Articles

COURT OF TAX APPEALS (CTA)

BIR’S ASSESSMENT IS CONCLUSIVE IF TAXPAYER FAILED TO FILE PROTEST WITHIN THE 30-DAY PERIOD; BUT BIR’S COLLECTION EFFORT MUST BE WITHIN THE 5-YEAR PERIOD FROM FLD/FAN ISSUANCE. The CTA has jurisdiction not only over disputed assessments but also over other matters arising under the NIRC, including BIR collection measures such as the levy and auction of real property; while a taxpayer generally has 30 days to protest an FLD/FAN, failure to do so makes the assessment final, executory, and demandable, but the finality of the assessment is distinct from the prescriptive period for its collection. Applying these rules, the CTA acquired jurisdiction because taxpayer timely filed its Petition and no prior administrative protest was necessary because the appeal concerned the BIR’s collection action rather than a disputed assessment. However, the deficiency EWT and DST assessments under the FLD/FAN were already conclusive because taxpayer failed to file a valid administrative protest within 30 days, thereby precluding it from subsequently challenging the assessments on their merits. Nevertheless, the BIR could no longer collect the assessed taxes because where the taxpayer failed to file the relevant returns, the BIR may assess within 10 years, but once an assessment is made, it must collect the assessed tax by distraint, levy, or court proceeding within five years from the assessment. Since taxpayer presented no evidence that it had filed the pertinent tax returns, the 10-year assessment period applied; nevertheless, the five-year collection period commenced upon service of the FLD/FAN. The BIR’s Warrant of Distraint and/or Levy was issued and the BIR seeking collection was filed only beyond the five-year period. the CTA held that prescription of collection may still be examined even though the assessment itself had become final and conclusive (City Government of Iligan v. Commissioner of Internal Revenue, CTA Case No. 11036, April 23, 2026)

QUESTIONS ON INTERLOCUTORY ORDERS OF THE CTA SHOULD BE RAISED WITH THE SUPREME COURT, NOT CTA EN BANC. The CTA En Banc has appellate jurisdiction only over final judgments, resolutions, or orders of a CTA Division, particularly resolutions on motions for reconsideration or new trial, and does not have jurisdiction over interlocutory orders issued while a case remains pending. An order is interlocutory when it resolves only a procedural or preliminary matter and leaves something further to be decided before the case can be finally disposed of. Applying these rules, the CTA En Banc held that the resolutions denying taxpayer’s request for an extension to file its Formal Offer of Evidence were interlocutory because they did not determine the merits of the case or terminate the proceedings; the CTA Division still had to continue hearing and resolve the main case, En Banc cannot entertain an appeal from an interlocutory ruling, nor may it exercise supervisory or certiorari jurisdiction over a CTA Division simply because the latter is conducting ongoing proceedings. This limitation prevents piecemeal appeals and unnecessary disruption of trial proceedings. The aggrieved party may instead proceed with the case before the Division and, if the eventual final judgment is adverse, raise the interlocutory ruling as an assigned error in an appeal to the En Banc; in exceptional cases involving grave abuse of discretion amounting to lack or excess of jurisdiction, the proper remedy is a Rule 65 petition for certiorari directly with the Supreme Court, not an immediate appeal to the En Banc. Since the main proceedings in the CTA Division had not yet been concluded and no final judgment existed, the petition was premature and the CTA En Banc dismissed it for lack of jurisdiction [Aeon Credit Services (Philippines), Inc. v. CIR, CTA En Banc Case No. 3091 (CTA Case No. 10693), April 30, 2026]

BIR MUST PROVE ACTUAL RECEIPT OF FLD/FAN IF TAXPAYER DENIES RECEIPT. An assessment must comply with due process, including proper service of the PAN and FLD/FAN, and where the taxpayer denies receipt, the CIR bears the burden of proving actual receipt by competent evidence; an assessment cannot become final and executory without proper service and receipt. Applying these rules, the CTA En Banc sustained the cancellation of the deficiency VAT assessment because the taxpayer categorically denied receiving the FLD/FAN and the BIR failed to present substantial evidence establishing that it was properly served and actually received. Although the BIR argued that the FLD/FAN was mailed to respondent’s registered address in Parañaque, the records showed that the BIR itself had already personally served the LOA, NIC, and PAN at the taxpayer’s new Makati address, demonstrating that it knew where taxpayer was located. More importantly, the BIR’s reliance on the old registered address and its presentation of an LBC courier receipt alone did not sufficiently prove service because the rules require the server’s written report under oath detailing the manner, place, and date of service and the relevant courier information. The disputable presumption that a properly mailed letter was received was likewise overcome by the taxpayer’s categorical denial, shifting the burden back to the BIR to prove actual receipt. Thus, there was no valid assessment, and the subsequent WDL could not be enforced. [Commissioner of Internal Revenue v. Diamond Drilling Corporation of the Philippines, CTA EB No. 3151 (CTA Case No. 10661), May 4, 2026]

REVENUE OFFICERS’ (RO) AUTHORITY MUST BE FROM A LOA, NOT FROM MEMORANDUM OF ASSIGNMENT (MOA). A valid LOA is required to clothe RO with authority to examine a taxpayer and recommend deficiency tax assessments, and only the RO specifically named in the LOA may conduct the examination; reassignment or substitution of revenue officers requires a new or amended LOA. Applying these rules, the CTA En Banc held that it could rule on the RO’s lack of authority even though the issue was raised only on appeal, since the rules authorize the CTA to resolve related issues necessary for the orderly disposition of a case. Although an initial LOA was issued by the Assistant Commissioner, the actual examination was conducted by ROs whose authority purportedly arose from a MOA signed by a Chief who was not among the officials authorized to issue LOAs. the CTA En Banc affirmed the cancellation of the assessments and the refund of tax [Commissioner of Internal Revenue v. Central Luzon Drug Corporation, CTA EB No. 3111 (CTA Case No. 10045), May 8, 2026]

BUREAU OF INTERNAL REVENUE

Revenue Memorandum Circular No. 98-2026

Coverage Covers non-micro taxpayers engaged in e-commerce/internet transactions, taxpayers under the LTS, Large Taxpayers under the EOPT framework, taxpayers using CAS/CBA with electronic invoicing or other invoicing software, and others subsequently required by the CIR.
Mandatory deadline Covered taxpayers must issue electronic invoices and comply with the Circular on or before December 31, 2026.
Voluntary adoption Taxpayers not yet mandatorily covered may voluntarily adopt electronic invoicing, subject to securing a PTI Electronic Invoice.
E-invoicing vs. sales reporting Electronic invoicing under Sec. 237 is separate from electronic sales reporting under Sec. 237-A. Sales reporting will be required only upon issuance of the BIR’s implementing rules.
Choice of system Taxpayers may use an in-house system, commercially acquired software, or an ESP.
Requirements for electronic invoice Must be generated by a registered/approved/accredited system, in structured electronic format, electronically transmitted to the buyer, and capable of producing data for BIR electronic sales reporting.
Word/Excel/Google Sheets Manually prepared invoices using Word, Excel, Google Docs, Google Sheets, or similar applications are not valid electronic invoices for tax compliance.
CAS/POS-generated invoice A CAS/POS-generated invoice that is merely printed is not an electronic invoice if the system cannot electronically transmit the invoice and required sales data. It is treated under non-electronic invoicing rules.
Structured format Electronic invoice data must be machine-readable and capable of automated processing. Taxpayers may use other structured formats internally, provided the data can be converted to the BIR-prescribed format.
JSON The BIR’s EIS uses JSON for transmission of sales data. Taxpayers may retain other internal formats if they can convert the required information into JSON.
Printing of e-invoice Electronic invoices may be printed for reference or record-keeping. A printed copy must be provided upon the buyer’s request.
Corrections An issued electronic invoice cannot be deleted, altered, or modified. Corrections must be made through a separate document referencing the original invoice.
Decrease in invoice Must be made through an authorized Credit Note/Memo.
Increase in invoice Must be made through issuance of a new electronic invoice.
Branches If the taxpayer is covered, the Head Office and all branches are generally required to comply. Compliance applies to the taxpayer as a whole.
Different systems per branch Different invoicing systems used by different branches, offices, or business segments require separate PTIs for each distinct system.
Additional branches An additional branch using the same approved system does not require a new PTI number, provided the BIR is properly notified.
System change Migration to, replacement of, or adoption of another invoicing system may require a new or amended PTI.
System downtime During system failure, Internet problems, power interruption, cybersecurity incidents, force majeure, or similar circumstances, the taxpayer must issue a BIR-authorized manual invoice.
After system restoration Manual invoices issued during downtime must subsequently be replaced with corresponding electronic invoices referencing the manual invoice numbers.
PTI application Covered taxpayers must secure a PTI before generating or issuing electronic invoices. Application is filed with the appropriate RDO/LT Office.
BIR processing BIR will evaluate a complete PTI application within 20 working days from receipt.
EIS Certification deadline EIS Certification must be secured within 6 months from issuance of the PTI. Failure may result in revocation of the PTI.
PTT A Permit to Transmit is required only when the Commissioner directs compliance with electronic sales reporting under Sec. 237-A. It is not automatically required merely because the taxpayer is implementing e-invoicing.
Tax classification changes Covered taxpayers generally continue complying with e-invoicing despite subsequent changes in classification unless the BIR expressly reclassifies or exempts them.
Upward reclassification A taxpayer moving to a higher classification must comply with the requirements applicable to the new classification within the period prescribed by BIR, which must be at least six months from reclassification.
Downward reclassification A taxpayer moving to a lower classification must continue complying with its previously approved electronic invoicing requirement.
Validity of e-invoice A compliant electronic invoice generated through an approved system with a valid PTI is recognized as proof of transaction and for tax substantiation purposes.
Effectivity The Circular takes effect immediately, with covered taxpayers required to comply with mandatory electronic invoicing by December 31, 2026.

BIR DEADLINES FROM SEPTEMBER 28, 2026 TO OCTOBER 4, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE  FILING/SUBMISSION
September 29, 2026 e-FILING & PAYMENT (Online/Manual) – BIR Form 1702Q (Quarterly Income Tax Return For Corporations, Partnerships and Other Non-Individual Taxpayers) and Summary Alphalist of Withholding Taxes (SAWT) – Fiscal Quarter ending July 31, 2026
September 30, 2026
SUBMISSION- Proof of eFiled BIR Form 1702–RT/1702-EX/1702-MX with Audited Financial Statements (AFS), 1709 (if applicable), and Other Attachments through Electronic Audited Financial Statements (eAFS)– Fiscal Year ending May 31, 2026
SUBMISSION- Soft Copies of Inventory List and Schedules stored and saved in DVD-R/USB properly labeled together with Notarized Sworn Declaration – Fiscal Year ending August 31, 2026
e-SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers. eFPS Filers – Fiscal Quarter ending August 31, 2026
ONLINE REGISTRATION (thru ORUS) – Computerized Books of Accounts and Other Accounting Records – Fiscal Year ending August 31, 2026
October 1, 2026
SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers. September 16-30, 2026
SUBMISSION – Engagement Letters and Renewals or Subsequent Agreements for Financial Audit by Independent CPAs. Fiscal Year beginning December 1, 2026 

COURT OF TAX APPEALS (CTA) DECISIONS

LOA SERVED 860 DAYS AFTER ISSUANCE AND THE APPLICABLE 180-DAY AUDIT PERIOD HAD ALREADY EXPIRED RENDERS THE ASSESSMENT VOID. A revenue officer may examine a taxpayer and recommend a deficiency assessment only pursuant to a valid Letter of Authority (LOA), while the regulations require the LOA to be served within 30 days from issuance, otherwise it becomes null and void unless revalidated; consistent with this, the Supreme Court held that an unserved LOA that remains outstanding beyond 30 days becomes wholly unenforceable absent revalidation. Here, the LOA was served 860 days after issuance, with no showing that it had been revalidated. The Court therefore found that the LOA had already become void and unenforceable when served. Although the BIR regulations subsequently deleted the 30-day service requirement, and clarified that an LOA served beyond 30 days may still be considered valid, the Circular expressly limits this to cases where the applicable 180-day/240-day period for completion of the audit has not yet expired. That saving provision did not benefit the BIR because, when the LOA was eventually served, the 180-day audit period had already expired. The taxpayer’s failure to update its address and the BIR’s alleged difficulty in locating it likewise did not preserve the validity of the already expired LOA. Since the audit and examination were therefore conducted without a valid and enforceable LOA, the resulting deficiency assessment was void and ineffectual. (Floorcompany, Inc., v. Commissioner of Internal Revenue (“CIR”), CTA Case No. 11050, April 29, 2026)

LOA IS REQUIRED FOR AN ASSESSMENT OUTSIDE THE COVERED PERIOD; BIR CANNOT VALIDLY ARGUE THAT NEW LOA IS UNNECESSIARY FOR VAT ASSESSMENT DUE TO UTILIZATION OF EXCESS INPUT VAT. An RO may examine a taxpayer and perform assessment functions only pursuant to a valid LOA issued by the CIR or a duly authorized RD, and the LOA must identify the taxable period covered because it defines the extent of the RO’s authority and protects the taxpayer’s right to due process. The Supreme Court emphasized that an assessment made pursuant to an invalid LOA, or beyond the authority granted therein, is void and ineffectual; the RO cannot assess a taxpayer for a taxable period not covered by the LOA, since the RO must obtain another LOA if the BIR intends to expand the audit period. A LOA is required even when the BIR does not physically examine the taxpayer’s books, because the requirement depends on whether the taxpayer is subjected to an examination or audit, not on the manner by which the BIR obtains or verifies the information used in the assessment. Here, the BIR issued LOA authorizing the examination of books of accounts and other accounting records for all internal revenue taxes. Despite this limited authority, the BIR issued an Assessment Letter and a Denial of Protest for alleged deficiency VAT for the quarter ended June 30, 2021, a period clearly outside the coverage of the LOAs. The CIR argued that a new LOA was unnecessary because the deficiency VAT assessment resulted from utilization of excess input taxes rather than from an examination of books and accounting records. The Court rejected this argument, explaining that the BIR cannot avoid the LOA requirement simply by relying on information or systems that do not involve a physical examination of the taxpayer’s books; once the taxpayer is subjected to an examination or audit, the statutory requirement for prior authorization applies. Thus, the BIR should have issued another LOA specifically authorizing the examination and assessment for the quarter ended June 30, 2021. [CIR v. PMFTC, Inc., CTA EB No. 3009 (CTA Case No. 10714), April 13, 2026]

A TAXPAYER MAY BE TREATED AS CBL ONLY UPON PROOF OF THE REQUIRED BIR TAGGING AND PUBLICATION; THUS, WHERE THE BIR SHOWED ONLY CERTIFICATIONS OF UNSUCCESSFUL LOCATION EFFORTS BUT FAILED TO PROVE ACTUAL CBL DESIGNATION AND PUBLICATION, THE LOA REMAINED SUBJECT TO THE 30-DAY REVALIDATION AND 180-DAY AUDIT PERIODS, RENDERING IT AND THE RESULTING ASSESSMENTS VOID. A taxpayer may be given “Cannot Be Located” (CBL) status only after the BIR makes efforts to locate the taxpayer and obtains certifications from at least two specified offices or organizations that the taxpayer does not appear in their records; the taxpayer’s CBL status must then be reflected in the BIR records and submitted for publication on the BIR website and in at least two newspapers of general circulation. Here, although the BIR obtained certifications from the Makati City Business Permits Office and Barangays San Isidro and Bangkal indicating that taxpayer was not registered in their respective records, these certifications merely established efforts to locate taxpayer and did not prove that taxpayer was actually tagged as CBL in the BIR’s records. The only evidence offered was a Memorandum recommending that taxpayer be included in the CBL list and that the matter be referred for publication; the BIR presented no evidence that the CBL designation was actually made, or that taxpayer’s name was submitted and published on the BIR website and in at least two newspapers. The Court could not consider evidence that had not been formally offered. Consequently, the BIR failed to establish the factual predicate for exempting the LOA from the 30-day revalidation requirement and the 180-day audit-completion period. The LOA was therefore void, and because the assessments for taxable year 2017 were issued pursuant to an invalid LOA, they were likewise unenforceable and had to be cancelled and set aside. (Floorcompany, Inc., v. CIR, CTA Case No. 11050, April 29, 2026)

A WDL IS VALID ONLY WHEN THE TAX LIABILITY IS FINAL AND EXECUTORY; THUS, WDLS ARE PREMATURE BECAUSE THE TAXPAYER’S MR OF THE FDDA REMAINED PENDING; TAXPAYER CANNOT VALIDLY CHALLENGE THE ASSESSMENT FOR LACK OF A FINAL CIR DECISION. The Court of Tax Appeals has jurisdiction over “other matters” arising under the NIRC, including the validity of a Warrant of Distraint and/or Levy (“WDL”), but the BIR may resort to summary collection remedies only when the taxpayer’s liability has become delinquent, final, and executory, whether arising from self-assessed taxes or a final deficiency assessment. Here, the taxpayer received the second WDL and filed its Petition within the 30-day period; the first WDL was refused because its Motion for Reconsideration (“MR”) of the Final Decision on Disputed Assessment (“FDDA”) was still pending. The Court held that both WDLs were premature because the deficiency assessment had not become final and executory: the taxpayer timely protested the FLD/FAN, submitted supporting documents, and elevated the denial of its protest through an MR to the CIR. Collection through a WDL presupposes a final and executory liability; thus, the BIR could not enforce the assessment while the taxpayer’s administrative remedy remained pending. However, the Court could not rule on the merits of the deficiency assessment because, after denial of a protest by an authorized representative of the CIR, the taxpayer may either appeal to the CTA within 30 days or seek reconsideration from the CIR, and these remedies are mutually exclusive. Having chosen the latter, the taxpayer had to await the CIR’s action on its MR before seeking judicial review. Moreover, only one 180-day period is available for the CIR or his authorized representative to act, reckoned from submission of the supporting documents; the subsequent MR did not create a new 180-day period. Accordingly, the Court cancelled and set aside the WDLs and ordered the BIR to cease collection until the assessment becomes final and executory, but dismissed the Petition insofar as it sought review of the deficiency assessment, there being no final CIR decision on the pending MR. (Ivonclar Vivadent, Inc. v. CIR, CTA Case No. 11253, April 20, 2026)

TAXPAYER SHOULD APPEAL THE FDDA SIGNED BY THE CIR HIMSELF TO THE CTA; MOTION FOR RECONSIDERATION WILL NOT TOLL THE PERIOD. The CTA has jurisdiction over disputed assessments only when the taxpayer timely protests the assessment and timely appeals the CIR’s final decision to the CTA, while “other matters  include challenges to BIR collection remedies such as WDL and Warrant of Garnishment (“WOG”). Here, the CTA En Banc ruled that the original Petition for Review was only partly within the CTA’s jurisdiction. The FDDA signed by the CIR (Dulay) constituted the CIR’s final decision on taxpayer’s protest and the taxpayer should have appealed the FDDA to the CTA. Instead, taxpayer filed a letter-reply/motion for reconsideration with the CIR, which did not suspend or extend the period to appeal. Consequently, the assessments became final, executory, and demandable, depriving the CTA of jurisdiction to review their validity. The Court nevertheless recognized jurisdiction over the WOGs as “other matters.” The WDL, however, was challenged beyond the 30-day period; hence, the CTA had no jurisdiction over the WDL. In contrast, the WOGs were received within 30-day period deadline, giving the CTA jurisdiction over them. On the merits, the Court sustained the WOGs because taxpayer could not use a challenge to the collection remedy to indirectly reopen an assessment that had already become final. Taxpayer’s separate argument that the first LOA was invalid because it was served more than 30 days after issuance without revalidation was likewise rejected. The taxpayer did not object to the alleged defect when the LOA was served, nor did it raise the issue in its protest or original CTA petition; it surfaced only during cross-examination and was formally raised much later in a memorandum. Because the first LOA was valid, taxpayer’s challenge to the waivers extending the period to assess also failed. Accordingly, the CTA En Banc partially dismissed the Petition for lack of jurisdiction insofar as it sought nullification of the assessment and WDL, but denied it on the merits [Pentagon Gas Corporation v. CIR, CTA EB No. 3089 (CTA Case No. 10868), April 20, 2026]

15-DAY PERIOD TO FILE APPEAL TO CTA EN BANC IS RECKONED FROM DATE OF RECEIPT OF OSG, NOT BY THE BIR A Petition for Review to the CTA En Banc must be filed within 15 days from receipt of the Division’s resolution, with extension available only upon proper motion. Where the OSG is the government’s principal counsel, receipt by the OSG controls the appeal period, even if the resolution is received later by deputized BIR counsel. Thus, receipt by the OSG started the 15-day period, and petition filed by the BIR outside the 15-days period is dismissible. [CIR v. Sumitomo Corporation – Manila Branch, CTA EB No. 2998 (CTA Case No. 10412, April 7, 2026]

IN A DE NOVO CTA PROCEEDING, DOCUMENTS MERELY SUBMITTED DURING THE BIR AUDIT HAVE NO EVIDENTIARY VALUE ABSENT FORMAL OFFER; THUS, WHERE THE TAXPAYER FAILED TO FORMALLY OFFER THE ORS/SIS SUPPORTING ITS INPUT VAT CLAIM, THE CTA SUSTAINED THE DISALLOWANCE FOR FAILURE TO PROVE THE ASSESSMENT ERRONEOUS. The CTA is a court of record where cases are litigated de novo, requiring taxpayers to formally offer competent evidence to substantiate their claims; likewise, under the rules on evidence, allegations are not evidence and the burden of proof rests on the party asserting the claim. Here, the CIR disallowed input VAT because the supporting ORs and SIs were either missing or issued by non-VAT suppliers, and although taxpayer claimed that the documents were submitted during the BIR audit and that the amounts were instead treated as expenses/COS, it failed to formally offer the alleged ORs and SIs before the CTA. Since documents merely submitted to the BIR have no evidentiary value absent formal offer in court, taxpayer failed to prove that the assessment was erroneous; thus, the CTA sustained the disallowance of the unsupported input VAT (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

INPUT VAT IS CREDITABLE ONLY UPON COMPLIANCE WITH PRESCRIBED INVOICING REQUIREMENTS. A taxpayer claiming input VAT must establish that the supporting VAT invoices/official receipts comply with the prescribed invoicing requirements, including the nature of payment/service, TIN, address, VAT breakdown, and other required details; input tax on local purchases of goods is creditable upon consummation of the sale, not upon payment. Here, the CTA found that taxpayer’s supporting invoices/receipts failed to comply with these requirements, and taxpayer could not shift the burden to its suppliers because it was incumbent upon it to exercise due diligence in ensuring that its documents were compliant; its cash-flow records also could not cure the absence of the required information. However, the Court cancelled the disallowance because the records showed that the taxpayer’s TIN was actually reflected in the supporting document. The Court likewise upheld the disallowance in “out-of-period” input VAT because the purchases involved goods acquired in a different year, for which the input tax became creditable upon consummation, rather than upon payment. Accordingly, the CTA sustained the invoicing-related disallowance (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

TAXPAYER MUST CLEARLY RECONCILE ALLEGATION OF OVERCLAIMED INPUT VAT BY SUBMITTING RELEVANT AND VERIFIABLE SOURCE DOCUMENTS . The CTA is a court of record conducting trials de novo, and the taxpayer bears the burden of proving that an assessment is erroneous; assessments are prima facie presumed correct and made in good faith. Here, the BIR determined an overclaimed input VAT by comparing the Global Sources of Input Tax (GSIT) reflected in taxpayer’s AFS/AITR with the sources of input tax reported in its VAT returns. Although taxpayer presented reconciliations and claimed that its importation input VAT was supported by 664 pages of importation documents and that differences arose from the use of landed cost versus amounts recorded in the AFS/AITR, it failed to present the underlying importation documents and other supporting records necessary to verify these explanations and failed to adequately explain the variances in its reconciliations. Since the reconciliations, without the relevant source documents, could not be independently verified, and evidence not formally offered cannot be considered, taxpayer failed to discharge its burden of proving the assessment erroneous; thus, the CTA sustained the disallowance for overclaimed input tax. (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

REVENUE ISSUANCES

Pursuant to Revenue Memorandum Circular (RMC) No. 97-2026 and under the National Internal Revenue Code (NIRC) of 1997, as amended, allowable system loss charges billed by electric distribution utilities to consumers are excluded from the 12% Value-Added Tax (VAT) computation to directly reduce end-user energy costs.

Date of Issuance September 14, 2026
Effectivity Immediately; applied prospectively from its effectivity and from the effectivity of ERC Resolution No. 26, Series of 2026, pursuant to Sections 12, 14, and 17 thereof
Nature of System Loss Charge The allowable System Loss Charge, within the cap approved by the ERC, is treated as a government-mandated pass-through cost
VAT Treatment The allowable System Loss Charge is excluded from Gross Sales for VAT purposes and is therefore not subject to output VAT
Creditable Withholding VAT (CWVAT) Since the allowable System Loss Charge is excluded from VATable gross sales, it is likewise not subject to CWVAT
Income Tax Treatment Unchanged. The VAT exclusion does not extend to income tax or the corresponding creditable withholding tax
Separate Identification The allowable System Loss Charge must be separately identified in the billing statement, invoice, or similar document
ERC Compliance Taxpayers must comply with applicable ERC rules and regulations governing the allowable System Loss Charge
Tax Compliance Taxpayers must comply with the relevant invoicing and gross sales provisions of the Tax Code and its implementing rules and regulations
Billing and Accounting Affected taxpayers must ensure proper billing, accounting, reporting, and disclosure of the System Loss Charge
Covered taxpayers –   must separately identify and properly account for the allowable System Loss Charge
  • Generation Companies (GenCos)
  • National Grid Corporation of the Philippines (NGCP)
  • Distribution Utilities (DUs)
Electric Cooperatives Covered taxpayer; must comply with the applicable ERC and tax requirements
Other Affected Taxpayers Must likewise ensure proper billing, accounting, reporting, and separate identification of the allowable System Loss Charge
Key Limitation The exclusion is for VAT purposes only; it does not mean that the System Loss Charge is excluded from taxable income or from income-tax withholding

BIR DEADLINES FROM SEPTEMBER 21, 2026 TO SEPTEMBER 27, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE  FILING/SUBMISSION
September 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayer. Non-eFPS Filers – Fiscal Quarter ending August 31, 2026
Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products – Fiscal Quarter ending August 31, 2026 
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550Q (Quarterly Value-Added Tax Return). eFPS & Non-eFPS Filers – Fiscal Quarter ending August 31, 2026
BIR Form 2551Q (Quarterly Percentage Tax Return) – eFPS & Non-eFPS Filers. Fiscal Quarter ending August 31, 2026
BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider). Fiscal Quarter ending August 31, 2026 

COURT OF TAX APPEALS (CTA) DECISIONS

REASSIGNMENT OF AUDIT TO ANOTHER EXAMINER PRIOR TO THE PAN-STAGE REQUIRES A NEW LETTER OF AUTHORITY (LOA); MEMORANDUM OF ASSESSMENT ISSUED BY A REVENUE DISTRICT OFFICER IS NOT SUFFICIENT. The Tax Code requires that the examination of a taxpayer’s books be conducted only by revenue officers specifically authorized under a valid LOA; an LOA is a special authority granted to particular revenue officers, not a general authority that may be used by any BIR officer. The Supreme Court held that the reassignment or substitution of revenue officers without a new or amended LOA violates the taxpayer’s right to due process and usurps the statutory authority of the CIR or his duly authorized representative. Any reassignment or transfer of a case to other revenue officers requires the issuance of a new LOA. Here, the examiners, who conducted the examination and recommended the issuance of the PAN, were not authorized under a valid LOA; their supposed authority rested only on Memorandum of Assignment issued by the Revenue District Officer, which could not substitute for an LOA. The subsequent LOA likewise did not cure the defect because it was issued long after the PAN. Thus, the PAN issued based on the unauthorized examination was void for lack of valid authority and violation of due process. [(Ammex I-Support Corporation v. Commissioner of Internal Revenue (CIR), CTA Case No. 11192, April 17, 2026)]

PHRASES IN THE ASSESSMENT NOTICE “YOU ARE REQUESTED TO PAY” OR “IF YOU ARE AMENABLE” DO NOT NEGATE DEMAND TO PAY; ASSESSMENT REMAINS VALID. A valid assessment must constitute a written notice and demand for a definite tax liability and must indicate a clear due date for payment, because the demand signals when penalties and interest accrue and informs the taxpayer of its remedies. Applying these principles, the CTA held that the FLD and FAN contained an unequivocal demand despite using the phrase “you are requested to pay,” since a demand may properly take the form of a request for payment; here, the FAN stated a definite amount and expressly provided June 30, 2022 as the payment deadline. Moreover, the title “Formal Letter of Demand” itself indicated the CIR’s intention to demand payment, and the phrases “you are requested to pay” and “if you are amenable” did not negate the demand. Thus, the assessment notices validly demanded payment of the deficiency taxes. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

3-YEAR PRESCRIPTIVE PERIOD WAS EXTENDED BY 420 DAYS DUE TO COVID-19  PANDEMIC. Internal revenue taxes must generally be assessed within 3 years from the last day prescribed for filing the return or the actual filing date, whichever is later, subject to the suspension provisions; during the COVID-19 pandemic, various legislations/regulations validly suspended the running of the prescriptive period during the specified ECQ/MECQ period. Applying these rules, although the original 3-year periods for 2018 income tax, VAT, WTC, and EWT liabilities had generally expired before the FLD was issued, the CTA held that the applicable COVID-19 suspensions validly extended the prescriptive periods by 420 days; consequently, the BIR’s right to assess remained timely for all the deficiency taxes involved, before the FLD was issued and received (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

TAXPAYER WAS NOT LIABLE FOR 30% RCIT ON PAGCOR’S USE OF THE CORPORATE OFFICES BECAUSE THE LEASE EXPRESSLY PROVIDED THAT SUCH USE WAS WITHOUT ADDITIONAL RENT. Income derived from taxable activities is subject to regular corporate income tax, while the tax treatment of PAGCOR-related income depends on the nature of the income actually earned; the CIR treated rental income from PAGCOR as subject to 30% RCIT on the theory that the reported rent supposedly covered both the gaming area and the corporate offices, with only the former being connected to exempt gaming activities. The CTA, however, found no factual or contractual basis for imputing rental income to the corporate offices because the Lease Agreement expressly provided that the rent pertained to the gaming premises, and that, upon payment of the stipulated rent, PAGCOR could continue using the Office Premises “without any further charge or payment therefor.” Thus, the taxpayer actually derived rental income only from the gaming premises and did not earn any additional rental income from PAGCOR’s use of the corporate offices. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

DISALLOWANCE OF MCIT CARRY-OVER WITHOUT EXPLANATION IS VOID. An assessment is void unless the taxpayer is informed in writing of the factual and legal bases thereof, as this is a substantive and mandatory requirement. Here, the FLD deducted the MCIT and income tax carried over to 2019 from the taxpayer’s total tax credits/payments, effectively disallowing these amounts, but failed to explain the factual and legal basis for their disallowance; thus, the taxpayer was not adequately informed of why these tax credits were rejected, rendering the corresponding assessment items void. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

INTEREST INCOME FROM A LOAN BY REAL ESTATE BUSINESS IS NOT SUBJECT TO VAT; BIR MUST PROVE INTEREST INCOME’S CONNECTION TO THE MAIN BUSINESS. VAT applies to services rendered in the course of trade or business, including transactions incidental thereto, but a transaction may be considered incidental only when there is an intimate connection between it and the taxpayer’s main business activity; moreover, interest income from loans is generally subject to VAT when earned by a lending investor, dealer in securities, financial institution, or an entity performing similar financing activities. Here, the taxpayer was principally engaged in the purchase, development, leasing, management, and sale of real and personal properties, and was not a lending investor, dealer in securities, or financial institution; although the interest income from its loan could potentially be VATable if the loan transaction were incidental to its business, the BIR failed to establish any clear relation or intimate connection between the loan and taxpayer’s main real estate business, merely stating that the income was not among its exempt activities. Thus, absent proof that the loan was incidental to petitioner’s VATable business, the interest income was not subject to VAT. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

PROCEEDS FROM DISPOSAL OF PROPERTY BY PAGCOR CONTRACTEE ENGAGED IN REAL ESTATE IS SUBJECT TO VAT. The tax exemption extended to PAGCOR contractees applies only to earnings derived from casino/gaming operations conducted under the PAGCOR franchise, while income from other activities remains subject to tax; likewise, transactions incidental to a taxpayer’s main business may be subject to VAT under the NIRC. Here, although the  proceeds from the disposal of property and equipment involved equipment previously used in casino operations, and the sale itself did not constitute earnings derived from PAGCOR’s gaming operations the disposal was considered a transaction incidental to petitioner’s business of purchasing, leasing, and selling real and personal properties, making the proceeds subject to VAT. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

RENTAL INCOME FROM PAGCOR’S USE OF CORPORATE OFFICE IS NOT SUBJECT TO VAT IF LEASE AGREEMENT PROVIDES THAT PAGCOR WILL NOT PAY RENT FOR THE USE THEREOF. Under the PAGCOR Charter and the Lease Agreement between the taxpayer and PAGCOR, only actual or constructively received rent income may be subjected to VAT. Here, rental income was based on the assumption that a portion of PAGCOR’s rent payments pertained to its use of the corporate offices, allegedly outside the exempt gaming activities; however, the lease agreement expressly provided that PAGCOR would incur no charge or further payment for its use of the Office Premises, resulting in no actual or constructive receipt of rent income by petitioner. Thus, there was no VATable rental income arising from PAGCOR’s use of the corporate offices, and the VAT assessment was cancelled. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

DISALLOWANCE OF INPUT VAT CARRY-OVER WITHOUT EXPLANATION IS VOID. An assessment or disallowance is void when the taxpayer is not informed in writing of the factual and legal bases thereof. Here, the BIR deducted input tax carried over to 2019 from the computed VAT due, effectively disallowing the amount and increasing the basic deficiency VAT, but neither the FLD nor the Details of Discrepancies stated the factual or legal basis for such disallowance. Accordingly, the disallowance of input tax carry-over was void, and after allowing the input tax credits, the taxpayer’s credits were sufficient to cover its output VAT for CY 2018, resulting in no basic deficiency VAT liability. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR CANNOT VALIDLY ASSESS TAXPAYER FOR FAILURE TO REFUND EXCESS WITHHOLDING TAX TO EMPLOYEES; BIR’S ASSESSMENT BASED ON MERE COMPARISON OF ALPHALIST AND AFS WITHOUT EXAMINING THE NATURE OF THE ACCOUNTS IS VOID. The penalty imposed on an employer or withholding agent applies when it fails or refuses to refund excess withholding tax to an employee, and does not provide a basis for assessing additional withholding tax merely from discrepancies in compensation expenses. Here, the BIR assessed deficiency WTC based on a discrepancy between compensation expenses reflected in taxpayer’s AFS and amounts reported in its Alphalist/BIR Form 1601-C, but its reliance on Section 252 was misplaced because that provision concerns the non-refund of excess withholding tax, whereas the assessment sought to impose additional withholding tax. The assessment also lacked sufficient factual basis because the amount taken from the Alphalist included non-taxable compensation, yet the BIR simply compared this amount with selected salary and payroll-related accounts in the AFS and treated the entire difference as compensation subject to WTC without examining the nature and taxability of the individual accounts. Thus, the BIR failed to establish both the legal authority and factual basis for the assessment, rendering the deficiency WTC assessment devoid of merit and subject to cancellation. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S EWT ASSESSMENT BASED ON MERE COMPARISON OF BOOKS/AFS AND WITHHOLDING TAX RETURN IS VOID; BIR MUST IDENTIFY THE SPECIFIC TRANSACTIONS AND NATURE OF INCOME PAYMENTS. An assessment must inform the taxpayer in writing of the specific factual and legal bases upon which it is made; otherwise, the assessment is void for failure to satisfy the statutory and constitutional requirements of due process. Here, the BIR assessed deficiency EWT based on discrepancies between the taxpayer’s expenses per books/AFS and its BIR Form 1601-E returns, classifying the alleged discrepancies as purchases of goods, purchases of services, rent, and professional fees and applying different EWT rates. However, the BIR merely invoked Section 57(B) of the NIRC and Section 2.57.2 of RR No. 2-98 without identifying the specific transactions covered, the nature of the income payments, the identities or classes of payees, or the particular subsection of Section 2.57.2 that prescribed the applicable withholding rate. This was insufficient because Section 2.57.2 contains several subsections covering different types of income payments and payees, each with corresponding EWT rates; thus, a general reference to the provision did not enable the taxpayer to determine which transactions were allegedly subject to EWT, why they were taxable, and how the rates were applied. Accordingly, the deficiency EWT assessment was declared void for failure to sufficiently state its factual and legal bases. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S DST ASSESSMENT (1) ON LOAN BASED ON YEAR-END BALANCE (2) PRIOR YEAR LEASE AND (3) RENT-FREE USE OF OFFICE IS VOID. DST is imposed on taxable debt instruments and certain lease agreements; however, a tax assessment must be supported by actual facts and transactions, rather than presumptions. Here, the BIR assessed deficiency DST by treating the year-end balances of taxpayer’s “Amounts owed by/to related party” accounts as loans or advances subject to DST. The Court found this improper because the amounts represented year-end balances, and the corresponding accounts already had substantial beginning balances, indicating that the amounts could have arisen from transactions in prior years. The BIR failed to determine whether the balances represented new loans or advances actually made during the year and did not present supporting documents, such as instructional letters, memoranda, vouchers, or other evidence establishing the existence of taxable loan transactions. The Court stressed that assessments cannot rest on reasonable or logical presumptions but must be grounded on actual facts. The DST assessments on the parking-area lease income and rental expense involving, respectively, were likewise improper because the relevant lease agreements were executed in prior years. Finally, the DST on alleged rent income was unfounded because the taxpayer did not receive any additional rent for PAGCOR’s use of the Office Premises, while the PAGCOR Gaming Premises lease was executed in prior year and was exempt from DST under the PAGCOR Charter. Accordingly, the BIR failed to establish that the assessed transactions were taxable DST transactions occurring within the audit period, and the entire deficiency DST assessment was cancelled. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S FAILURE TO ADDRESS TAXPAYER’S ARGUMENTS IN THE PAN RENDERS THE ASSESSMENT VOID. The Tax Code requires that the taxpayer be informed in writing of the factual and legal bases of the assessment and that its defenses and supporting evidence be meaningfully considered; otherwise, the assessment is void for violation of administrative due process. The Supreme Court held that due process requires not merely an opportunity to be heard but also that the BIR actually consider and address the taxpayer’s explanations, with reasons stated for rejecting them. Here, the taxpayer filed a reply to the PAN, raising factual and legal arguments against the proposed assessment, but the subsequent FAN/ANs neither acknowledged nor addressed taxpayer’s arguments and were substantially identical to the PAN, except for the computation of interest. The subsequent protest against the FAN/ANs did not cure the defect because the denial of due process had already occurred at the assessment stage. Accordingly, the FAN/ANs were null and void, and the assessment and subsequent decision were cancelled and set aside. [(Ammex I-Support Corporation v. CIR, CTA Case No. 11192, April 17, 2026; Abraham Holdings, Inc.(Formerly Armadillo Holdings, Inc.) v. CIR, CTA Case No. 11088, June 8, 2026; Ozamiz City v. CIR, CTA Case No. 10828, June 18, 2026; CIR v. Marina Square Properties, Inc., CTA EB No. 3051, CTA Case No. 13049, May 21, 2026; Konica Minolta Marketing Services (Philippines) Inc., v. CIR,  CTA Case No. 10908, May 26, 2026; CIR v. United Graphic Printing Corporation, CTA Eb No. 3142, CTA Case No. 10610, May 26, 2026; CIR v. Serbiz Multi-Purpose Cooperative, CTA EB No. 3057, CTA Case No. 10369, May 28, 2026; CIR v. Justice Maria Lourdes P.A. Sereno, CTA EB No. 2996, CTA Case No. 10792, April 23, 2026; CIR v. Plastic Container Packaging Corporation, CTA EB No. 3039 (CTA Case No. 10095), April 22, 2026; CIR v. Neuftech Philippines, Inc., CTA EB No. 3012, CTA Case No. 10442, May 7, 2026)]

3-YEAR ASSESSMENT PERIOD APPLIES IF BIR FAILS TO PROVE FRAUDULENT INTENT. The extended prescriptive period applies only in cases of a false or fraudulent return with intent to evade tax or failure to file, while absent fraud or intentional falsity, the applicable period to collect an assessed tax is 3 years from the assessment. Here, the BIR failed to establish that taxpayer deliberately falsified her returns or intended to evade taxes; rather, she filed her AITRs, voluntarily paid income taxes, and reasonably relied on the BIR Form 2316 and tax withholdings of her employer, the Supreme Court, as statutory withholding agent. Thus, the alleged errors did not constitute fraud, making the extended prescriptive period inapplicable. (CIR v. Justice Maria Lourdes P.A. Sereno, CTA EB No. 2996, CTA Case No. 10792, April 23, 2026)

COOPERATIVE’S TAX EXEMPTION RETROACTS TO THE DATE OF ITS REGISTRATION. For cooperatives, while the law provides that tax exemption generally takes effect upon issuance of the Certificate of Tax Exemption, the initial issuance of such certificate is retroactive to the date the law took effect, provided that the cooperative was registered with the Cooperative Development Authority (CDA). Here, the taxpayer was registered with the CDA in 2009, and its Certificate of Tax Exemption issued in 2012 was its first certificate; hence, the certificate’s effectivity retroacted to 2009, making taxpayer exempt from income tax and VAT beginning taxable year 2009 despite the certificate being issued only in 2012. Thus, the taxpayer was not liable for the deficiency taxes assessed for TY 2009, CIR v. Serbiz Multi-Purpose Cooperative, CTA EB No. 3057, (CTA Case No. 10369) May 28, 2026)]

RECEIPT OF THE FORMAL LETTER OF DEMAND/FINAL ASSESSMENT NOTICE (FLD/FAN) PRIOR TO EXPIRATION OF 15-DAY PERIOD TO REPLY TO THE PAN RENDERS THE ASSESSMENT VOID. A taxpayer must be given 15 days from receipt of the PAN to submit a reply, and the BIR must wait for the taxpayer’s response or the lapse of the 15-day period before issuing the FLD/FAN; here, the taxpayer received the PAN on January 4, 2013, as shown by the notation on the PAN itself, giving it until January 21, 2013 to respond because the 15th day fell on a Saturday. However, the BIR issued the FAN on January 14, 2013, seven days before the expiration of the response period, thereby prematurely terminating respondent’s statutory opportunity to contest the PAN. The BIR’s unsupported claim that the PAN was served on December 28, 2012 was insufficient, as it presented no proof of service, while the PAN itself indicated receipt on January 4, 2013. The subsequent filing of a protest and administrative appeal did not cure the defect. [CIR v. Kuehne + Nagel, Inc., CTA EB No. 3024 (CTA Case No. 10216), April 15, 2026]

TAXPAYER CANNOT REFUND AN ERRONEOUSLY PAID IN A TAX ASSESSMENT CASE. SEE DISSENTING OPINION. A taxpayer seeking a refund or tax credit of erroneously or illegally collected taxes must first file a written administrative claim with the CIR, and both the administrative and judicial claims must be filed within two years from the date of payment; this two-year period is mandatory and jurisdictional. Here, the taxpayer paid tax during the reinvestigation of its TY 2009 assessment. Although the Court in Division subsequently found that the payments were made pursuant to a void assessment and ordered their refund, the Court En Banc held that the CTA had no jurisdiction to grant such relief. Moreover, with respect to all the payments, the taxpayer failed to file a written claim for refund or tax credit with the CIR within two years and did not even allege or pray for a refund in its Petition for Review. Accordingly, the En Banc modified the Division’s decision by deleting the refund/TCC while affirming that the assessments were void. Dissenting Opinion: The CTA has jurisdiction not only over disputed assessments and refund cases, but also over “other matters arising under the NIRC” or laws administered by the BIR. Moreover, it may resolve related issues necessary for the complete and orderly disposition of the case. Lastly, the period should be relaxed because of the peculiar circumstances of the case. Strict procedural rules should not be applied where they would allow the government to retain taxes it had no legal right to collect. [CIR v. Kuehne + Nagel, Inc., CTA EB No. 3024 (CTA Case No. 10216), April 15, 2026]

A SUBSEQUENT LOA IS VOID IF IT COVERS A PERIOD UNDER AN EARLIER LOA, WHICH HAS BEEN FULLY SETTLED. For income tax purposes, the examination and inspection of a taxpayer’s books shall be conducted only once in a taxable year, subject to limited exceptions, while the BIR regulations provide a “One LOA per Taxable Year” rule by generally allowing only one LOA for the same taxpayer, tax type, and period, except when a subsequent LOA is justified by circumstances such as the reassignment, retirement, or inability of the originally assigned revenue officers to continue the investigation. Applying these rules, the third LOA was infirm because it substantially overlapped with the period already examined under the First and Second LOAs. Moreover, none of the recognized exceptions justified the third LOA: even the alleged fraud, irregularity, or mistake had already been investigated under the Second LOA, and the alleged undeclared gain from the sale of land and improvements – which became the basis for the ad valorem penalties under the third LOA – had already been considered and ultimately abandoned in the FDDA issued under the Second LOA. More importantly, the assessments under the second LOA had already become final and were fully settled when taxpayer voluntarily paid the assessed deficiency taxes. thereby closing the audit and assessment process. Thus, the Third LOA improperly attempted to reopen and reassess matters that had already been examined, resolved, abandoned, and paid, in violation of the “One LOA per Taxable Year” rule and the principles of finality of assessments and orderly tax administration; consequently, the third LOA was void, and all assessments issued pursuant thereto were likewise void and without legal effect. [Orica Nitrates Philippines, Inc. v. CIR, CTA Case No. 10946, (April 15, 2026)]

BIR’S FAILURE TO INDICATE THE DUE DATE IN THE FAN RENDERS THE ASSESSMENT VOID. The Tax Code mandates that the taxpayer be informed in writing of the facts and law upon which an assessment is based, and jurisprudence establishes that a valid formal assessment must contain not only the computation of the tax liability but also a definite demand for payment within a prescribed period. A FAN that fails to state a definite due date is not a valid assessment because the due date determines when the taxpayer must pay, when penalties and interest may accrue, and allows the taxpayer to determine and exercise the proper remedies. Here, the FLD dated merely instructed taxpayer to pay the ad valorem penalties “within the time shown in the assessment notice,” but the FAN itself contained no due date, with the corresponding field left blank. Thus, there was no date certain or specific period within which petitioner was required to pay, resulting in the absence of a valid demand for payment. (Orica Nitrates Philippines, Inc. v. CIR, CTA Case No. 10946, April 15, 2026)

FLD/FAN ISSUED 10-DAYS AFTER THE RECEIPT OF THE PAN RENDERS THE ASSESSMENT VOID. The Tax Code requires the BIR to issue a PAN informing the taxpayer of the facts and law supporting the proposed deficiency assessment and to give the taxpayer 15 days from receipt of the PAN to respond before the FLD/FAN may be validly issued; these requirements are substantive due process safeguards, and failure to strictly comply renders the assessment void. In this case, the BIR issued the PAN but issued the FLD/FAN only 10 days later, without waiting for the full 15-day period, thereby depriving the taxpayer of the opportunity to contest the PAN and present supporting evidence. Accordingly, the FLD/FAN and the resulting deficiency tax assessment were declared void and without effect, and the assessments were cancelled and set aside. [(Transnational E-Business Solutions, Inc. v. CIR, CTA Case No. 10912,  April 13, 2026; CIR v. Travel Warehouse, Inc., CTA EB No. 3011, (CTA Case No. 10098), April 6, 2026)]

REVENUE ISSUANCES

Revenue Memorandum Circular No. 96-2026

The BIR clarifies the qualification of Export-Oriented Enterprises (EOE) to VAT Refund during the transitory period for securing a VAT Zero-Rating Certificate from the Export Marketing Bureau of the Department of Trade and Industry (EMB-DTI).

  • EOE that were passed on VAT on their local purchases and importation during the effectivity of RA 12066 on November 28, 2024 up to issuance of the VAT zero-rating certification by the EMB-DTI, may claim VAT refund for such passed-on VAT, provided that such certification was issued during the transitory period ending December 31, 2025
  • If EOE attains 70% threshold from the preceding year but did not obtain EMB certification (including transitory period), it cannot refund input VAT covering immediately succeeding year; but input VAT may be carried forward to subsequent taxable quarters until utilized
  • If VAT has been reimbursed, credited, adjusted, recovered from suppliers or utilized, it cannot be refunded.

BIR DEADLINES FROM SEPTEMBER 14, 2026 TO SEPTEMBER 20, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
SEPTEMBER 14, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group B. Month of August 2026
SEPTEMBER 15, 2026
REGISTRATION (Online thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Accounts/Invoices and Other Accounting Records. Fiscal Year ending August 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1702–RT/1702-EX/1702-MX– Fiscal Year ending May 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return For Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending May 31, 2026
eFILING & PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld). eFPS Filers under Group A. Month of August 2026
e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld)  – eFPS Filers under Group E, D, C & B. Month of August 2026
SEPTEMBER 16, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers – September 1-15, 2026
SEPTEMBER 20, 2026 eFILING & PAYMENT (Online/Manual) – BIR Form 1600 WP (Remittance Return of Percentage Tax on Winnings and Prizes Withheld by Race Track Operators) – eFPS & Non-eFPS Filers. Month of August 2026
AUGUST 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – Non-eFPS Filers. Fiscal Quarter ending July 31, 2026
SUBMISSION – Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products. Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2551Q (Quarterly Percentage Tax Return). Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider) – Fiscal Quarter ending July 31, 2026
AUGUST 29, 2026 e-FILING & PAYMENT (Online/Manual) – BIR Form 1702Q (Quarterly Income Tax Return For Corporations, Partnerships and Other Non-Individual Taxpayers) and Summary Alphalist of Withholding Taxes (SAWT). For the Quarter ending June 30, 2026
AUGUST 30, 2026
SUBMISSION – Proof of eFiled BIR Form 1702 – RT/EX/MX with Audited Financial Statements (AFS), 1709 (if applicable), and Other Attachments through Electronic Audited Financial Statements (eAFS) or Manually. Fiscal Year ending April 30, 2026
SUBMISSION – Soft Copies of Inventory List and Schedules stored and saved in DVD-R/USB properly labeled together with Notarized Sworn Declaration. Fiscal Year ending July 31, 2026
e-SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – eFPS Filers. Fiscal Quarter ending July 31, 2026
ONLINE REGISTRATION (thru ORUS) – Computerized Books of Accounts and Other Accounting Records. Fiscal Year ending July 31, 2026

Dear Clients, Colleagues and Friends:

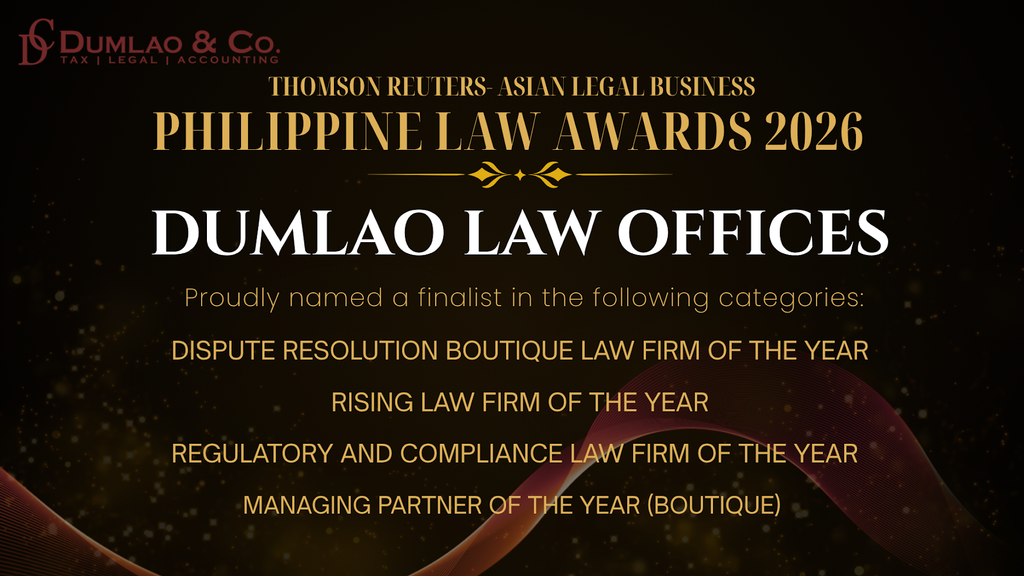
We are thrilled to share that Dumlao Law Offices has been named as a finalist in the 11th Annual ALB Philippine Law Awards 2026, presented by Asian Legal Business.

The firm has been recognized as a finalist in the following categories:

  • Dispute Resolution Boutique Law Firm of the Year
  • Rising Law Firm of the Year
  • Regulatory and Compliance Law Firm of the Year
  • Managing Partner of the Year (Boutique)

This recognition is a meaningful milestone for our firm and reflects our continued commitment to excellence in legal practice and service.

We are grateful for the continued trust and confidence extended to Dumlao Law Offices and remain committed to providing quality and dependable legal services.

Thank you for being part of our journey.

COURT OF TAX APPEALS (CTA) DECISIONS

IN VAT REFUND CLAIMS, WHERE THE CIR FAILS TO ACT WITHIN THE 90-DAY PERIOD, THE CLAIM IS DEEMED DENIED AND MUST BE APPEALED WITHIN 30 DAYS; SEE DISSENTING OPINION. The CTA has jurisdiction over decisions and inaction of the CIR involving VAT refund claims, and the CIR’s failure to act within the prescribed 90-day period constitutes a deemed denial, which must be appealed to the CTA within 30 days from the expiration of such period; applying these rules, the CIR failed to act within the 90-day period, which expired on October 13, 2020, such that the taxpayer had until November 12, 2020 to file its judicial claim, and the subsequent VAT refund notice issued beyond the 90-day period did not revive or extend the appeal period, rendering the Petition for Review filed only on November 20, 2020 late and depriving the CTA of jurisdiction. Dissenting opinion: The TRAIN Law did not eliminate the taxpayer’s right to appeal either the CIR’s inaction or a denial issued after the 90-day processing period. The TRAIN Law deleted the language referring to inaction and shortened the processing period to 90 days; however, CTA Charter continued to expressly grant the CTA jurisdiction over CIR inaction. A taxpayer could still either appeal the CIR’s deemed denial within 30 days after the lapse of the 90-day period or wait for the CIR’s actual decision and appeal within 30 days from receipt, even if the decision was issued after the 90-day period. [Franklin Baker Company of the Philippines v. CIR, CTA EB No. 3025 (CTA Case No. 10407), February 10, 2026]

A TAXPAYER CLAIMING A CWT REFUND MUST PROVE THAT THE INCOME PAYMENTS SUBJECT TO CWT WERE INCLUDED IN ITS GROSS INCOME. The Court generally cannot consider evidence that was not formally offered, and even when this rule is relaxed, the evidence must have been identified through testimony and incorporated into the record; applying this rule, the taxpayer failed to prove that the income payments subjected to the claimed CWTs were included in its gross income because its AITR, AFS, and GL reflected a discrepancy, and it did not adequately reconcile the difference or trace the income payments reported in the SAWT and CWT certificates to the revenues declared in its AITR. Although the taxpayer presented reconciliation tables attributing the discrepancy to accounting adjustments, revenues not subjected to CWT, and timing differences, these were presented for the first time on appeal, were not testified to by its witnesses, were unsupported by specific evidence, and were not evaluated by the Court in Division; hence, they constituted mere allegations that could not establish entitlement to the claimed CWT refund. The Court likewise emphasized that the findings of the Court-commissioned ICPA were not conclusive and could not relieve taxpayer of its burden to independently substantiate its refund claim. [Ford Group Philippines v. Commissioner of Internal Revenue, CTA EB No. 3026 (CTA Case No. 10507), February 4, 2026]

ONLY A FINAL DECISION OR INACTION OF THE CIR OR A DULY AUTHORIZED REPRESENTATIVE IS APPEALABLE TO THE CTA; AN RDO’S LETTER IS NOT AN APPEALABLE DENIAL SINCE HE IS NOT CONSIDERED AS AUTHORIZED REPRESENTATIVE. Only a decision or inaction of the CIR, or of a duly authorized representative acting pursuant to a valid delegation of authority, is appealable to the CTA; although the CIR may delegate the authority to decide refund claims to qualified subordinate officials, such delegation must comply with the applicable rules, which provide that VAT refund claims are processed by the RDO but their approval or denial must be made by the Regional Director or the appropriate authorized official. Applying these rules, the letter issued by RDO and received by the taxpayer was not an appealable decision because an RDO, acting alone, lacked authority to finally deny the refund claim, and the letter itself did not convey a tenor of finality, stating merely that the taxpayer failed to prove its entitlement to the refund and providing the information for its guidance. The actual appealable denial was the subsequent letter signed by Regional Director, categorically denying the VAT refund for lack of legal and factual basis; however, the taxpayer had already filed its Petition for Review before receipt of the authorized denial, making the CTA petition premature and depriving the Court of jurisdiction. [Firmenich (Philippines), Inc. v. Commissioner of Internal Revenue, CTA EB No. 2992 (CTA Case No. 10209), December 15, 2025]

 A FACILITY CONDUCTING BUSINESS IS CONSIDERED AS A BRANCH, WHICH IS REQUIRED TO BE VAT-REGISTERED FOR INPUT VAT REFUND PURPOSES. Every person subject to internal revenue tax must register with the appropriate RDO before commencement of business, and every separate or distinct establishment or facility where sales transactions are conducted must be registered as a branch and subjected to the corresponding annual registration fee; this registration requirement is likewise a prerequisite to being considered a VAT-registered person entitled to claim an input VAT refund. Applying these rules, although the Palawan Facility and Technopoint Facility were denominated as facilities, the taxpayer generated sales of call center services to, thereby making the facilities branches for VAT registration purposes; however, the taxpayer failed to register them as branches and pay the corresponding annual registration fees on or before the sales transactions occurred. Consequently, the taxpayer was not a VAT-registered person during the period covered by the refund claim [Foundever Philippines Corporation (formerly Sitel Philippines Corporation) v. Commissioner of Internal Revenue, CTA EB No. 2942 (CTA Case No. 10200), December 18, 2025]

A TAXPAYER CLAIMING AN EXCISE TAX REFUND MUST SUFFICIENTLY IDENTIFY AND TRACE THE PETROLEUM PRODUCTS SOLD TO TAX-EXEMPT ENTITIES TO THE PRODUCTS ON WHICH THE EXCISE TAX SUBJECT OF THE REFUND CLAIM WAS ACTUALLY IMPOSED AND PAID. The taxpayer bears the burden of substantiating its entitlement by competent evidence establishing a clear nexus between the excise taxes paid and the petroleum products subsequently sold to tax-exempt entities; moreover, the Court is not bound by the findings of the ICPA, and evidence submitted to the ICPA does not constitute evidence formally offered before the Court. Applying these rules, the taxpayer failed to establish that the bunker fuel oil (BFO) and special fuel oil (SFO) sold to tax-exempt entities were the same petroleum products on which it paid excise taxes, as it did not submit the Official Registry Books (ORBs), complete and properly supported fuel-oil inventory records, and all relevant sales invoices; the missing invoices further prevented the Court from tracing the inventory using the first-in, first-out method. The Court also rejected petitioner’s claim that the ORB requirement was introduced later, noting that ORBs had previously been utilized in jurisprudence and tax refund examinations, and held that the taxpayer could not rely on its submission of the ORBs to the ICPA because such submission was not equivalent to a formal offer of evidence before the Court. [SL Harbor Bulk Terminal Corporation v. Commissioner of Internal Revenue, CTA EB No. 2982 (CTA Case No. 10320), December 23, 2025 and CTA EB No. 2981 (CTA Case No. 10440), February 2, 2026]

LACK OF DESCRIPTION IN INVOICE WARRANTS THE DISALLOWANCE OF INPUT VAT REFUND; CROSS-REFERENCING TO BILLING STATEMENTS IS NOT SUFFICIENT. Admissibility of evidence must be distinguished from its probative value, and a taxpayer seeking an input VAT refund bears the burden of proving its legal and factual entitlement through sufficient, competent, complete, and legible evidence; moreover, strict compliance with VAT substantiation and invoicing requirements is necessary because the VAT invoice or official receipt serves as the primary evidence of creditable input VAT and ensures an accurate audit trail. Applying these rules, although the taxpayer’s physical copies of the official receipts were admitted in evidence, the scanned copies submitted for the Court’s appreciation were blurred and unreadable, preventing the Court from properly examining and verifying the input VAT credits claimed; hence, their admission did not establish their probative value. The taxpayer likewise failed to comply with the requirement that VAT official receipts for services indicate the nature of the service, and its admission that the subject ORs lacked such description could not be cured by identifying the suppliers or cross-referencing billing statements and invoices, since other documents cannot substitute for the required VAT receipts themselves. The Court further held that the principle of VAT neutrality cannot override the NIRC’s mandatory invoicing and documentary requirements, which are substantive requirements rather than mere technicalities. [Commissioner of Internal Revenue v. New York Bay Philippines, Inc., CTA EB Nos. 2915 & 2916 (CTA Case No. 10417), December 2, 2025]

Defective verification is not fatal and may be corrected or dispensed with when warranted by the circumstances, while a defect in the certification against forum shopping is generally not curable by subsequent submission unless there is substantial compliance or special or compelling circumstances; applying these rules, the Court found substantial compliance because the petitioner expressly explained that it could not initially submit the authenticated documents due to distance and time constraints and subsequently filed the Apostilled Verification and Certification of Non-Forum Shopping and Director’s Certificate as soon as these were secured, thus satisfying the mandatory purpose of the requirements without unduly rigid application that would defeat the orderly administration of justice [Commissioner of Internal Revenue v. Grid Solutions (US) LLC., CTA EB No. 2814 (CTA Case No. 10146)]

DOE REGISTRATION IS REQUIRED FOR ZERO-VAT SALE ON SALE OF ELECTRICITY GENERATED FROM RENEWABLE ENERGY SOURCES. Sales of electricity generated from renewable energy sources may qualify for 0% VAT, but the incentive is subject to the statutory and regulatory conditions imposed on Renewable Energy Developers, including registration with the DOE, and the taxpayer must still prove through competent evidence that it actually made zero-rated sales; applying these rules, the Court held that the taxpayer’s reliance on the NIRC alone was misplaced because R.A. No. 9513 is a later and special law specifically governing fiscal incentives for RE Developers, and its express repealing clause and IRR require an RE Developer to secure DOE registration to qualify for the incentives, including VAT zero-rating. Although the taxpayer submitted a BOI Certificate of Registration, it failed to timely present the required DOE Certificate of Registration, which it attached only to its Motion for Reconsideration; evidence that could have been presented during trial but was belatedly submitted without justification constitutes forgotten evidence and cannot be admitted on appeal. More importantly, even assuming the taxpayer could qualify for the incentive, it still failed to prove the actual existence of zero-rated sales. Its Quarterly VAT Return reported no zero-rated sales; its AFS and AITR showed only interest income and no operating revenue from electricity generation; and taxpayer itself admitted that it had no recorded sale of electricity because it only began generating electricity in the subsequent year. Its subsequent reliance on its later AITR was likewise insufficient because the return merely reflected aggregate revenue without identifying the nature of the transactions or establishing that they were zero-rated sales. The official receipts submitted for the first time before the Court En Banc were also inadmissible forgotten evidence because they had not been formally offered during the proceedings before the Court in Division and no justification was given for their late submission. [YH Green Energy Incorporated v. Commissioner of Internal Revenue, CTA EB No. 2995 (CTA Case No. 9784), February 10, 2026]

NON-RESIDENT FOREIGN CORPORATION’S SALE OF SHARES IN A DOMESTIC CORPORATION IS EXEMPT FROM CGT IF DOMESTIC CORPORATION’S PROPERTY AND EQUIPEMENT DOES NOT EXCEED THE 50% THRESHOLD. A claim for refund of erroneously or illegally collected taxes must be supported by timely administrative and judicial claims, and the claimant must establish its right to the refund, including the specific legal basis for any claimed tax exemption; applying these rules, the taxpayer established its entitlement to a refund of the CGT paid on the sale of domestic company shares because RP-US Tax Treaty grants the exclusive taxing right over gains from the sale of shares to the seller’s country of residence, unless the shares represent an interest in a corporation whose assets principally consist of Philippine real property, and the domestic corporation’s financial statements showed that its Philippine property and equipment well below the 50% threshold; the Philippines had no taxing right over the capital gain, and the statutory taxpayer/seller had standing to claim the refund. [Commissioner of Internal Revenue v. Grid Solutions (US) LLC., CTA EB No. 2814 (CTA Case No. 10146)]

REVENUE ISSUANCES

BIR RMO No. 22-2026, August 24, 2026

The BIR prescribes the consolidated and revised policies, guidelines and procedures for the BIR audit program

  • Taxpayer (TP) is subject to only 1 Letter of Authority (eLA) for a given year covering all applicable internal revenue tax type
  • Audit shall be system-assisted, risk-based. TP identity remained concealed during the selection and assignment stage to ensure impartiality and prevent undue influence.
  • Mandatory cases:
    • Suspected fraud such as declaring 30% less income or 30% more expenses;
    • TP identified through specific industry knowledge, data from third parties, or publicly accessible information;
    • TP previously under a Mission Order where preliminary findings show a 30% or greater understatement of sales;
    • ONETT where findings resulted in tax deficiency or real property transactions with findings in the eCAR system (should be limited only to a specific ONETT and conducted by the investigating office which issued the eCAR and which has proper jurisdiction; if eCAR is used by the office which has no jurisdiction, referral to the appropriate office to be made and corresponding eLA is used)
    • Using tax exemptions or special incentives;
    • Non-compliance with tax obligations arising from Spontaneous Exchange of Information (EOI);
    • ТP requesting for tax clearance whose gross sales for the immediately preceding year exceed Php3M or gross assets is more than Php8M, due to:
      • Death of the taxpayer; or 
      • Taxpayers retiring from business
      • Taxpayers undergoing merger/ consolidation/  split-up/ spin-off and other types of corporate reorganizations
    • TP who failed to respond to Third Party Information (TPI) request
    • TP with validated discrepancies or material inconsistencies identified through the system.
    • TP with refund claims
  • Mandatory cases do not require CIR’s approval. Approving authority is regional director or ACI R for LTS; Effect of misclassification – administrative sanction
  • Taxpayer enjoying tax exemptions or incentives is not automatically subjected to audit, and subject to risk-based evaluation
  • Failure to respond to request for confirmation of TPI data matching within the period – TP shall be subject to mandatory audit
  • For refunds of income tax under Section 58 (e) and 76(C), LOA and TVN will be issued
  • Service of LOA requires First and Second/Final notice if taxpayer fails to comply within 10 days
  • Place of examination – place of business or BIR office; if documents are voluminous or transport or examination at the BIR would be impractical, burdensome or disruptive to business operation, TP has option on the venue and manner of examination; TP consent on audit venue to be accomplished
    • If at BIR office – taxpayer may opt to physically submit the BIR records
    • If principal place of business – TP to coordinate with RO; TP shall provide suitable area
      • Photocopies may be accepted; TP or authorized representative must certify that the documents are true and faithful reproduction of the original. BIR may require presentation of original for solely for verification. 
      • SDT – no option for venue; venue is BIR office specified in the SDT
  • Minutes of Meeting after NOD is issued are required
  • Prescriptive period suspended – when issuance of SDT or EOI BIR is requested; effectivity date: upon date of receipt of request by concerned office; to resume when BIR officer receives the requested information
  • Termination Letter – to be prepared for all paid cases or cases with no findings or discrepancies; issued by Regional office; LTS, HREA-EAS; 
  • Priority cases (electronically selected based on risk-based criteria; uses the data from filed tax returns and other information in the BIR system)
    • Drastic decrease in reported sales or VAT payments
    • Large increases in sales that are zero-rated or exempt from tax
    • TP with Discrepancy Notices
    • Differences between current VAT filings and what was carried over from previous months
    • Claiming input VAT that cover more than 75% of the total output tax
    • Paying income tax that is less than 2% of the gross sales/revenues
    • TP filing percentage tax returns exceededing the VAT threshold
    • Reporting a net loss despite having substantial sales
    • Operating for more than five years without ever being audited
    • Taxpayers with increase in assets of more than 50% from the previous year but with reported net loss
    • Claims for damages from natural disasters or for old inventory
    • Getting almost all income from a parent company or affiliate
    • Taxpayers claiming write-off of input tax as allowable deduction in its annual income tax
    • Sharing expenses between different branches or companies in a group. 
  • Recommendations by the heads of investigating office must be supported by written justification. IT shall include the audit selection criteria; subject to approval of the CIR upon recommendation of the DCIR-OG, DCIR-SRG before the eLA is issued
  • Effectivity: immediately (august 24, 2026)

BIR DEADLINES FROM AUGUST 24, 2026 TO AUGUST 30, 2026. A gentle reminder on the following deadlines, as may be applicable.

DATE FILING/SUBMISSION
AUGUST 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – Non-eFPS Filers. Fiscal Quarter ending July 31, 2026
SUBMISSION – Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products. Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2551Q (Quarterly Percentage Tax Return). Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider) – Fiscal Quarter ending July 31, 2026
AUGUST 29, 2026 e-FILING & PAYMENT (Online/Manual) – BIR Form 1702Q (Quarterly Income Tax Return For Corporations, Partnerships and Other Non-Individual Taxpayers) and Summary Alphalist of Withholding Taxes (SAWT). For the Quarter ending June 30, 2026
AUGUST 30, 2026
SUBMISSION – Proof of eFiled BIR Form 1702 – RT/EX/MX with Audited Financial Statements (AFS), 1709 (if applicable), and Other Attachments through Electronic Audited Financial Statements (eAFS) or Manually. Fiscal Year ending April 30, 2026
SUBMISSION – Soft Copies of Inventory List and Schedules stored and saved in DVD-R/USB properly labeled together with Notarized Sworn Declaration. Fiscal Year ending July 31, 2026
e-SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – eFPS Filers. Fiscal Quarter ending July 31, 2026
ONLINE REGISTRATION (thru ORUS) – Computerized Books of Accounts and Other Accounting Records. Fiscal Year ending July 31, 2026

COURT OF TAX APPEALS (CTA) DECISIONS

TAXPAYER CANNOT CLAIM REFUND FOR VAT ERRONEOUSLY PASSED ON BY SUPPLIERS ON ZERO-RATED PURCHASES; THE PROPER REMEDY IS REIMBURSEMENT FROM THE SUPPLIERS. A taxpayer that is entitled to zero-rated purchases is not the proper party to claim a refund of VAT erroneously passed on by its suppliers; the buyer’s remedy is to seek reimbursement from the supplier. Applying these principles, even assuming that taxpayer’s purchases from renewable energy suppliers were zero-rated, the VAT allegedly shifted to the taxpayer should not have been charged in the first place; the taxpayer therefore cannot recover the erroneously passed-on VAT through a Section 112 refund claim merely because it bore the economic burden. The Supreme Court held that the proper recourse of a buyer mistakenly charged VAT on zero-rated purchases is against its supplier and the same principle extends to  renewable energy developers. Thus, the Court held that the taxpayer was not the proper party to claim a refund of the input VAT erroneously passed on by its suppliers, without prejudice to its right to seek reimbursement from them. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

THE INCENTIVES GRANTED TO RE DEVELOPERS EXPRESSLY COVER BOTH POWER AND NON-POWER APPLICATIONS; INPUT VAT RELATED TO NON-POWER APPLICATION CANNOT BE VALIDLY SUBJECT OF INPUT VAT REFUND. The law (third paragraph) provides zero-rated VAT on local purchases of goods, properties, and services needed for the whole process of exploring and developing renewable energy sources up to their conversion into power. The Court held that the third paragraph does not distinguish between power and non-power applications: the phrase “whole process of exploring and developing renewable energy sources” sufficiently covers non-power applications, while the succeeding phrase “up to its conversion into power” merely extends the coverage to power applications and does not exclude non-power RE developers. Since petitioner was accredited by the DOE as a biomass RE developer for non-power application, specifically a biofuel manufacturer producing biodiesel/Coconut Methyl Ester, its purchases falling within the statutory coverage were entitled to VAT zero-rating. Accordingly, the input VAT pertaining to purchases entitled to zero-rating should be disallowed from the taxpayer’s VAT refund claim. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

INPUT VAT ON CAPITAL GOODS EXCEEDING PHP MILLION MUST BE PROPERLY SUBSTANTIATED BY INVOICE AND AMORTIZATION SCHEDULE; PRIOR YEAR INPUT VAT RETURN IS NOT SUFFICIENT. Input VAT on capital goods with an aggregate acquisition cost exceeding Php1 million may be spread over 60 months or the capital goods’ estimated useful life, whichever is shorter, but the taxpayer must properly substantiate the capital-goods purchases and the corresponding amortization; supporting documents are necessary to establish the nature of the purchases as capital goods and to verify the proper amortization of the input VAT. Applying this rule, although the taxpayer claimed that the deferred input VAT carried over from CY 2017 was supported by its Q4 CY 2017 VAT return and that it represented the remaining amortized input tax, the taxpayer failed to present the underlying documents establishing the capital-goods purchases and the correctness of the amortization computation; even its independent CPA reported that the supporting documents for the capital-goods input taxes deferred and amortized in CY 2018 had not been provided. Thus, the mere appearance of the amount in the prior-period VAT return was insufficient substantiation, and the Court properly disallowed the deferred input VAT from the refund claim. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

INPUT VAT MAY BE SUPPORTED BY PHOTOCOPIES. A duplicate, including a photocopy, is admissible to the same extent as an original unless a genuine question is raised regarding the authenticity of the original or admission of the duplicate would be unjust or inequitable. The Supreme Court recognized that a photocopy falls within the definition of a duplicate and is therefore admissible as an original. Applying this rule, the Court held that the input VAT supported by photocopies of sales invoices and official receipts should not have been disallowed, since the BIR did not question the authenticity of the originals nor establish that admitting the photocopies would be unjust or inequitable. Accordingly, the disallowance was reversed and the amount was added back to the taxpayer’s valid input VAT for CY 2018. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

A VAT-REGISTERED TAXPAYER CLAIMING INPUT VAT ATTRIBUTABLE TO ZERO-RATED SALES HAS TWO ALTERNATIVE OPTIONS: (1) CHARGE THE INPUT VAT AGAINST OUTPUT VAT FROM REGULAR 12% VATABLE SALES AND CLAIM A REFUND ONLY OF ANY RESULTING EXCESS INPUT VAT, OR (2) CLAIM THE ENTIRE INPUT VAT ATTRIBUTABLE TO ZERO-RATED SALES FOR REFUND OR TAX CREDIT. The Court cannot impose the first method when the taxpayer chose the second. In this case, however, the Court found that the taxpayer original Petition for Review and its own computation showed that it chose the first option, as it first allocated input VAT to VATable sales and determined whether such input VAT exceeded its declared output VAT before arriving at the refundable amount. Thus, the Court in Division properly charged the substantiated input VAT against petitioner’s output VAT. The Court En Banc determined valid input VAT, of which an amount was allocated to VATable sales, leaving  output VAT still due; the remaining input VAT allocated to zero-rated sales was likewise insufficient to produce any excess input VAT refundable to petitioner. Accordingly, despite the adjustment recognizing the photocopied supporting documents, the taxpayer still had no excess input VAT for refund and failed to satisfy the requisites under Section 112. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

INVOICE ISSUED PRIOR TO DATE OF ATP CANNOT VALIDLY SUBSTANTIATE INPUT VAT; ANTE-DATING IS NOT ALLOWED. Taxpayers are required to issue a duly registered invoice at the point of each sale, and the supporting invoice must be covered by a valid and subsisting Authority to Print (ATP) applicable to the date of the transaction. Applying this rule, the Court rejected the taxpayer’s argument that the subject document remained valid merely because they were eventually registered with the BIR under an ATP dated earlier than ATP date, and that the NIRC does not expressly prohibit antedating. The Court clarified that antedating itself was not the decisive issue; rather, the receipts (now invoice) were disallowed because they were not duly registered receipts at the point of each sale, constituting non-compliance with the invoicing and substantiation requirements. The official receipts (now invoice) covering transactions dated earlier should have been supported by an ATP valid and subsisting on those dates, but the receipts (now invoice) bore serial numbers outside the range authorized by  a later ATP. Consequently, the receipts could not substantiate the claimed input VAT. [Mastercard Transaction Services (Philippines) Inc. v. Commissioner of Internal Revenue, CTA EB Nos. 3062 & 3066 (CTA Case No. 10628), March 18, 2026]

AN EXPORT SALE IS SUBJECT TO ZERO PERCENT VAT ONLY WHEN THE SALE IS MADE BY A VAT-REGISTERED PERSON, THERE IS AN ACTUAL SALE AND SHIPMENT OF GOODS FROM THE PHILIPPINES TO A FOREIGN COUNTRY, AND THE SALE IS PAID FOR IN ACCEPTABLE FOREIGN CURRENCY AND ACCOUNTED FOR IN ACCORDANCE WITH BSP RULES. The taxpayer bears the burden of strictly proving both the factual basis of its zero-rated sales and compliance with the statutory and documentary requirements, since a VAT refund is in the nature of a tax exemption; moreover, a CTA case is litigated de novo, and the judicial claim must be established by the evidence formally presented before the CTA. Applying these rules, the taxpayer failed to prove that its reported sales actually qualified for VAT zero-rating. The Court found that some of reported sales had no valid VAT zero-rated sales invoices or lacked corresponding bills of lading and/or export declarations; or bills of lading that were inadmissible, missing from the records, did not correspond with the exhibits offered, or were illegible. The taxpayer likewise failed to establish the third requirement because its inward remittance certifications and bank transaction reports did not correspond with the amounts stated in the sales invoices; its explanations that the discrepancies resulted from advance payments, prior-period receivables, or the practice of splitting or consolidating invoice amounts were merely bare assertions unsupported by sales invoices, official receipts, bank credit advices, or reconciliation schedules. Because the taxpayer failed to first establish the existence of valid zero-rated sales to which the claimed unutilized input VAT could be attributed, the Court found it unnecessary to examine the remaining requisites for the refund. [Agri Exim Global Philippines, Inc. v. CIR, CTA EB No.3075, CTA Case No. 10621, March 24, 2026]

WHERE THE TAXPAYER IMPORTED JET A-1 FUEL AND SUBSEQUENTLY SOLD IT TO QUALIFIED INTERNATIONAL CARRIERS FOR USE OUTSIDE THE PHILIPPINES, THE FUEL BECAME EXEMPT. Under the applicable provisions on excise tax and tax exemption of petroleum products sold to international carriers, excise tax is an indirect tax imposed on the article itself, with the statutory liability attaching to the importer or manufacturer, while the economic burden may be passed on to the buyer; hence, the buyer is not the statutory taxpayer entitled to claim the exemption. Applying this rule, the Court held that the international carriers that purchased the Jet A-1 fuel merely bore the economic burden of the excise tax, while the taxpayer, as the importer and statutory taxpayer, was the proper party to claim the exemption and refund. Although the excise tax became due upon importation, the subsequent sale of the Jet A-1 fuel to qualified international carriers for use and consumption outside the Philippines rendered the petroleum products exempt, resulting in the excise taxes previously paid being erroneously or illegally collected and therefore refundable. The taxpayer sufficiently proved through competent evidence that it imported the Jet A-1 fuel and subsequently sold it to international carriers; thus, the CTA in Division correctly granted the refund. [(CIR v. Pilipinas Shell Petroleum Corporation, CTA EB No. 3027, CTA Case NO. 10352, March 11, 2026)]

UNDER THE 2-YEAR PRESCRIPTIVE PERIOD FOR TAX REFUNDS, THE PERIOD RUNS FROM PAYMENT OF THE ERRONEOUSLY OR ILLEGALLY COLLECTED TAX; THUS, BECAUSE THE TAXPAYER IMPROPERLY RECOGNIZED DEFERRED SUBSCRIPTION REVENUE IN 2017 AND PAID THE CORRESPONDING INCOME TAX IN APRIL 2018, ITS REFUND CLAIMS FILED ONLY IN APRIL AND MAY 2021 WERE PRESCRIBED; WITH DISSENTING OPINION. Both the administrative and judicial claims for refund of erroneously or illegally collected taxes must be filed within  2 years from the date of payment of the tax, with timely filing being mandatory and jurisdictional; applying these provisions, the Court En Banc held that the erroneous payment arose not in CY 2018 but in CY 2017, when the taxpayer improperly included Php200M of deferred subscription revenue, collected but not yet earned, in its 2017 taxable income and paid the corresponding income tax in April 2018. Since the taxpayer uses the accrual method, income should be recognized when earned, and the deferred subscription revenue was properly earned only in 2018; thus, the two-year period commenced in April 2018 and, considering the applicable COVID-19 extensions, taxpayer had only until June 2020 to file its claims. However, the taxpayer filed its administrative claim only in April 2021 and its judicial claim in May 2021, both beyond the prescriptive period, depriving the CTA of jurisdiction and requiring dismissal of the refund case. Dissenting Opinion: The two-year prescriptive period should be reckoned from its 2018 income tax payment, not from 2017 when the taxpayer reported the cash deposits or advances as income when received in 2017 in compliance with RMC No. 16-2013; the Court should respect the accounting method adopted by the taxpayer [SAS Institute (Philippines) Inc. v. Commissioner of Internal Revenue & Commissioner of Internal Revenue v. SAS Institute (Philippines) Inc., CTA EB Nos. 2991 & 2994 (CTA Case No. 10537), March 4, 2026.]

REVENUE ISSUANCES

RMC No. 95-2026, August 14, 2026

The BIR provides extension of the deadlines for the filing of tax returns of corresponding taxes due thereon, including submission of required documents for taxpayers due to unavailability of eBIR forms offline package

Covered Return Deadlines on August 10 to 16, 2026
Extended Period August 18, 2026
Excluded from the Coverage Taxpayers mandated to use eFPS

BIR DEADLINES. A gentle reminder on the following deadlines, as may be applicable:

BIR DEADLINES FROM AUGUST 10, 2026 TO AUGUST 16, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
AUGUST 18, 2026
SUBMISSION – List of Buyers of Sugar Together with a Copy of Certificate of Advance Payment of VAT made by each buyer appearing in the List by a Sugar Cooperative. Month of July 2026
SUBMISSION – Information Return on Releases of Refined Sugar by the Proprietor or Operator of a Sugar Refinery or Mill. Month of July 2026
e-SUBMISSION – Monthly e-Sales Report for All Taxpayers using CRM/POS and/or Other Similar Business Machines whose last digit of 9-digit TIN is Odd Number. Month of July 2026
e-FILING & PAYMENT/REMITTANCE (Online/Manual) – BIR Form 2200-M Excise Tax Return for the Amount of Excise Taxes Collected from Payment Made to Sellers of Metallic Minerals. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2200-C (Excise Tax Return for Cosmetic Procedures) with Monthly Summary of Cosmetic Procedures Performed. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 0620 (Monthly Remittance Form of Tax Withheld on the Amount Withdrawn from the Decedent’s Deposit Account) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or 1600-PT (Other Percentage Taxes Withheld) and Monthly Alphalist of Payees (MAP) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1606 – (Withholding Tax Remittance Return for Onerous Transfer of Real Property Other Than Capital Asset Including Taxable and Exempt). Month of July 2026
e-FILING & e-PAYMENT/REMITTANCE – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or BIR Form 1600-PT (Other Percentage Taxes Withheld) and 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – National Government Agencies (NGAs). Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E. Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group D. Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group C.  Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group B. Month of July 2026
AUGUST 18, 2026
REGISTRATION (Online Thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Accounts/Invoices and Other Accounting Records. Fiscal Year ending July 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1702 – RT/EX/MX. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return For Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1701Q (Quarterly Income Tax Return For Individuals, Estates & Trusts) and Summary Alphalist of Withholding Taxes (SAWT) – eFPS & Non-eFPS Filers. For the Quarter ending June 30, 2026
e-FILING & e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group A. Month of July 2026
e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded)  and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E, D ,C & B.  Month of July 2026
AUGUST 18, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers. August 1-15, 2026

COURT OF TAX APPEALS DECISIONS

REASONS FOR DISALLOWANCE OF CWT. A taxpayer is entitled to a refund of excess Creditable Withholding Taxes (CWT) if, among others, the income payments subject of the CWTs are declared as part of the taxpayer’s gross income in its annual ITR and the fact of withholding is established through duly issued BIR Form No. 2307, without requiring proof of the withholding agent’s actual remittance or the submission of a SAWT. Here, while the taxpayer substantiated most of its claimed CWTs through valid BIR Forms 2307, the Court disallowed some CWT due to defective withholding certificates and further denied CWT corresponding to income payments that were not sufficiently proven to have been reported as part of gross income. Reasons for the disallowance: variance between sales invoice and schedule; unreadable invoice; cancelled sales invoice, untraced payment file; incorrect TIN of the taxpayer; the TIN of the Head Office was indicated but the address is the Branch Office; Incomplete address of the taxpayer; BIR Forms 2307 were dated outside of the claimed period; variance in the amount of CWT per BIR Form 2307 versus per books; CWT not within the period of claim; no signature of the payor-issuer/authorized representative; with alteration on taxpayer’s name without counter signature, alteration on the taxpayer’s TIN without counter signature; income payments not traced to the GL/supporting documents [Watsons Personal Care Stores (Philippines), Inc. v. CIR, CTA Case No. 10883, November 26, 2025; Watsons Personal Care Stores (Philippines), Inc., CTA Case No. 10504, February 16, 2026; see also Sonic Sales & Distribution, Inc. v. CIR, CTA Case No. 10888, February 18, 2026]

OSG’S RECEIPT OF THE RESOLUTION, NOT BIR’S, IS THE RECKONING PERIOD TO APPEAL TO THE CTA EN BANC. An aggrieved party may appeal a CTA Division decision or resolution on a motion for reconsideration or new trial to the Court En Banc within 15 days from receipt thereof, while the Administrative Code vests in the Office of the Solicitor General (OSG) the authority and duty to represent the government in appellate proceedings, with deputized government lawyers remaining under its supervision and control. Service upon the deputized counsel or BIR Legal Division is insufficient; the OSG, as principal counsel, must receive the decision and has the authority to determine whether an appeal should be taken. In this case, although the BIR received the assailed Resolution in December, the OSG received it only in January the following year, while the BIR filed the Petition for Review in December, before the OSG had even received the Resolution. There was also no evidence that the BIR had been duly authorized by the OSG to file the appeal. Thus, the petition lacked the requisite OSG authority, and the 15-day appeal period could not be reckoned from the BIR’s receipt of the Resolution. Consequently, the appeal was not properly perfected, causing the assailed Resolution to attain finality (CIR v. MSCI Hongkong Limited, CTA EB No. 3047, CTA Case No. 10474, February 19, 2026)

A DUPLICATE COPY, INCLUDING A PHOTOCOPY, OF A DOCUMENT IS ADMISSIBLE TO THE SAME EXTENT AS AN ORIGINAL UNLESS (1) A GENUINE QUESTION IS RAISED AS TO THE AUTHENTICITY OF THE ORIGINAL, OR (2) IT WOULD BE UNJUST OR INEQUITABLE TO ADMIT THE DUPLICATE IN LIEU OF THE ORIGINAL; DISSENTING OPINION Consistent with Lastimosa Case, a photocopy of a paper-based document qualifies as a duplicate, abandoning the former distinction between electronic and paper-based documents. Applying this rule, the Court En Banc held that certain exhibits, which the Court in Division had excluded solely because the taxpayer failed to present the originals for comparison, should be admitted because the BIR did not question their authenticity and there was no showing that admitting the photocopies would be unjust or inequitable. Although the taxpayer failed to timely seek reconsideration of the earlier exclusion, the Court relaxed the procedural rules in the interest of substantial justice, consistent with the principle that procedural rules are meant to facilitate, rather than defeat, the just resolution of cases. Accordingly, the Court admitted the photocopied exhibits as duplicates under the amended Rules on Evidence. Dissenting Opinion: original documents should have been presented under the CTA rules; party should sufficiently explain the unavailability of the originals; taxpayer did not seek reconsideration of the CTA in Division’s resolution excluding the documentary exhibits; there was no proper tender of excluded evidence; strict application of law under tax refund cases [Schaeffler Philippines Inc. v. Commissioner of Internal Revenue, CTA EB No. 2947 (CTA Case No. 10358), February 20, 2026]

THE ABSENCE OF A SEPARATELY PROMINENT IMPRINT OF “ZERO-RATED SALE” DID NOT AUTOMATICALLY NEGATE THE ZERO-RATED CHARACTER OF THE TRANSACTIONS. A VAT invoice must prominently indicate “zero-rated sale,” while invoices covering mixed transactions must clearly show the breakdown of taxable, exempt, and zero-rated components; however, substantial compliance with these invoicing requirements may suffice when the invoice itself clearly identifies the amount as pertaining to zero-rated sales. In this case, although the Court in Division denied the taxpayer’s refund claim because the phrase “zero-rated sale” was not separately and prominently imprinted on the invoice/OR, the Court En Banc held that the invoices contained a detailed breakdown expressly identifying the sales amount under “Zero Rated Sales,” which sufficiently disclosed both the nature and monetary value of the transactions. The Court found that this presentation substantially complied with the invoicing requirement because there could be no other reasonable conclusion than that the stated amount pertained to zero-rated sales, and the clients’ PEZA registrations further established that the sales were indeed subject to zero percent VAT [Schaeffler Philippines Inc. v. Commissioner of Internal Revenue, CTA EB No. 2947 (CTA Case No. 10358), February 20, 2026; Commissioner of Internal Revenue v. MSCI Hong Kong Limited, CTA EB No. 2939 (CTA Case No. 9884), November 9, 2025]

REVENUE ISSUANCES

RMC No. 89-2026, August 10, 2026

The BIR provides extension of the deadlines for the filing of tax returns and payment of corresponding taxes due thereon, including submission of required documents for taxpayers within the jurisdiction of Revenue District Offices of the BIR that were affected by the continued heavy rainfall brought about by southwest monsoon.

Covered Return Deadlines on August 10 to 17, 2026
Extended Period August 17, 2026
Covered Areas
  • Metro Manila
  • Ilocos Sur
  • Provinces of La Union and Pangasinan
  • Provinces of Abra, Apayao, Benguet, Ifugao, Kalinga, Mountan Province
  • Provinces of Bataan, Bulacan, Pampanga, Tarlac, Zambales
  • Provinces of Cavite, Batangas, Rizal and Mindoro
Further extension If extended deadline falls on a holiday, or non-working day, submission and/or filing shall be made on the next working day

BIR DEADLINES. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
AUGUST 17, 2026
SUBMISSION – List of Buyers of Sugar Together with a Copy of Certificate of Advance Payment of VAT made by each buyer appearing in the List by a Sugar Cooperative. Month of July 2026
SUBMISSION – Information Return on Releases of Refined Sugar by the Proprietor or Operator of a Sugar Refinery or Mill. Month of July 2026
e-SUBMISSION – Monthly e-Sales Report for All Taxpayers using CRM/POS and/or Other Similar Business Machines whose last digit of 9-digit TIN is Odd Number. Month of July 2026
e-FILING & PAYMENT/REMITTANCE (Online/Manual) – BIR Form 2200-M Excise Tax Return for the Amount of Excise Taxes Collected from Payment Made to Sellers of Metallic Minerals. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2200-C (Excise Tax Return for Cosmetic Procedures) with Monthly Summary of Cosmetic Procedures Performed. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 0620 (Monthly Remittance Form of Tax Withheld on the Amount Withdrawn from the Decedent’s Deposit Account) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or 1600-PT (Other Percentage Taxes Withheld) and Monthly Alphalist of Payees (MAP) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1606 – (Withholding Tax Remittance Return for Onerous Transfer of Real Property Other Than Capital Asset Including Taxable and Exempt). Month of July 2026
e-FILING & e-PAYMENT/REMITTANCE – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or BIR Form 1600-PT (Other Percentage Taxes Withheld) and 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – National Government Agencies (NGAs). Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E. Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group D. Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group C.  Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group B. Month of July 2026
AUGUST 17, 2026
REGISTRATION (Online Thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Accounts/Invoices and Other Accounting Records. Fiscal Year ending July 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1702 – RT/EX/MX. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return For Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1701Q (Quarterly Income Tax Return For Individuals, Estates & Trusts) and Summary Alphalist of Withholding Taxes (SAWT) – eFPS & Non-eFPS Filers. For the Quarter ending June 30, 2026
e-FILING & e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group A. Month of July 2026
e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded)  and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E, D ,C & B.  Month of July 2026
AUGUST 17, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers. August 1-15, 2026

COURT OF TAX APPEALS DECISIONS

EXEMPTION FROM RPT INVOLVES MIXED QUESTIONS OF LAW AND FACT; DISPUTE REQUIRES PAYMENT UNDER PROTEST. The proper procedure for contesting a real property tax (RPT) assessment depends on the nature of the issues raised. Where the dispute involves the correctness or reasonableness of the assessment, including claims of tax exemption that require factual determination, the taxpayer must first comply with the following administrative remedies: pay the assessed tax under protest, file a protest with the local treasurer, and, if denied, appeal successively to the Local Board of Assessment Appeals (LBAA), the Central Board of Assessment Appeals (CBAA), and finally the CTA En Banc. Direct recourse to the courts is allowed only where the assessment is illegal and the issues raised are purely legal, without requiring the evaluation of evidence. Thus,  the Court found that the taxpayer’s challenge – asserting that its electrical poles and distribution transformers were exempt from RPT because they were not taxable real property and were not exclusively used by the taxpayer – involved mixed questions of law and fact requiring factual evaluation by the LBAA. Despite receiving the notice of assessment and subsequent collection notices, the taxpayer neither paid the assessment under protest nor pursued the mandatory administrative remedies before the LBAA and CBAA. Instead, it directly filed an action before the Regional Trial Court, rendering the assessment final and executory for failure to exhaust administrative remedies. Accordingly, the CTA En Banc denied the petition and affirmed the CTA Division’s ruling. [Manila Electric Company (MECO) v. Municipality of Cordova, CTA EB No. 2957 (CTA AC No. 258), February 2, 2026]

WHILE REAL PROPERTY OWNED BY THE GOVERNMENT IS EXEMPT FROM RPT, THE CONCESSIONAIRE/OPERATOR IS LIABLE FOR RPT UNDER THE BENEFICIAL USE DOCTRINE BECAUSE IT HAD POSSESSION, CONTROL, AND EXCLUSIVE ECONOMIC BENEFIT FROM OPERATING THE TOLLWAY, AND NO LAW EXPRESSLY GRANTED IT A TAX EXEMPTION; TAX DECLARATION SHOULD BE ISSUED UNDER THE NAME OF THE OPERATOR. While real property owned by the Republic of the Philippines is generally exempt from RPT, the exemption does not apply when the beneficial use of the property has been granted, for consideration or otherwise, to a taxable person. The “beneficial use principle” imposes RPT liability on the taxable entity that actually possesses, controls, and derives economic benefit from the government property, regardless of legal ownership. Applying these principles, the Court held that the taxpayer, as the operator of the STAR Tollway under the Toll Concession Agreement (TCA) and Operations and Maintenance Agreement (OMA), had beneficial use of the subject property because it exercised possession and control over the tollway, collected and owned the toll revenues, and operated the facility for its own revenue-generating business. The Court rejected taxpayer’s argument that the public enjoyed the beneficial use, explaining that only paying toll road users could access the facility and that the taxpayer could deny entry to non-paying motorists, demonstrating its exclusive control and economic benefit. The Court further ruled that the government’s supervisory powers through the Toll Regulatory Board did not negate the taxpayer’s beneficial use, as such oversight merely ensured compliance with the concession agreements. Moreover, the taxpayer failed to identify any law granting it exemption from RPT, and the TCA and OMA expressly obligated the concessionaire and operator to pay all taxes unless specifically exempted by law, reinforcing the rule that tax exemptions must be clearly and expressly granted. Consequently, the City Assessor correctly issued the tax declaration in the taxpayer’s name, which requires government-owned property subject to beneficial use by a taxable person to be assessed in the name of the possessor or grantee. Accordingly, the Court sustained the RPT assessment and denied the petition [South Luzon Tollway Corporation v. City Assessor of Lipa, et al., CTA EB No. 2943 (CBAA Case No. L-145-2020), February 4, 2026]

AN INDEPENDENT POWER PRODUCER UNDER A BOT CONTRACT WITH A GOCC THAT HAD ALREADY PAID VALID RPT WAS ENTITLED TO A REFUND OF THE EXCESS RPT RESULTING FROM THE STATUTORY REDUCTION; NO SEPARATE WRITTEN REFUND CLAIM WAS REQUIRED. A taxpayer may file a written claim for refund or credit of RPT and interests only when an assessment is found to be illegal or erroneous and the tax is thereafter reduced or adjusted. In this case, the Supreme Court had already ruled that the RPT assessments imposed by the Province of Nueva Vizcaya against CE Casecnan Water and Energy Company, Inc. were valid, although the amount payable must be recomputed. The law provides for the reduction and condonation of RPT liabilities, including special levies, penalties, and interests, on properties, machinery, and equipment actually and directly used by independent power producers (IPPs) in the production of electricity under build-operate-transfer (BOT) contracts with government-owned or controlled corporations (GOCCs). Since CE Casecnan was an IPP that entered into a BOT agreement with the National Irrigation Administration (NIA), a GOCC, it was entitled to the benefits  of the law. The Supreme Court further held that the reduced RPT amount should be deducted from the amount already paid by CE Casecnan, even though the taxes had already been settled, because the law  does not distinguish between unpaid liabilities and taxes already paid at the time of its effectivity. Accordingly, the Supreme Court remanded the case to the Central Board of Assessment Appeals (CBAA) to determine the refundable amount, if any. The Court En Banc held that CE Casecnan was not required to file a separate written claim for refund under Section 253 of the LGC, because the refund arose directly from the final and executory judgment of the Supreme Court, and requiring another claim would result in the re-litigation of issues already conclusively resolved and would violate the doctrine of immutability of final judgments. The CBAA therefore correctly proceeded to compute the refund and determined that CE Casecnan was entitled to refund. The Court sustained the CBAA’s factual findings, recognizing that the CBAA was in the best position to evaluate the documents and records submitted by the parties, and found no grave abuse of discretion in its determination. (Province of Nueva Vizcaya v. CE Casecnan Water and Energy Company, Inc., CTA EB Case No. 2979, February 12, 2026)

A CITY’S AUTOMATIC INCREASE OF ITS LFT RATE FROM 50% OF 1% TO 75% OF 1% IN THE SAME REVENUE ORDINANCE WAS VOID BECAUSE TAX RATE INCREASES MUST BE MADE THROUGH A SUBSEQUENT ORDINANCE, NOT MORE THAN ONCE EVERY FIVE YEARS, AND BY NO MORE THAN 10% OF THE PREVAILING RATE, RESULTING IN THE CANCELLATION OF THE ADDITIONAL LFT ASSESSMENTS. While cities may impose a local franchise tax (LFT) of up to 75% of 1% of gross annual receipts, any increase in tax rates must comply with the law by being effected through a subsequent tax ordinance, imposed not more often than once every five years, and limited to a maximum 10% adjustment from the prevailing rate. Applying these principles, the CTA held that the City’s automatic increase of the LFT rate from 50% of 1% to 75% of 1%, contained in the same revenue ordinance, was ultra vires and invalid because the adjustment was not made through a separate ordinance and exceeded the allowable 10% increase from the existing tax rate. Consequently, the CTA reversed the RTC, declared the franchise tax adjustment void, and cancelled the additional LFT assessments (Manila Electric Company v. San Jose del Monte City et. al., CTA AC No. 329, November 12, 2025)

A MUNICIPALITY VALIDLY INCREASED THE LBT RATE ON CONTRACTORS FROM 0.55% TO 0.60% BECAUSE THE ADJUSTMENT WAS MADE SIXTEEN YEARS AFTER THE PREVIOUS ORDINANCE AND DID NOT EXCEED THE 10% INCREASE LIMIT PRESCRIBED BY THE LOCAL GOVERNMENT CODE. Local government units may adjust tax rates not more than once every five years, provided that the increase does not exceed ten percent (10%) of the rates fixed under the existing ordinance. Jurisprudence likewise clarifies that the 10% limitation is reckoned from the tax rate imposed under the immediately preceding valid tax ordinance. Applying these principles, the Court found that the Municipality of Pagbilao validly increased the local business tax (LBT) rate on contractors from 55% of 1% (0.55%) under the 2001 Revised Revenue Code to 60% of 1% (0.60%) under the 2017 Revised Revenue Code, as the ordinances were enacted sixteen years apart and the 0.05% increase was within the allowable 10% ceiling of the previous rate. Accordingly, the Court upheld the validity and legality of the contractor’s LBT rate under the 2017 Revised Revenue Code. (The Municipality of Pagbilao, Shierre Ann Portes-Palicpic, in her capacity as Municipal Mayor of the Municipality of Pagbilao, and Rizalino P. Tina, in his capacity as Assistant Municipal Treasurer of the Municipality of Pagbilao v. Team Energy Corporation, CTA AC Case No. 350, March 13, 2026)

A NON-STOCK, NON-PROFIT MUTUAL BENEFIT ASSOCIATION PROVIDING WELFARE BENEFITS EXCLUSIVELY TO ITS MEMBERS IS NOT AN INSURANCE COMPANY OR OTHER FINANCIAL INSTITUTION UNDER THE INSURANCE CODE AND, ABSENT AN EXPRESS STATUTORY IMPOSITION, IS NOT SUBJECT TO LBT WARRANTING THE REFUND OF THE ERRONEOUSLY COLLECTED LBT. LBT may be imposed only on businesses operated for profit and on banks and other financial institutions, including insurance companies, as defined under applicable laws. The Insurance Code expressly excludes mutual benefit associations (MBAs) from the definition of insurance companies, and the Department of Finance likewise recognizes that MBAs are not insurance companies subject to LBT. Applying these provisions, the CTA found that the taxpayer is a duly organized non-stock, non-profit mutual benefit association whose primary purpose is to provide financial assistance, retirement, and welfare benefits to its members, who are personnel of public safety offices, and not to engage in commercial or profit-making insurance business. Its Articles of Incorporation and By-Laws established that its operations are conducted solely for the mutual benefit of its members and not as a means of livelihood or with a view to profit. Consequently, the taxpayer is neither an insurance company nor any other financial institution and cannot be subjected to LBT on its mutual benefit operations. The CTA further emphasized that the taxpayer was not invoking a tax exemption but merely asserting that no law expressly imposed LBT on mutual benefit associations, reiterating the settled rule that taxes cannot be imposed by implication and any ambiguity in tax imposition must be resolved in favor of the taxpayer. Finding no statutory basis for the assessment, the CTA reversed the RTC and ordered the City of San Juan to refund the erroneously collected LBT [(Public Safety Mutual Benefit Fund, Inc. v. San Juan City Treasurer (CTA Case No. 308, February 3, 2026)]

WHERE A CITY MERELY ISSUED BILLING STATEMENTS DURING BUSINESS PERMIT RENEWAL WITHOUT A VALID DEFICIENCY TAX ASSESSMENT, THE FILING OF ADMINISTRATIVE AND JUDICIAL CLAIMS WITHIN TWO YEARS FROM PAYMENT IS A PROPER REMEDY. Section 195 of the Local Government Code applies only when the local treasurer issues a valid notice of assessment for deficiency taxes, which must state the nature of the tax, the amount of deficiency, and the corresponding surcharges, interests, and penalties. Absent such a valid assessment, the taxpayer’s remedy is governed by Section 196, which allows the filing of an administrative and judicial claim for the refund of taxes erroneously or illegally collected within two years from payment. Applying these principles, the Court held that the Billing Statements issued by the Business Permits and Licensing Office during the renewal of respondent’s business permits were not notices of assessment under Section 195 because they merely reflected the business taxes and regulatory fees due, without assessing any deficiency tax, surcharge, interest, penalty, or demand for payment. The city’s own witness likewise admitted that no notices of assessment were issued. Consequently, the taxpayer was not required to file a protest under Section 195 but properly availed itself of the refund remedy under Section 196 by filing its administrative and judicial claim, both within the applicable two-year prescriptive period. Accordingly, the Court sustained the timeliness of respondent’s refund claims and ruled that Section 196, rather than Section 195, governed the case. (Atty. Voltaire Enriquez, in his capacity as City Treasurer of Taguig v. Dacon Corporation, CTA AC No. 321, November 6, 2025; see also Royal Cargo, Inc. v. City Treasurer of Parañaque, CTA AC No. 337, Civil Case No. 2021-010, February 18, 2026)

A HOLDING COMPANY WHOSE BUSINESS IS MERELY OWNING SHARES AND RECEIVING DIVIDENDS IS NOT A NON-BANK FINANCIAL INTERMEDIARY SUBJECT TO LBT; A LOCAL ORDINANCE TAXING ITS DIVIDEND INCOME IS VOID. Local government units are authorized to impose LBT on dividend income only when received by banks and other financial institutions, including non-bank financial intermediaries (NBFIs). A holding company does not become an NBFI merely because it owns shares or receives dividends from its investments; to qualify as an NBFI, it must be authorized to perform quasi-banking functions and regularly engage in financial intermediary activities. Applying these principles, the Court found that the taxpayer’s Articles of Incorporation established that its primary purpose was to own and hold shares of stock and manage its subsidiaries, not to perform quasi-banking or financial intermediary functions. Accordingly, the taxpayer was a holding company, not a bank or NBFI, and its receipt of dividend income did not subject it to LBT. The Court further ruled that Taguig Ordinance, which imposed LBT on dividend income received by holding companies, was invalid because it expanded the taxing authority granted under the Local Government Code and therefore contravened the statute. As local government units possess only delegated taxing powers, they cannot impose taxes beyond those authorized by Congress. Consequently, the Court affirmed the refund of the LBT erroneously collected on  the taxpayer’s dividend income. (Atty. Voltaire Enriquez, in his capacity as City Treasurer of Taguig v. Dacon Corporation, CTA AC No. 321, November 6, 2025)

THE CTA HAS NO APPELLATE JURISDICTION OVER CHALLENGES TO A REGULATORY ENVIRONMENTAL FEE BECAUSE AN EXACTION IMPOSED PRIMARILY TO FUND WATERSHED PROTECTION UNDER A CITY’S POLICE POWER IS A REGULATORY FEE – NOT A LOCAL TAX – EVEN IF IT INCIDENTALLY GENERATES REVENUE. The Court of Tax Appeals has appellate jurisdiction only over decisions of Regional Trial Courts involving local tax cases. Whether an exaction constitutes a tax or a regulatory fee depends on its primary purpose – if imposed primarily to generate revenue, it is a tax; if imposed principally to regulate under the police power, any revenue generated is merely incidental. Applying these principles, the Court held that the Environmental Tax under a Davao City Ordinance was not a local tax but a regulatory fee, as its primary purpose was to fund the protection, conservation, and management of the city’s watershed pursuant to the local government’s police power and environmental mandates under the Local Government Code. Since the exaction was regulatory rather than revenue-raising, it did not constitute a local tax. Consequently, the CTA lacked jurisdiction to entertain the appeal and dismissed the petition for lack of jurisdiction (Dole Philippines, Inc. – Stanfilco Division v. The Sangguniang Panlungsod of the City of Davao, et. al., CTA AC No. 325, March 11, 2026)

A LOCAL GOVERNMENT UNIT CANNOT REFUSE TO ACCEPT LBT PAYMENTS FOR FAILURE TO PRESENT PROOF OF UPDATED RPT PAYMENT. The Local Government Code does not require payment of RPT as a prerequisite to the payment of LBT. Courts cannot read into the law conditions that are not expressly provided. Likewise, the LGU’s Revenue Code merely prescribes the requirements for the issuance of a business permit and do not authorize local officials to refuse acceptance of LBT payments due to unpaid RPT. Applying these principles, the Court held that the municipality had no legal basis to reject the taxpayer’s LBT payments solely because of the absence of proof of updated RPT payment; consequently, the surcharges and penalties imposed on such refusal were invalid, and the trial court correctly ordered their refund (The Municipality of Pagbilao, Shierre Ann Portes-Palicpic, in her capacity as Municipal Mayor of the Municipality of Pagbilao, and Rizalino P. Tina, in his capacity as Assistant Municipal Treasurer of the Municipality of Pagbilao v. Team Energy Corporation, CTA AC Case No. 350, March 13, 2026)

A TAXPAYER MAY DIRECTLY CHALLENGE THE VALIDITY OF AN INCREASED LBT RATE IN COURT WITHOUT FIRST APPEALING TO THE SECRETARY OF JUSTICE WHEN THE ISSUE IS A PURE QUESTION OF LAW INVOLVING COMPLIANCE WITH THE LOCAL GOVERNMENT CODE, MAKING THE DOCTRINE OF EXHAUSTION OF ADMINISTRATIVE REMEDIES INAPPLICABLE. The doctrine of exhaustion of administrative remedies does not apply when the issue raised is a pure question of law, as the interpretation and application of laws are matters within the exclusive competence of the courts. Jurisprudence recognizes that a taxpayer need not first exhaust administrative remedies, such as an appeal to the Secretary of Justice, where the controversy does not involve disputed facts but solely the determination of what the law provides under established circumstances. Applying this principle, the Court held that taxpayer was not barred from questioning the validity of the increased LBT rate under the Revised Revenue Code because the issue involved only the legal question of whether the increase complied with the limitations imposed by the Local Government Code. Since no factual matters were in dispute, the Court validly exercised jurisdiction despite the taxpayer’s failure to appeal before the Secretary of Justice (The Municipality of Pagbilao, Shierre Ann Portes-Palicpic, in her capacity as Municipal Mayor of the Municipality of Pagbilao, and Rizalino P. Tina, in his capacity as Assistant Municipal Treasurer of the Municipality of Pagbilao v. Team Energy Corporation, CTA AC Case No. 350, March 13, 2026)

ALTHOUGH LBT ACCRUES ON JANUARY 1, AN INCREASED TAX RATE UNDER A NEW REVENUE ORDINANCE APPLIES ONLY FROM THE FIRST DAY OF THE SUCCEEDING QUARTER AFTER THE ORDINANCE’S EFFECTIVITY, ENTITLING THE TAXPAYER TO A REFUND OF THE EXCESS LBT COLLECTED USING THE HIGHER RATE BEFORE IT BECAME EFFECTIVE. While local taxes generally accrue on the first day of January, any new tax or adjustment in tax rates takes effect only on the first day of the quarter following the effectivity of the ordinance imposing such change. Applying this rule, the Court held that although taxpayer’s LBT for Calendar Year 2018 was initially assessed under the 2001 Revised Revenue Code, the enactment of the 2017 Revised Revenue Code on 21 May 2018 required the application of the new contractor’s tax rate of 60% of 1% beginning only in the third and fourth quarters of 2018, while the first and second quarters remained subject to the 2001 rate. Recomputing the taxpayer’s tax liability using the proper quarterly rates, the Court found that the correct LBT for each of the third and fourth quarters resulted in an overpayment. Consequently, while affirming the RTC’s ruling that the 2017 Revised Revenue Code governed the latter half of 2018, the Court modified the computation and ordered the municipality to refund the excess LBT. (Mayor of the Municipality of Pagbilao, and Rizalino P. Tina, in his capacity as Assistant Municipal Treasurer of the Municipality of Pagbilao v. Team Energy Corporation, CTA AC Case No. 350, March 13, 2026)

REVENUE ISSUANCES

Revenue Memorandum Circular No. 084-2026, July 2026.

The BIR clarifies certain provisions of Revenue Regulations No. 004-2026, prescribing the guidelines and procedures for the availment of the one-time abatement of taxes and/or penalties for micro taxpayers

Certificate of Existence of Outstanding Tax Liability/ies Controlling document to determine the liability/threshold; to be requested from Issuing Offices (i.e. RDO for open stop-filer cases)
Mixed income earners May avail of abatement
Taxpayer classification
  • Must be a Micro Taxpayer
Place of filing RDO where Micro Taxpayer is registered (BIR Form No. 2121); RDO of head office (for multiple branches)
Pending compromise settlement and abatement of penalties
  • Taxpayer can still apply for abatement
  • Taxpayer should withdraw the pending compromise settlement
  • Administrative appeals against PAN, FAN/FLD or FDDA not deemed withdrawn
Covered taxes
  1. Taxpayer statutorily liable for the tax sought to be abated (e.g. seller for CGT, donor for DST) is classified as a Micro Taxpayer
  2. The liability is covered under Section 4 of RR No. 004-2026; and
  3. The covered liability as of December 31, 2025, as certified by the issuing office, does not exceed Php80,000.00
  • RR No. 004-2026 does not distinguish as to the type of transaction involved, provided that the application satisfies the Php80,000.00 threshold per taxable year and all other requirements under the said RR
Covered penalties
  • All types – interests, surcharges, open case penalties, compromise penalties.
  • For purposes of the Php80,000.00, unpaid basic taxes and compromise penalties shall be included in the computation while surcharges and interests shall be excluded therefrom
RATE cases and Fraud cases General rule: Not covered

Exception: if allowed by the CIR or his duly authorized representative.
Multiple years involved
  • Can be abated separately
  • Deadline should fall as of December 31, 2025
  • Php80k threshold applies per year (i.e., you can apply 5 applications for different taxable years if each of the 5 years does not exceed Php80k)
Unfiled returns No need to file unfiled returns

Covered liabilities are cancelled and considered settled upon issuance of the Certificate of Availment and completion of the prescribed procedures
Regularizing the records (for micro taxpayers who ceased operations but wish to update and rectify registration/records)
  • Can be abated
  • Threshold should be observed
Surcharge and interest
  • Surcharge and interest not covered in the computation; but considered abated
All taxes per taxable year
  • Threshold is not per tax type
  • Taxpayer cannot choose which tax type to abate
Reducing basic tax to meet the threshold by payment
  • Partial payment to be applied first against interests, surcharge and compromise penalties
  • Payment is made on or before December 31, 2025
  • No refund for partial payment
  • Scenario: taxpayer made partial payment even if original basic tax liability is lower than Php80K and covered by the program
Reasons for denial Taxpayer’s classification; timeliness; out of scope; out of coverage; threshold; non-payment of abatement fee; incomplete application; lack of required approval for RATE cases; and material misrepresentation
Non submission of proof of payment within 5 days
  • Not a ground for denial
  • Application is void but can be refiled
Application processed after December 31, 2026 Still timely as long as application is filed on or before December 31, 2026
No collection enforcement upon filing of application Suspended until application is denied, voided and withdrawn
Certificate of Availment
  • Serves as basis for the preparation of Authority to Cancel Assessment
  • To be issued within 5 working days from receipt of the proof of payment
  • Closes the covered cases for the taxable year
  • Not a tax clearance
  • May support application for closure/cancellation of business registration but subject to proper application
No more audit No field audit or new investigation by reason of application for the taxable year; application is evaluated on the documents submitted

BIR DEADLINES FROM AUGUST 3, 2026 TO AUGUST 9, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
AUGUST 5, 2026 SUBMISSION – Summary Report of Certification issued by the President of the National Home Mortgage Finance Corporation (NHMFC). Month of July 2026

e-FILING & PAYMENT (Online/Manual) – BIR Form 2000 (Monthly Documentary Stamp Tax Declaration/Return). Month of July 2026

e-FILING & PAYMENT (Online/Manual) – BIR Form 2000-OT (Documentary Stamp Tax Declaration/Return One Time Transactions). Month of July 2026
AUGUST 8, 2026 SUBMISSION – All Transcript Sheets of Official Register Books (ORBs) used by Dealers/Manufacturers/Toll Manufacturers/Assemblers/Importers of Alcohol Products, Tobacco Products, Petroleum Products, Non-Essential Goods, Sweetened Beverage Products, Mineral Products & Automobiles. Month of July 2026

e-SUBMISSION – Monthly e-Sales Report for All Taxpayers using CRM/POS and/or Other Similar Business Machines whose last digit of 9-digit TIN is Even Number. Month of July 2026

COURT OF TAX APPEALS DECISIONS

PAGCOR LICENSEES OPERATING IN THE CLARK FREEPORT ZONE ARE SUBJECT TO THE SPECIAL 5% TAX ON GROSS INCOME EARNED (3% NATIONAL GOVERNMENT, 2% LGU) UNDER THE GOVERNING CFZ LAW, RATHER THAN THE GENERAL 5% FRANCHISE TAX UNDER THE PAGCOR CHARTER, MAKING THE CONTRARY PORTION OF RMC NO. 32-2022 NULL AND VOID; SEE DISSENTING OPINION. PAGCOR is subject to a 5% franchise tax on gross revenues or earnings from its gaming operations in lieu of all other national and local taxes, and this tax exemption extends to its licensees and contractees with respect to income derived from casino operations; however, PAGCOR licensees located within a special economic zone or freeport zone are likewise entitled to the special tax regime applicable to registered business enterprises in that zone. Applying these principles, although the PAGCOR Charter extends the 5% franchise tax regime to PAGCOR licensees, taxpayers here were registered businesses operating within the Clark Freeport Zone (CFZ), whose governing law grants registered business enterprises exemption from national and local taxes in exchange for a 5% tax on gross income earned (GIE), with 3% remitted to the National Government and 2% to the relevant LGU. The CFZ tax regime is a special law specifically applicable to businesses located in the zone and therefore prevails over the general 5% franchise tax regime under the PAGCOR Charter. The taxpayer’s Certificates of Registration and Tax Exemption likewise confirmed their entitlement to the 5% GIE regime. Applying the 5% franchise tax to PAGCOR licensees in the CFZ, while subjecting other registered businesses in the same zone to the 5% GIE tax, would defeat the legislative intent to provide uniform tax incentives to businesses located in the country’s ecozones and freeport zones. Thus, the assailed portion of RMC No. 32-2022, which provided that the gaming income of PAGCOR licensees in ecozones or freeport zones remains subject to the 5% franchise tax instead of the applicable 5% GIE regime, is null and void for being inconsistent with the governing law; accordingly, the taxpayers’ gaming income remained subject to the 5% tax on gross income earned, and not the 5% franchise tax. Dissenting Opinion:  The 5% franchise tax applies to the gaming revenues of PAGCOR licensees in lieu of other national and local taxes, even where the licensee operates in an ecozone or freeport. RMC No. 32-2022 merely clarified that the gaming income of PAGCOR licensees remains subject to the 5% franchise tax and not to the GIT, ITH, or corporate income tax, even if the licensee is located in an ecozone or freeport. The PAGCOR Charter prevails over the BCDA incentives regime, as it is the special law specifically governing the gaming industry. Lastly, the PAGCOR Charter governs the tax treatment of gaming income; while The BCDA regime may continue to apply to non-gaming income or matters not specifically covered by the PAGCOR Charter [BIR et al. v. BB International Leisure and Resort Development Corporation, et al., CTA EB No. 2975 (CTA Case No. 10841), February 23, 2026]

A CONDOMINIUM CORPORATION IS NOT SUBJECT TO LBT ABSENT PROOF OF A PROFIT-ORIENTED BUSINESS, AS ASSOCIATION DUES AND ASSESSMENTS COLLECTED SOLELY TO FUND THE MAINTENANCE AND ADMINISTRATION OF COMMON AREAS ARE NOT COMMERCIAL REVENUES; THUS, THE TAXPAYER WAS NOT A TAXABLE CONTRACTOR UNDER THE TAGUIG REVENUE CODE. The liability for Local Business Tax (LBT) presupposes that the taxpayer is engaged in “business,” meaning trade or commercial activity regularly pursued as a means of livelihood or with a view to profit; therefore, the mere receipt of money or collection of assessments does not, by itself, establish that an entity is engaged in a taxable business. Here, the taxpayer, a condominium corporation organized under the Condominium Act, was legally restricted to holding the common areas, managing and administering the condominium project, and undertaking acts necessary, incidental, or convenient to those purposes. Its Articles of Incorporation and By-laws were consistent with these statutory limitations and did not authorize activities directed toward the pursuit of livelihood or profit. The association dues, membership fees, and other assessments collected from unit owners were likewise not revenues earned from a commercial enterprise or consideration for services rendered for a fee; rather, they constituted a common fund used to pay for the maintenance, repair, improvement, reconstruction, and administrative expenses of the condominium project and common areas for the benefit of the unit owners. Consequently, the taxpayer could not be treated as a contractor under the Taguig Revenue Code merely because it collected these assessments, and the LGU failed to present sufficient evidence that the taxpayer was engaged in any other profit-oriented activity. The Supreme Court has recognized that condominium corporations generally do not engage in trade or business when managing and maintaining common areas for the benefit of unit owners and are therefore generally not subject to local business taxation, irrespective of a local ordinance attempting to impose such tax. Although a condominium corporation may potentially become liable for LBT if it is proven to have engaged in activities for profit, no such activities were alleged or established in this case; the assessment was based solely on the collection of assessments used to defray authorized condominium expenses.  [City Treasurer of Taguig City v. Cedacrest Condominium Corporation, CTA EB No. 3061 (RTC SCA No. 291), March 31, 2026; see also City Treasurer of Taguig City v.  Rosewood Pointe Residences Condominium Corporation, CTA EB No. 3008, (SCA Case No. 298 and MeTC Civil Case No. 22-4575) November 27, 2025]

A HOLDING COMPANY THAT MERELY OWNS SHARES AND RECEIVES DIVIDENDS, WITHOUT BSP AUTHORIZATION OR REGULAR FINANCIAL-INTERMEDIARY ACTIVITIES, IS NOT A BANK, FINANCIAL INSTITUTION, OR QUALIFIED NBFI SUBJECT TO LBT ON GROSS RECEIPTS UNDER THE LGC; ORDINANCE CANNOT EXPAND THE LGU’S DELEGATED TAXING POWER. An LGU may impose LBT on the gross receipts of banks and other financial institutions, including qualified non-bank financial intermediaries (NBFIs), but the taxing power of an LGU is merely delegated and must be strictly construed, with any doubt resolved against the municipality. LGC permits the imposition of LBT on the specified gross receipts of banks and other financial institutions, while LGU also defines the entities covered, and it generally prohibits LGUs from imposing income taxes, except on banks and other financial institutions. An entity is considered an NBFI only if the requisites for such classification concur, including BSP authorization to perform quasi-banking functions, principal functions involving the lending, investing, or placement of funds or evidence of indebtedness or equity, and the regular and recurring performance of recognized financial intermediary activities. Applying these rules, the taxpayer’s ownership of shares in a corporation and receipt of dividends did not make it a bank, financial institution, or NBFI because taxpayer was not authorized by the BSP to perform quasi-banking functions and did not regularly or recurringly receive funds from one group for lending or investment with another, principally acquire debt or equity securities using funds received, or borrow against, lend on, or trade in debt or equity securities. The taxpayer was instead a holding company, whose principal purpose was to hold shares in another company to control its policies, and any investment activity was merely incidental to that purpose. The Court therefore distinguished the taxpayer  from financial intermediaries that actively deal with public funds. Consequently, the assessment of LBT on the taxpayer’s dividends had no legal basis, and the local ordinance could not expand the taxing authority granted to the City by the LGC. [Atty. Voltaire Enriquez in his capacity as the City Treasurer of Taguig City v. La Lumiere Holdings, Inc., CTA AC No. 346, December 16, 2025; see also Enriquez v. Rice Creek Holdings, Inc., CTA AC NO 322 (RTC Civil Case No. 663) November 12, 2025, Enriquez v. Chrismon Investments, Inc., CTA AC No 323, February 4, 2026]

REVENUE ISSUANCES

Revenue Memorandum Order No. 14-2026

Pursuant to the Bureau of Internal Revenue’s authority to regulate tax administration, Revenue Memorandum Order (RMO) No. 14-2026 partially revokes certain procedural provisions of RMO No. 4-2025 (particularly Section E) regarding the verification and handling of Cannot Be Located (CBL) taxpayers.

APPLICATION OF FACTS
    Revenue Officers (ROs) must immediately exclude the revoked RMO No. 4-2025 procedures when auditing, verifying, or handling taxpayers flagged as absent or missing from their registered business addresses.
REVOKED SECTION
  • Validate the taxpayer’s non-existence/untraceability and secure supporting certifications and documents.
  • If validation is negative and the taxpayer has no distrainable or leviable property, recommend classification as a “Suspense Account” (11-F-A).
  • Approved CBL dockets remain with the concerned office and in the AR/DA Inventory List for continuing monitoring.
  • Dockets tagged 11-F-A may be recommended for write-off after three (3) consecutive negative validations, with at least twelve (12) months between qualifying validations. The initial validation is not counted.
  • Upon approval of the write-off recommendation and completion of validation, issue an Authority to Cancel Assessment (ATCA). Physical dockets must be kept by the RMD/AHRMD for seven (7) years.
  • If the taxpayer resurfaces, verify the reporting office, require the prescribed Affidavit of Undertaking, update or untag the taxpayer’s registration, and continue collection remedies. Any ATCA previously issued shall be revoked, if applicable.
  • No taxpayer may be reported as CBL, and no ATCA may be issued, without the required review and approval. Written-off dockets must be microfilmed and retained for future reference.

REVENUE ISSUANCES

Revenue Memorandum Order No. 015-2026

Under the tax authority’s power to streamline administrative procedures, the Bureau of Internal Revenue (BIR) reiterates and standardizes the guidelines for processing Freedom of Information (FOI) requests to ensure uniform implementation and eliminate processing delays.

COVERED ISSUANCE All requests to any office under EO No. 2 s. 2016
STANDARD PROCEDURE – FOI Receiving Officer will be designated (initial point of contact for FOI request)
– FOI Request form to be accomplished. Purpose must be stated (general purpose i.e. for information, for research not allowed)
GROUNDS TO DENY REQUEST
  1. Incomplete request
  2. Material misrepresentation
  3. BIR’s lack of custody of the information
  4. Vexatious request
  5. Out of scope request
FOI DECISION MAKER WILL DENY OR APPROVE Grounds to deny (other than the above):

  1. 60-day period to provide clarification lapsed
  2. Information is covered by Executive privilege
  3. Privileged information relating to National Security, Defense or Relations:
  4. Information related to Law enforcement and protection of public and personal safety
  5. Confidential information
  6. Prejudicial premature disclosures

Revenue Memorandum Circular No. 75-2026 

Under the tax authority’s power to streamline administrative procedures, the Bureau of Internal Revenue (BIR) consolidates and clarifies the guidelines for processing the One-Time Transaction (ONETT) Computation Sheet (OCS) and the electronic Certificate Authorizing Registration (eCAR) to ensure uniform implementation and improve the ease of doing business. 

COVERED ISSUANCE
  1. ONETT Transactions
  2. Sale of Real Property Considered as Capital and Ordinary Asset
  3. Sale, Transfer or Assignment of Stocks Not Traded in the Stock Exchange
  4. Estate
MODES OF FILING AND PAYMENT OF RELATED TAXES Filing: Electronically; manual, if electronic mode is unavailable
Payment – manual or electronic, unless eFPS filer (except not available); for manual payment – any AABs
WHERE TO PROCESS ECAR
  1. Sale of real property (capital or ordinary) – where property is located
  2. Shares not traded in local stock exchange – residence of the transferor-individual as indicated in the BIR system; place of registration for non-individual
  3. Donation – same with transfer of shares not listed in stock exchange
  4. Estate – where Estate of the TIN is issued; if deceased has registered business – where business is registered (because it is where the TIN was secured); if no registered business, RDO where administrator or heirs intend to apply for the issuance of eCAR
INSTANCES OF ANTEDATED SALE
  1. Documents dated before September 7, 1979 or effectivity of Capital Gains Tax Law
  2. Documents dated prior to effectivity of CWT regulations
  3. Documents dated prior to effectivity of current zonal values
  4. Proof of no ante-dating: cancelled checks, invoices, CTS, certification from court or notarial archives
WHOSE TIN IS REQUIRED
  1. Sale of property – transferor and transferee
  2. Donation – Donor and Donee
  3. Estate – Deceased, heirs, administrator (if any)
  4. Spouse’s TIN not required, except when property sold or donated is conjugal or community or spouse is a party to the transaction (buyer or donee)
LOST eCAR Taxpayer to request for reprinting of the same eCAR. Taxpayer to submit written request, original copy of the supporting documents and payment of certification fee.
PROPERTIES ACQUIRED BY BANKS VIA FORECLOSURE SALE
  • Considered ordinary asset
  • Banks not considered habitually engaged in the real estate business for purposes of determining the withholding tax rate
REAL PROPERTIES SOLD BY REAL ESTATE LESSORS
  • Automatically deemed ordinary asset (all properties for lease/rent or being offered for lease/rent or for use in trade or business)
NO DELAY OF eCAR RELEASE IF VAT IS NOT YET PAID UPON APPLICATION
  • No proof of VAT payment is required.
  • eCAR processing office to inform RDO having jurisdiction over the seller to verify and assess VAT, if warranted.
BUYER ASSUMES CGT Amount of tax should not be added in the selling price for purposes of determining the CGT Tax Base; computation is based on higher between Selling price or FMV, whichever is higher.
DST ON INSTALLMENT SALE COVERED WITH CTS DST to accrue upon execution of DOAS; but tax base is at the time when CTS was executed.
DACION EN PAGO Ordinary asset – Taxes applicable: CWT, VAT and DST
Capital asset – Taxes applicable: CGT and DST
INSPECTION REQUIRED
  1. Conflict of data as to the existence of the improvement in documents presented
  2. Taxpayer’s invocation of special law that will result in payment of a lesser tax
  3. To be conducted within the processing period and should not delay the issuance of eCAR
FORECLOSURE SALE CGT is due 30 days from expiration of redemption period/judicial confirmation/registration of the certificate of sale.

Judicial foreclosure involving Bank-mortgagee – redemption period is 1 year from registration of certificate of sale; if non-bank – CGT is due 30 days from confirmation of the foreclosure of sale by the court.

Extrajudicial foreclosure – redemption period is 1 year from registration of the certificate of sale.

Extrajudicial foreclosure where mortgagor is a juridical person and mortgagee is a bank – redemption period shall last until the registration of the certificate of sale, which shall in no case be later than 3 months after the foreclosure, whichever is earlier.

CWT – 10 days (following end of the month in which the redemption period expires, judicial confirmation of the foreclosure sale, or registration of the certificate of sale, as the case may be).

DST – 5 days (following the end of the month; reckoning point – same as CWT).
PRIOR CANCELLATION OF DECEDENT’S TIN BEFORE ESTATE PROCESSING Not required; can be accomplished parallel to the processing of the estate; issuance of estate TIN is not contingent on the cancellation of the TIN of the decedent with business.

Estate of deceased person is issued a TIN separate from TIN of the deceased person.

Closure of decedent’s business with BIR is not required prior to the filing of estate tax return.

BIR DEADLINES FROM JULY 20, 2026 TO JULY 26, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
JULY 20, 2026 SUBMISSION – Quarterly Information on OCWs or OFWs Remittances Exempt from DST furnished by the Local Banks & Non-Bank Money Transfer Agents – For the Quarter ending June 30, 2026

SUBMISSION – Quarterly Report of Printer – For the Quarter ending June 30, 2026

e-FILING & PAYMENT (Online/Manual) – BIR Form 1600 WP (Remittance Return of Percentage Tax on Winnings and Prizes Withheld by Race Track Operators) – eFPS & Non-eFPS Filers. Month of June 2026
JULY 25, 2026 SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers. Non-eFPS Filers – For the Quarter ending June 30, 2026

SUBMISSION – Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products – For the Quarter ending June 30, 2026

e-FILING & PAYMENT (Online/Manual) – BIR Form 2550Q (Quarterly Value-Added Tax Return). eFPS & Non-eFPS Filers – For the Quarter ending June 30, 2026

e-FILING & PAYMENT (Online/Manual) – BIR Form 2551Q (Quarterly Percentage Tax Return). eFPS & Non-eFPS Filers – For the Quarter ending June 30, 2026

e-FILING & PAYMENT (Online/Manual) – BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider). For the Quarter ending June 30, 2026

e-FILING & PAYMENT (Online/Manual) – BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider). For the Quarter ending June 30, 2026

Dear Valued Clients:

We hope this message finds you well.

Please be advised that Vince Noel Lupango is no longer connected with Dumlao Law Offices effective December 22, 2025, and has no affiliation whatsoever with the Firm after the said date. Any communication or transaction made by him after said date is undertaken solely in his personal capacity. Accordingly, the Firm shall not be responsible for, nor be bound by, any such communication or undertaking.

Should Mr. Lupango, or any of our former staff now under his employ, contact you or any member of your organization after the said date, we would appreciate it if you could kindly inform us so that we may take the appropriate action.

We sincerely appreciate your continued trust and confidence in our Firm.

Thank you for your continued support.

Sincerely,

Dumlao & Co.

COURT OF TAX APPEALS DECISIONS

NEW LOA IS REQUIRED IN CASE OF RE-ASSIGNMENT OF AUDIT TO ANOTHER RO; MOA IS NOT SUFFICIENT; BIR CANNOT VALIDLY REPRODUCE ITS FINDINGS IN THE FLD/FAN WITHOUT ADDRESSING THE TAXPAYER’S EXPLANATIONS. Only revenue officers specifically authorized under a valid Letter of Authority (LOA) may examine a taxpayer’s books of account, and any reassignment of the audit to another Revenue Officer (RO) must be covered by a new LOA issued by the Commissioner of Internal Revenue (CIR) or a duly authorized official. The same provisions likewise mandate that the Preliminary Assessment Notice (PAN), Formal Letter of Demand/Final Assessment Notice (FLD/FAN), and Final Decision on Disputed Assessment (FDDA) state the factual and legal bases of the assessment and meaningfully address the taxpayer’s explanations and evidence; otherwise, the assessment is void for violating due process. Applying these rules, the Court held that although the original LOA authorized ROs Rosario Arriola and Sheila Samaniego to conduct the audit, the actual examination was undertaken by RO Abigail Cayabyab pursuant only to a MOA, without the issuance of the required new LOA, rendering the audit unauthorized and the resulting assessments void. The Court further found that the BIR failed to observe due process because, despite the taxpayer’s timely protest to the PAN, the FLD/FAN merely reproduced verbatim the findings and computations contained in the PAN, without discussing or addressing the taxpayer’s explanations, defenses, and supporting documents, thereby showing that the protest was not genuinely evaluated. [Commissioner of Internal Revenue v. NCR Corporation Philippines, CTA EB No. 2967 (CTA Case No. 10498), March 23, 2026; see also Nationwide Health Systems Baguio, Inc. v. Commissioner of Internal Revenue (CTA Case No. 10686) November 7, 2025]

BIR’S FAILURE TO PROVE THAT PERSONAL SERVICE WAS IMPRACTICABLE BEFORE RESORTING TO SUBSTITUTED SERVICE AND FAILURE TO PRESENT THE REQUIRED WITNESSES AND PROOF OF MAILING CONSTITUTE A DENIAL OF DUE PROCESS. The Tax Code requires strict compliance with the prescribed modes and procedures for the valid service of assessment notices. Personal service is the primary mode, while substituted service or service by mail may only be resorted to when personal service is not practicable, subject to specific requirements. Here, the Court found that the Bureau of Internal Revenue (BIR) failed to establish that personal service of the PAN and FLD/FAN was impracticable, relying merely on the statement of the building guard without conducting reasonable verification. Further, the BIR failed to prove valid service by mail of the PAN as it presented only an LBC official receipt, which did not sufficiently identify the document sent, and failed to submit the required proof of delivery and sworn written report. Likewise, the substituted service of the PAN and FLD/FAN was invalid because the BIR failed to bring a barangay official and two disinterested witnesses to personally observe and attest to the taxpayer’s absence, as required by the regulations, and the notices were instead received by barangay staff member who was not shown to be a proper barangay official. Accordingly, the failure to strictly comply with the requirements for service deprived the taxpayer of due process, rendering the PAN, FLD/FAN, and the resulting Warrant of Distraint and/or Levy void and unenforceable. (Sabre Travel Network Philippines, Inc. v. Commissioner of Internal Revenue, CTA Case No. 10848, November 4, 2025)

NO VIOLATION OF DUE PROCESS IF BIR SIGNIFICANTLY REDUCED ASSESSMENT. Administrative due process in tax assessment proceedings requires that the taxpayer be properly notified of the assessment, given a meaningful opportunity to present defenses and supporting evidence, and that the BIR duly consider such submissions and render a decision based on the evidence presented. Due process does not require that the taxpayer’s arguments be accepted, but only that the taxpayer’s defenses be fairly evaluated and that the administrative body explain the basis of its conclusions. Applying these principles, the Court En Banc held that the taxpayer was not denied due process despite its claim that the CIR allegedly ignored its protest and supporting documents until the issuance of the FDDA. The Court found that after the taxpayer filed its protest against the FAN, the CIR evaluated its arguments and evidence and issued the FDDA explaining the basis for sustaining or rejecting the taxpayer’s defenses. The fact that the CIR substantially considered taxpayer’s submissions only at the FDDA stage did not invalidate the assessment proceedings, as the taxpayer was afforded an opportunity to be heard and its defenses were ultimately considered. Moreover, the evaluation of taxpayer’s protest resulted in a significant reduction of the basic deficiency VAT assessment, demonstrating that the CIR did not disregard the taxpayer’s submissions but instead took them into account in resolving the assessment. Accordingly, the Court ruled that the requirements of administrative due process were substantially complied [CIR v. BASF Philippines, Inc., CTA EB No. 2754 (CTA Case No. 10221); BASF Philippines, Inc. v CIR, CTA EB No. 2755. CTA Case No. 10221), November 12 2025]

A STATEMENT THAT INTEREST AND THE TOTAL AMOUNT DUE SHALL BE ADJUSTED IF PAYMENT IS MADE AFTER THE DUE DATE DOES NOT RENDER THE ASSESSMENT VOID. A taxpayer must be informed of the specific amount of tax assessed and be given a definite period within which to pay the assessed liability. In determining the validity of an assessment, jurisprudence provides that an assessment is void when it fails to indicate a fixed and determinate amount of tax due and does not provide a specific due date for payment, thereby leaving the taxpayer uncertain as to the extent of its obligation. In the present case, however, the Court En Banc ruled that the FAN and the Amended Assessment Notice attached to the FDDA substantially complied with these requirements. Both notices clearly stated the basic deficiency VAT assessed, as well as the corresponding total amount due and the specific deadlines for payment, thereby providing the taxpayer with sufficient notice of its tax liability. The Court further held that the statement in the notices that the interest and total amount due would be adjusted if payment was made beyond the specified date did not make the assessment indefinite or uncertain. Such statement merely recognized that interest continues to accrue until full payment and that the final amount payable may increase due to the taxpayer’s delay in settlement. Hence, the FAN and FDDA issued against the taxpayer constituted a valid demand for payment containing a definite tax liability and due date, thereby complying with the requirements of administrative due process. [CIR v. BASF Philippines, Inc., CTA EB No. 2754 (CTA Case No. 10221); BASF Philippines, Inc. v CIR, CTA EB No. 2755. CTA Case No. 10221), November 12 2025]

IN CASE OF APPEAL DUE TO DEEMED DENIAL OF PROTEST, NO NEW 180-DAY PERIOD COMMENCES UPON THE FILING OF A REQUEST FOR RECONSIDERATION WITH THE OFFICE OF THE COMMISSIONER. A taxpayer who receives a FLD/FAN may protest the assessment and, if the protest is not acted upon within 180 days from the filing of the request for reconsideration or from the submission of complete supporting documents in case of a request for reinvestigation, may either appeal to the CTA within 30 days from the lapse of the 180-day period or await the final decision on the protest and appeal within thirty (30) days from receipt thereof. However, the 180-day period applies only to the initial administrative protest against the FLD/FAN and does not create a separate or fresh 180-day period for an administrative appeal or request for reconsideration filed after the issuance of a decision by the Commissioner’s duly authorized representative. In this case, the taxpayer submitted its Request for Reinvestigation on January 18, 2019 and completed the submission of supporting documents on February 6, 2019; hence, the CIR or his duly authorized representative had until August 6, 2019 to act on the protest. The Regional Director subsequently issued the FDDA dated March 15, 2021, which the taxpayer received on April 23, 2021, prompting the taxpayer to file a Request for Reconsideration before the Commissioner on May 24, 2021. The taxpayer erroneously assumed that the Commissioner was granted another 180-day period to act on the administrative appeal and consequently filed its Petition for Review on December 20, 2021, counting 30 days from the supposed lapse of the new 180-day period. The Court ruled that no such additional period exists. Since the FDDA had already resolved the administrative protest, the taxpayer’s remedy was either to appeal the FDDA within thirty (30) days from receipt or await the Commissioner’s final decision on the administrative appeal and appeal such decision within the prescribed period. Having filed its Petition for Review beyond the allowable period, the CTA was deprived of jurisdiction over the case; thus, the petition was dismissed without consideration of the merits of the deficiency tax assessment. (Allied Metals, Inc. v. CIR, CTA Case No. 10711, November 4, 2025)

BIR MUST CONDUCT A MINIMUM 10-DAY SURVEILLANCE PERIOD BEFORE CLOSING A BUSINESS ESTABLISHMENT; 4-HOUR VISIT NOT SUFFICIENT. The CIR may suspend business operations and temporarily close business establishments for specified violations, such as failure to issue receipts or invoices, understatement of taxable sales, or failure to file VAT returns. However, the regulations require the conduct of a duly authorized surveillance for a minimum of 10 days before a taxpayer may be classified as a non-compliant taxpayer and before the issuance of a 48-Hour Notice, 5-Day Notice of Violation Conference (VCN), or Closure Order. Applying these rules, the Court held that the BIR violated the taxpayer’s right to due process because, although the Mission Order expressly directed the RO to conduct surveillance for violations of bookkeeping rules, the evidence showed that the supposed surveillance consisted only of a single 4-hour visit, which plainly failed to satisfy the mandatory 10-day surveillance period. The BIR likewise failed to present any written authority extending, shortening, or exempting compliance with the surveillance requirement. The Court further rejected the BIR’s reliance on a later regulation, explaining that while it prescribes procedures for the post-evaluation of point-of-sale (POS) machines, it neither supersedes nor dispenses with the surveillance requirements under a prior regulation governing business closures. Since the post-evaluation relied solely on extracted POS data without the benefit of the mandatory surveillance, it did not constitute substantial evidence of the BIR’s alleged violations. Absent the mandatory surveillance, the BIR could not validly be classified as a non-compliant taxpayer, thereby rendering the 48-Hour Notice, 5-Day VCN, and Closure Order void for lack of factual and procedural basis and in violation of the BIR’s constitutional right to due process [Commissioner of Internal Revenue v. Rebecca D. Duka, CTA EB No. 3050 (CTA Case No. 10393), December 22, 2025)

A PCL AND A FNBS MAY BE ASSAILED BEFORE THE CTA AS “OTHER MATTERS” UNDER THE TAX CODE AND ARE NOT SUBJECT TO THE PROTEST PROCEDURES APPLICABLE TO FLD/FANS.  The Tax Code prescribes the procedure for protesting a tax assessment and provides that a taxpayer may file a request for reconsideration or reinvestigation within 30 days from receipt of a valid assessment, with the corresponding judicial appeal to the Court of Tax Appeals to be filed within 30 days from receipt of the denial of the protest or from the lapse of the 180-day period without action. However, this presupposes the existence of a valid assessment, which jurisprudence defines as a written notice containing not only the computation of the taxpayer’s tax liability but also a demand for payment within a specified period, together with the legal and factual bases of such assessment. Consistent with this, the regulations provide that the administrative protest is directed specifically against an FLD/FAN and not against mere collection notices or other BIR communications. In this case, the Court held that the taxpayer incorrectly applied the procedures when it filed requests for reinvestigation against the Preliminary Collection Letter (PCL) and Final Notice Before Seizure (FNBS). The Court found that these documents were not assessments because they did not contain the essential elements of a valid assessment, such as the computation of the alleged deficiency taxes, the legal and factual bases supporting the liability, and a formal demand for payment within a definite period. Rather, the PCL and FNBS were merely collection letters issued by the BIR arising from the taxpayer’s alleged failure to settle deficiency taxes based on a prior FAN, which the taxpayer claimed it never received. Thus, the taxpayer’s recourse was not to file a protest but to directly challenge the BIR’s collection action as an “other matters”,  such action must be appealed to the CTA within 30 days from receipt of the assailed BIR decision or action. Since the taxpayer received the PCL on June 11, 2018 and the FNBS on June 26, 2018, it should have filed its Petition for Review not later than July 11, 2018 and July 26, 2018, respectively. Its filing only on April 8, 2019 was therefore made beyond the prescribed period, causing the loss of its statutory right to appeal and depriving the CTA of jurisdiction to entertain the case. Accordingly, the Court affirmed the dismissal of the petition for being filed out of time. [Encore Receivable Management, Inc. v. Commissioner of Internal Revenue, CTA EB No. 2937 (CTA Case No. 10062), November 11, 2025]

CTA EN BANC HAS NO JURISDICTION OVER INTERLOCUTORY ORDERS. The Court En Banc has exclusive appellate jurisdiction only over decisions or resolutions on motions for reconsideration or new trial rendered by the Court in Division in the exercise of its jurisdiction over cases arising from administrative agencies, such as the BIR. However, jurisprudence consistently distinguishes between final judgments, which fully dispose of a case and leave nothing more to be done by the court, and interlocutory orders, which do not finally resolve the parties’ rights and liabilities and merely address incidental matters while the main case remains pending. The Court En Banc has no jurisdiction to review interlocutory orders of the Court in Division because allowing such appeals would result in piecemeal litigation, multiplicity of appeals, and unnecessary delay in the resolution of the main case. In this case, although the assailed Resolution was issued in relation to the taxpayer’s Motion for Reconsideration, the Court in Division’s finding that the BIR’s right to assess was preliminarily barred by prescription did not constitute a final adjudication of the tax case. The Court in Division expressly characterized its finding as preliminary, granted only the suspension of collection, lifted the Warrant of Distraint and/or Levy, and prohibited collection of the deficiency VAT, without making a definitive ruling on the validity of the assessment, the Assessment Notices, or the FDDA. [Commissioner of Internal Revenue v. Perf Restaurants, Inc., CTA EB No. 3132 (CTA Case No. 11231), November 6, 2025]

BIR FINDINGS BASED ON TPI WITHOUT COMPLIANCE WITH REQUIREMENTS ARE VOID. The regulations require the BIR to verify TPI obtained through the Reconciliation of Listings for Enforcement (RELIEF) System before using it as the basis of a tax assessment. These issuances mandate the sending of confirmation requests to the identified TPI sources, the procurement of sworn statements attesting to the accuracy of the reported data, and, where the TPI sources are located outside the investigating office’s jurisdiction, the service of confirmation requests by registered mail with registered return cards before proceeding with the assessment. Applying these rules, the Court sustained the cancellation of the deficiency VAT assessment for alleged undeclared sales because the BIR failed to properly validate the RELIEF-generated TPI. Although the BIR relied on TPI indicating undeclared sales with a VAT tax base, the confirmation letters were sent to only four of the seven customers, only one confirmation letter was allegedly received, and, most significantly, the BIR failed to present any registered return cards proving that the confirmation requests had been served on customers located outside the jurisdiction of the investigating office. Thus, the TPI remained unverified and could not constitute competent factual basis for the assessment. [CIR v. BASF Philippines, Inc., CTA EB No. 2754 (CTA Case No. 10221); BASF Philippines, Inc. v CIR, CTA EB No. 2755. CTA Case No. 10221), November 12 2025]

WHEN A TAX ASSESSMENT IS BASED ON THIRD-PARTY INFORMATION (TPI), THE RO MUST VERIFY THE ALLEGED DISCREPANCIES BY ISSUING CONFIRMATION REQUESTS TO THE THIRD-PARTY SOURCE AND OBTAINING DULY EXECUTED SWORN STATEMENTS ATTESTING TO THE ACCURACY OF THE DATA BEFORE SUCH INFORMATION MAY SERVE AS THE FACTUAL BASIS OF AN ASSESSMENT. Presumption of correctness of a tax assessment applies only when it is supported by actual facts and credible evidence, and cannot rest on unverified or self-serving data. Applying these principles, the Court held that the assessment for unsupported purchases was void because the BIR merely relied on system-generated TPI data comparing the taxpayer’s Summary List of Purchases with its supplier’s reported sales, without presenting duly notarized sworn statements or other competent evidence confirming the alleged discrepancies. The BIR’s reliance on the absence of a response from third-party sources was insufficient, rendering the assessment arbitrary and without factual foundation. [The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue (CTA Case No. 11091, November 12, 2025); see also CIR v. BASF Philippines, Inc., CTA EB No. 2754 (CTA Case No. 10221); BASF Philippines, Inc. v CIR, CTA EB No. 2755. (CTA Case No. 10221), November 12 2025]

BIR MAY ASSESS TAXPAYER BASED ON UNACCOUNTED SOURCE OF CASH. Tax assessments are presumed correct and made in good faith, and the burden rests upon the taxpayer to prove by substantial evidence that the assessment is erroneous; bare allegations, unsupported by competent documentary evidence, have no probative value and cannot overcome the presumption of correctness. Applying these principles, the Court sustained the assessment for an unaccounted source of cash because the BIR established a discrepancy between the additions to property and equipment reflected in the taxpayer’s Notes to the Audited Financial Statements and its Statement of Cash Flows, while the taxpayer’s explanation that the difference pertained to inventory purchases made in 2017 and later transferred to property and equipment was unsupported by any documentary evidence. Consequently, the taxpayer failed to discharge its burden of proving that the assessment was erroneous. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

PRODUCTIVITY INCENTIVES GRANTED TO RANK-AND-FILE AND SUPERVISORY EMPLOYEES ARE SUBJECT TO  WITHHOLDING TAX, NOT FBT; AN RO CANNOT VALIDLY SUBJECT THE ENTIRE AMOUNT TO FBT WITHOUT DETERMINING CLASSIFICATION OF EMPLOYEE. FBT applies only to fringe benefits granted by an employer to managerial or supervisory employees, while benefits given to rank-and-file employees, as well as certain de minimis benefits and productivity incentives within the limits prescribed by regulations, are excluded from FBT. In this case, the BIR assessed the taxpayer deficiency FBT on productivity incentives and bonuses, alleging that the taxpayer failed to withhold FBT on these payments. The taxpayer, however, established that the amounts represented productivity bonuses granted under its Efficiency Productivity System (EPS), which were subjected to withholding tax on compensation, and submitted its Guidance Document on the Productivity Point System showing that the incentives were granted to both rank-and-file and supervisory employees who exceeded production standards. The Court found that the revenue officer improperly subjected the entire amount to FBT without determining whether the recipients were managerial, supervisory, or rank-and-file employees, despite the exclusion of rank-and-file employees from FBT coverage. Moreover, the revenue officer’s testimony revealed uncertainty as to the proper tax treatment of productivity incentives, admitting that such incentives should instead be treated as compensation subject to withholding tax. Since the BIR failed to present evidence proving that the entire amount of incentives was exclusively granted to managerial or supervisory employees or otherwise fell within the scope of taxable fringe benefits, the assessment lacked sufficient factual and legal basis. Accordingly, the Court cancelled the deficiency FBT assessment against the taxpayer (Somnomed Philippines, Inc. v. CIR, CTA Case NO. 10845, March 19, 2026)

THE BIR CANNOT VALIDLY DISALLOW ADMINISTRATIVE SALARIES AND WAGES EXPENSES IF THE TAXPAYER IS AVAILING OF 5% GIT. An enterprise availing of the five percent (5%) Gross Income Tax (GIT) incentive is subject to tax based on its gross income earned, which refers to gross sales or revenues derived from business activities within the ecozone, less sales discounts, returns, allowances, and cost of sales or direct costs. Unlike ordinary taxpayers, administrative, marketing, selling, operating expenses, and incidental losses are not deducted in determining the taxable base under the GIT regime. In this case, the BIR disallowed salaries, wages, and benefits that were purportedly not subjected to withholding tax, after reconciling the taxpayer’s salaries and benefits per its Income Tax Return and Audited Financial Statements against its Monthly Remittance Returns of Income Taxes Withheld on Compensation. The taxpayer argued that the alleged deficiency had no effect on its tax liability considering that it was a PEZA-registered export manufacturing enterprise subject to the five percent (5%) GIT regime. The Court found merit in the taxpayer’s position, holding that the disallowance pertained to operating expenses and, therefore, could not affect the computation of the taxpayer’s GIT liability because such expenses are not deductible in arriving at gross income earned. Hence, there was no basis to sustain the BIR’s adjustment since the taxpayer sufficiently explained the discrepancy and the BIR failed to establish that the alleged non-withholding resulted in any deficiency tax liability. Accordingly, the assessment for disallowed salaries, wages, and benefits due to alleged non-withholding was cancelled for lack of factual and legal basis (Somnomed Philippines, Inc. v. CIR, CTA Case NO. 10845, March 19, 2026)

MEAL EXPENSES CAN BE DEDUCTED UNDER GIT REGIME IF SUBSTANTIATED AND TAXPAYER PROVED THAT THEY WERE INCURRED DIRECTLY RELATED TO PRODUCTION ACTIVITIES. Deductions from gross income must be supported by sufficient evidence, such as official receipts, invoices, and other relevant accounting records, to establish the fact, amount, and business purpose of the claimed expense. For PEZA-registered enterprises availing of the five percent (5%) GIT incentive, only costs of sales or direct costs are considered in arriving at gross income earned, while administrative, selling, marketing, and other operating expenses are excluded from the computation of the taxable base. Here, the Court found that the taxpayer had established that meal expenses were incurred and were directly related to its production activities, thereby forming part of its cost of sales and allowable direct costs under the GIT regime. The Court further considered the examination conducted by the taxpayer’s independent CPA of the supporting official receipts and invoices and determined that the majority of the claimed meal expenses were adequately substantiated. Nevertheless, the Court held that some expenses could not be allowed because they were either unsupported by sufficient documents, covered only by defective receipts, or could not be properly linked to the taxpayer’s business operations. (Somnomed Philippines, Inc. v. CIR, CTA Case NO. 10845, March 19, 2026)

TO EXCLUDE REIMBURSEMENTS RECORDED AS RECEIVABLES FROM UNDECLARED INCOME, THE TAXPAYER MUST PRESENT SUFFICIENT SUPPORTING EVIDENCE; MERE SCHEDULES DO NOT SUFFICE. All income from whatever source derived is taxable unless specifically excluded by law, and a taxpayer claiming that certain receipts constitute non-taxable reimbursements or a mere return of capital bears the burden of proving such claim through competent and sufficient evidence. Applying this rule, the Court sustained the deficiency assessment for undeclared income after the BIR compared the taxpayer’s VAT returns, annual income tax return, and trade receivables, revealing a discrepancy in reported income. The taxpayer’s contention that the trade receivables included reimbursements of airfare, visa fees, training, medical, and other pre-employment expenses advanced on behalf of its foreign clients was rejected because the schedules of trade and non-trade receivables it submitted merely reflected a breakdown of receivable balances and did not specifically trace or identify the alleged reimbursements. In addition, the schedules were unsupported by sufficient documentary evidence to verify their accuracy and reliability. (Supply Oilfield & Marine Personnel Services, Inc. v. Commissioner of Internal Revenue, CTA Case No. 11048, December 17, 2025)

THE BIR MAY RELY ON THE PARTIES’ AGREEMENT TO DETERMINE A TAXPAYER’S REVENUE BY GROSSING UP THE INCOME PAYMENT BASED ON A PERCENTAGE OF SALES. All income from whatever source derived is taxable unless expressly excluded by law, and the taxpayer has the burden of proving, by competent and sufficient evidence, that the Commissioner’s assessment is erroneous or that the amounts assessed are not subject to income tax. Applying this rule, the Court upheld the deficiency assessment for undeclared income after the BIR recomputed the taxpayer’s sales based on the Trademark License Agreement which obligated the taxpayer to pay a royalty fee equivalent to 1% of its total sales, and found that the resulting sales exceeded those reported in the taxpayer’s income tax return. The Court rejected the taxpayer’s argument that the assessment was based on mere assumptions and that no undeclared income existed after accounting for an alleged over-recording of fees and deducting withholding taxes. It found that the Trademark License Agreement expressly provided only that total sales should be computed net of VAT or similar sales taxes and contained no provision authorizing the deduction of withholding taxes or showing that the taxpayer had contractually assumed such taxes. Likewise, the taxpayer’s claim of an over-recording of expenses was unsupported by receipts or other competent documentary evidence. In the absence of sufficient proof to substantiate its adjustments or disprove the BIR’s computation, the taxpayer failed to overcome the presumption of correctness of the assessment. (Supply Oilfield & Marine Personnel Services, Inc. v. Commissioner of Internal Revenue, CTA Case No. 11048, December 17, 2025)

ARTICLES OF PARTNERSHIP AND BOA ACCREDITATION ARE INSUFFICIENT, BY THEMSELVES, TO PROVE THAT PAYMENTS TO A GENERAL PROFESSIONAL PARTNERSHIP (GPP) ARE EXEMPT FROM INCOME TAX; PROOF OF PAYMENT IS LIKEWISE REQUIRED. A taxpayer claiming that payments to GPPs are not subject to withholding tax must substantiate both the status of the recipients and the actual payments made. Applying these principles, the Court sustained the deficiency EWT assessment on the disallowed professional fees as the taxpayer merely submitted the Articles of Partnership of Magsalin, Magsalin, and Associates and the Board of Accountancy Certificate of Accreditation of Isla Lipana & Co., but failed to present invoices, official receipts, payment vouchers, or other documentary evidence establishing that the questioned professional fees were actually paid to these GPPs. (Supply Oilfield & Marine Personnel Services, Inc. v. Commissioner of Internal Revenue, CTA Case No. 11048, December 17, 2025)

A TAXPAYER CANNOT ESTABLISH THE INCOME TAX EXEMPTION OF PAYMENTS MADE TO NRFC SOLELY THROUGH A SEC CERTIFICATE OF NON-REGISTRATION AND A BIR RULING THAT IS NOT SPECIFICALLY APPLICABLE TO THE TAXPAYER. A taxpayer claiming that payments to non-resident foreign corporations (NRFC) are exempt from Philippine income tax and withholding tax must establish through competent documentary evidence that the recipients are non-resident foreign corporations not engaged in trade or business in the Philippines and that the income is not derived from Philippine sources. Applying these principles, the Court sustained the deficiency EWT assessment on the disallowed professional fees. Although the taxpayer claimed that the amounts represented payments to Newrest Group International SAS and Newrest Group Services for consultancy services allegedly rendered outside the Philippines, it failed to prove that these entities qualified as non-resident foreign corporations, as the SEC Certificate of Non-Registration submitted for Newrest Group International SAS merely showed that it was not registered in the Philippines and did not establish its foreign corporate status. The Court likewise ruled that the taxpayer could not rely on a BIR ruling because it was issued exclusively in favor of Newrest Group Holding SL, and the taxpayer presented no evidence showing that its coverage extended to Newrest Group International SAS or Newrest Group Services.  Moreover, the Court held that the Consultancy Agreement alone, although stating that Pocomwell Ltd. was organized under the laws of Hong Kong, was insufficient to establish its NRFC status, as the taxpayer failed to present a Certificate of Non-Registration from the SEC, proof of incorporation or registration in Hong Kong, a tax residence certificate, or any other competent evidence demonstrating that Pocomwell Ltd. was not engaged in trade or business in the Philippines. (Supply Oilfield & Marine Personnel Services, Inc. v. Commissioner of Internal Revenue, CTA Case No. 11048, December 17, 2025)

LOCAL TREASURER’S FAILURE TO ACT WITHIN 60 DAYS FROM THE FILING OF A PROTEST IS DEEMED A DENIAL BY INACTION; AN APPEAL FILED BEYOND THE 60-DAY PERIOD IS OUT OF TIME. A taxpayer must appeal to the proper court within 30 days either from receipt of the local treasurer’s denial issued within the 60-day period to resolve the protest or, if no action is taken within that period, from the lapse of the 60-day period, as the treasurer’s inaction constitutes a deemed denial; failure to perfect the appeal within the prescribed period renders the assessment final, conclusive, and unappealable. Applying this rule, although the taxpayer timely protested, the local treasurer failed to act within the 60-day period, resulting in a deemed denial on May 12, 2019, from which the taxpayer had only until June 11, 2019 to file its appeal. Since the appeal was filed only on June 13, 2019, it was filed out of time, rendering the assessment final, executory, and unappealable, and the subsequent receipt of the actual denial on May 14, 2019 did not extend or reset the appeal period. [Public Safety Mutual Benefit Fund, Inc., represented by its President Emmanuel B. Peralta v. Rosette F. Laquian, Acting City Treasurer, San Juan City, CTA EB No. 3003 (CTA AC No. 245), December 22, 2025]

BIR FORM 2307 SUPPORTS INCOME TAX CREDITS. A taxpayer claiming CWT as tax credits must substantiate the claim with the corresponding BIR Form 2307 or certificates of creditable tax withheld; otherwise, the claimed tax credits may be disallowed. Applying these provisions, the Court sustained the BIR’s disallowance of the taxpayer’s claimed CWT because the taxpayer failed to present the required CWT certificates. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

CGT CANNOT BE VALIDLY CLAIMED AS DEDUCTION FROM INCOME TAX. Although taxes paid or incurred in connection with the taxpayer’s trade or business are generally deductible from gross income, income taxes imposed under the Tax Code, including CGT, are expressly excluded from allowable deductions. Applying this provision, the Court sustained the BIR’s disallowance of the taxpayer’s claimed deduction representing CGT, holding that CGT is a final income tax and, by law, constitutes a non-deductible expense. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

A CGT ASSESSMENT IS SUSTAINED WHERE THE TAXPAYER PRESENTS A DOCUMENT SHOWING A DIFFERENT BUYER THAN THE ONE IDENTIFIED BY THE BIR AND FAILS TO ESTABLISH THAT THE TWO BUYERS ARE RELATED PARTIES. 

A CGT shall be paid upon the filing of the prescribed return, and the taxpayer claiming payment or exemption bears the burden of proving compliance through competent and admissible evidence. Here, the Court sustained the BIR’s deficiency CGT assessment arising from the taxpayer’s sale of 50% of its shares. Although the taxpayer maintained that the CGT had already been paid and submitted a Deed of Absolute Sale, BIR Form No. 1707 (CGT Return), and a Land Bank BIR payment slip, the Court held that these documents could not be considered because they were not admitted in evidence after the taxpayer failed to present their originals for comparison. The Court further ruled that, even if admitted, the documents would still be insufficient to establish that the CGT payment related to the transaction assessed by the BIR, since the assessment involved the sale of shares to Southern Capital, whereas the submitted documents pertained to Sufficient Grace PTE. Ltd. The taxpayer’s assertion that Sufficient Grace and Southern Capital were related entities likewise remained unsubstantiated, as no documentary evidence proving their relationship was presented. Significantly, the taxpayer’s own witness admitted during cross-examination that no proof of the relationship between the two corporations had been submitted during the administrative proceedings and merely committed to present additional evidence in the future. Accordingly, the taxpayer failed to establish either that the CGT had been paid on the transaction subject of the assessment or that the payment allegedly made in connection with Sufficient Grace corresponded to the sale of shares to Southern Capital. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

SALE OF SHARES RESULTING IN A CHANGE IN OWNERSHIP DOES NOT GIVE RISE TO A DEEMED SALE OF INVENTORY FOR VAT PURPOSES; DEEMED SALE APPLIES ONLY WHEN THE BUSINESS CEASES OPERATIONS. VAT may be imposed on transactions deemed sale only in the specific instances enumerated by law, including retirement from or cessation of business with respect to inventories on hand. Jurisprudence likewise clarifies that a “change of ownership of business” constitutes a deemed sale only when it occurs as an incident of the taxpayer’s retirement from or cessation of business, and not merely because of a restructuring or disposition of assets. Applying these principles, the Court held that the BIR had no factual or legal basis for assessing VAT on the taxpayer’s inventories. Although the taxpayer reduced its ownership in its subsidiary through the sale of shares, the Court found that this transaction did not constitute a change in the taxpayer’s line of business from coffee manufacturing to a holding company. The taxpayer’s Amended Articles of Incorporation expressly authorized it not only to manufacture and sell coffee products but also, under its secondary purposes, to invest in other corporations. Thus, the sale of its investment was consistent with its corporate purposes and did not amount to a retirement from or cessation of business. Since the taxpayer continued its operations and none of the statutory circumstances giving rise to a deemed sale were present, the assessment for deficiency VAT on inventories was declared without factual and legal basis and was accordingly cancelled. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

TO ESTABLISH THAT A SALE IS VAT-EXEMPT, THE TAXPAYER MUST PRESENT THE CERTIFICATE OF REGISTRATION AND TAX EXEMPTION (CRTE), WHICH MUST BE FORMALLY OFFERED AND ADMITTED IN EVIDENCE. A taxpayer claiming VAT-exempt sales bears the burden of proving its entitlement to the exemption through competent and admissible evidence. Correspondingly, the allocation of input tax to exempt sales applies only where the taxpayer has sufficiently established that such sales are indeed VAT-exempt. Applying these principles, the Court upheld the BIR’s deficiency VAT assessment on the taxpayer’s alleged unsupported VAT-exempt sales. Although the taxpayer claimed that certain sales were VAT-exempt and asserted that it had presented a CRTE issued by the Subic Bay Metropolitan Authority (SBMA), the records showed that it submitted only a photocopy of the CRTE, which the Court had previously denied admission as evidence. In the absence of any competent and admissible proof establishing the VAT-exempt status of the transactions, the taxpayer failed to substantiate its claim of exempt sales. Consequently, the Court likewise rejected the BIR’s adjustment disallowing as input tax allocable to exempt sales, holding that since the alleged exempt sales were not proven and were instead treated as taxable sales, there was no basis to allocate or deduct any portion of the allowable input tax as attributable to exempt sales. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

VAT INVOICING REQUIREMENTS ARE ALSO APPLICABLE IN ASSESSMENT CASES AND NOT CONFINED TO CLAIMS FOR VAT REFUNDS. A taxpayer may claim creditable input VAT only when the same is supported by a valid VAT invoice or official receipt issued in accordance with the statutory invoicing requirements. Mandatory information that must appear on such document includes the seller’s VAT registration details, TIN, amount of VAT, date of transaction, description of goods or services, and other relevant particulars. In this case, the taxpayer argued that the strict enforcement of invoicing requirements should only apply to VAT refund claims and not to tax assessment proceedings. The Court En Banc, however, rejected this contention, holding that the law makes no distinction between refund cases and assessment cases in requiring compliance with invoicing rules. The Court ruled that the same statutory requirements govern all instances where a taxpayer seeks recognition of input VAT, whether as a credit against output VAT in an assessment case or as the basis for a refund claim. Thus, the validity of input VAT depends upon strict compliance with the invoicing requirements imposed by law, and a taxpayer cannot invoke a more lenient standard merely because the issue arises in an assessment proceeding rather than a refund application. [CIR v. BASF Philippines, Inc., CTA EB No. 2754 (CTA Case No. 10221); BASF Philippines, Inc. v CIR, CTA EB No. 2755. CTA Case No. 10221), November 12 2025]

MERE FAILURE TO DECLARE IMPORTATIONS OR PAY THE CORRESPONDING INPUT VAT CANNOT, BY ITSELF, ESTABLISH THE EXISTENCE OF UNDECLARED SALES SUBJECT TO OUTPUT VAT. VAT shall be imposed on every sale, barter, or exchange of goods or properties, and shall be paid by the seller or transferor based on the gross selling price or gross value in money of the goods or properties sold. Thus, before a transaction may be subjected to output VAT, there must first be sufficient proof that a taxable sale, barter, or exchange actually occurred. Importation, standing alone, does not constitute a sale transaction, and the mere failure to declare importations or pay the corresponding input VAT cannot, by itself, establish the existence of undeclared sales subject to output VAT. Applying these principles, the Court upheld the cancellation of the deficiency VAT assessment arising from the alleged undeclared sales attributed to unaccounted importations. The BIR alleged that discrepancies existed between the importation figures in the VAT returns and the importation data obtained from the Bureau of Customs, resulting in alleged undeclared importations reflected in its Summary List of Importations (SLI). Using the Cost Ratio Method, the BIR extrapolated these alleged unreported importations into presumed undeclared sales and imposed deficiency output VAT. However, the Court ruled that the BIR’s conclusion was based merely on an inference that imported goods necessarily resulted in sales, without presenting independent and competent evidence proving that such goods were actually sold in the course of the taxpayer’s business. No sales invoices, official receipts, inventory records, or other documentary evidence were presented to establish the occurrence and amount of the alleged taxable sales. Since VAT liability cannot arise from a presumption of sale based solely on importation discrepancies, the BIR failed to establish the factual basis for the assessment. Accordingly, the Court held that the deficiency VAT assessment was properly cancelled for lack of sufficient factual and evidentiary support. [CIR v. BASF Philippines, Inc., CTA EB No. 2754 (CTA Case No. 10221); BASF Philippines, Inc. v CIR, CTA EB No. 2755. CTA Case No. 10221), November 12 2025]

EXCESS INPUT VAT CREDITS FROM PRIOR PERIODS MUST BE PROVED BY SUFFICIENT DOCUMENTARY EVIDENCE. A taxpayer is allowed to claim input VAT credits only to the extent that such credits are properly substantiated and remain available for application against output VAT. A taxpayer claiming excess input VAT credits carried over from prior periods bears the burden of proving, through sufficient documentary evidence, that the credits were validly earned, properly recorded, and remained unutilized in subsequent taxable periods. In this case, the Court En Banc sustained the disallowance of claimed excess input VAT credits which it sought to apply against its assessed deficiency VAT liability. The Court found that the taxpayer failed to present adequate evidence showing that the alleged excess input VAT credits from prior periods had not yet been applied or exhausted and were still available for carry-over. [CIR v. BASF Philippines, Inc., CTA EB No. 2754 (CTA Case No. 10221); BASF Philippines, Inc. v CIR, CTA EB No. 2755. CTA Case No. 10221), November 12 2025]

ABSENCE OF FORMAL DEBT INSTRUMENT DOES NOT PRECLUDE IMPOSITION OF DST. DST is an excise tax imposed on the transaction itself rather than on the document evidencing it. Thus, loan agreements and similar transactions are subject to DST regardless of the form of the documentation, and the taxpayer bears the burden of proving either that the transaction is not subject to DST or that the corresponding tax has been properly remitted. The Court applied prevailing jurisprudence holding that the absence of formal debt instruments does not preclude the imposition of DST because the tax attaches to the loan transaction itself and not to the document evidencing it. Since the taxpayer neither disputed the existence of the advances nor presented proof that the corresponding DST had been paid, the Court sustained the deficiency DST assessment in full. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

DST RETURN AND PROOF OF PAYMENT TO THE BIR CONSTITUTE THE BEST EVIDENCE OF PAYMENT OF DOCUMENTARY STAMP TAX; CHECK VOUCHERS ALONE ARE INSUFFICIENT. A DST is imposed on taxable documents and transactions, including lease agreements and certain advances, and the taxpayer asserting that the DST has already been paid or remitted bears the burden of proving actual payment to the BIR through competent and credible documentary evidence. Applying this rule, the Court sustained the deficiency DST assessment after the BIR found that the taxpayer failed to file and pay DST on its lease agreements and advances from related parties, as disclosed in its audited financial statements and supplementary information submitted to the BIR. Although the taxpayer maintained that it had already shouldered the DST by remitting the corresponding amounts to the other contracting parties for payment to the BIR, the Court held that such assertion was unsupported by sufficient proof. The lease agreement confirmed that the taxpayer was contractually liable for the DST, and while the corresponding check voucher showed payment its lessor, the taxpayer failed to present any documentary evidence, such as a DST return or proof of payment to the BIR, establishing that the lessor actually remitted the tax. Similarly, the check vouchers submitted to support the alleged payment on advances from related parties merely evidenced insurance-related payments and bore no relation to the payment or remittance of DST on the advances in question. (Supply Oilfield & Marine Personnel Services, Inc. v. Commissioner of Internal Revenue, CTA Case No. 11048, December 17, 2025)

DST TO BE CLAIMED AS DEDUCTIBLE MUST BE SUPPORTED BY PROOF OF TAX PAYMENT. No deduction from gross income shall be allowed unless the taxpayer substantiates the claimed expense with sufficient evidence, such as official receipts or other adequate records, establishing both the amount of the expense and its direct connection to the taxpayer’s business. Banks and other specified financial institutions are responsible for remitting DST when they are parties to a taxable transaction. Applying these principles, the Court sustained the BIR’s disallowance of the taxpayer’s claimed DST expense. Although the taxpayer argued that the DST had already been withheld and remitted by the banks involved in its loan transactions, it failed to present competent evidence proving that the transactions were indeed entered into with banks or that the corresponding DST had actually been remitted. In the absence of adequate documentary support to substantiate the deduction and rebut the presumption of correctness of the assessment, the Court upheld the disallowance of the claimed DST expense. (The Table Group Inc., represented by Mr. Walden Chu v. Commissioner of Internal Revenue, CTA Case No. 11091, November 12, 2025)

BIR DEADLINES FROM JULY 13, 2026 TO JULY 19, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING / SUBMISSION
July 13, 2026 E-FILING – BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – eFPS Filers under Group C. Month of June 2026
July 14, 2026 E-FILING – BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – eFPS Filers under Group B. Month of June 2026
July 15, 2026 REGISTRATION (Online thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Account/Invoices and Other Accounting Records. Fiscal Year ending June 30, 2026

SUBMISSION – List of Medical Practitioners – For the Quarter ending June 30, 2026

SUBMISSION – Quarterly List (with Monthly Breakdown) of Contractors of Gov’t. Contracts entered into by the Provinces/Cities/Municipalities/Barangays – For the Quarter ending June 30, 2026

E-FILING & PAYMENT (Online/Manual) – BIR Form 1702-RT/1702-EX/1702-MX – Fiscal Year ending March 31, 2026

E-FILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return for Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending March 31, 2026

E-FILING & PAYMENT (Online/Manual) – BIR Form 2200-M (Excise Tax Return for Mineral Products) – For the Quarter ending June 30, 2026

E-FILING & E-PAYMENT – BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – eFPS Filers under Group A. Month of June 2026

E-PAYMENT – BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – eFPS Filers under Group E, D, C & B. Month of June 2026
July 16, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers. July 1–15, 2026

COURT OF TAX APPEALS DECISIONS

THE ASSESSMENT WAS VOID BECAUSE THE RO, WHO HAD NO AUTHORITY UNDER THE LOA, CONDUCTED THE AUDIT, EXAMINATION, AND RECOMMENDATION OF DEFICIENCY ASSESSMENTS; SEE DISSENTING OPINION. Examination of a taxpayer must be conducted only by the Revenue Officers (RO) specifically authorized under a valid Letter of Authority (LOA) as the LOA is the exclusive source of authority to examine a taxpayer’s books and records; any assessment resulting from an audit conducted by unauthorized officers is void, and any collection proceeding based thereon is likewise invalid. Here, the Court held that although the LOA authorized Revenue Officer Ami and Group Supervisor Causapin to examine the taxpayer’s books, the audit, examination, and recommendation of the deficiency assessments were actually performed by Revenue Officer Ventura, who admitted conducting the examination despite having no valid LOA authorizing her to do so. Consequently, the assessment was a nullity from the outset, and the subsequent collection measures. Dissenting Opinion: CTA lacks jurisdiction because the taxpayer failed to file a timely administrative protest against the Formal Letter of Demand/Final Assessment Notice (FLD/FAN), thus, the assessment had attained finality, thereby authorizing the BIR to proceed with collection. Accordingly, the CTA could only determine whether the Warrant of Distraint and/or Levy (WDL) was properly issued in the course of collection, but could no longer invalidate the underlying assessment based on alleged defects in the LOA. The dissent cautioned that allowing the taxpayers to challenge the FLD/FAN indirectly through the CTA’s “other matters” jurisdiction would effectively revive lost remedies, reward failure to comply with statutory protest procedures, improperly expand the CTA’s jurisdiction, and amount to judicial legislation. Consequently, the dissent voted to grant the Petition for Review and uphold the BIR’s collection efforts. [CTA EB No. 2867, CTA Case No. 9745, November 19, 2025; see also CIR v. Misnet Education, Inc., CTA EB No. 2825 (CTA Case No. 9941), November 18, 2025]

TAXPAYER CANNOT BELATEDLY CHALLENGE THE AUTHORITY OF ITS FOOD HANDLERS TO RECEIVE FLD/FAN AND FDDA AFTER CONSISTENTLY ALLOWING THEM TO ACCEPT SUCH DOCUMENTS, INCLUDING LOA WITHOUT OBJECTION. FLD/FAN and Final Decision on Disputed Assessment (FDDA) are validly served when delivered to the taxpayer’s registered address through the modes prescribed by the regulations, and that only a decision or collection notice which constitutes the CIR’s final determination on a disputed assessment is appealable to the CTA. The Court applied the doctrine of equitable estoppel, holding that a taxpayer who previously accepted BIR notices through the same employee and acted upon them cannot later deny such employee’s authority to receive subsequent assessment notices. Applying these principles, the Court found that the FLD/FAN and FDDA were validly served at the taxpayer’s registered address and received by its food handler, who was identified as a staff member. The taxpayer had consistently allowed its food handlers to receive prior BIR communications, including the LOA, and even acted upon those notices without questioning their authority. The Court held that the taxpayer was estopped from later claiming that the same employees were unauthorized to receive the FLD/FAN and FDDA. Consequently, the FDDA became final and executory when the taxpayer failed to appeal within the mandatory 30-day period. Since the taxpayer filed its Petition for Review only after the assessment had become final and executory, the CTA held that it did not acquire jurisdiction over the case and dismissed the petition. (Delicious Kakanin Enterprises Corporation v. CIR and Regional Director, Revenue Region No. 5, Caloocan City, CTA Case No. 10988, March 12, 2026)

ASSESSMENT IS VOID IF THE BIR FAILED TO VALIDLY SERVE THE PAN AND FLD/FAN AFTER SENDING THE NOTICES TO THE TAXPAYER’S FORMER INTRAMUROS ADDRESS DESPITE KNOWLEDGE OF ITS TRANSFER TO QUEZON CITY AND RDO TRANSFER, AND FAILED TO PROVE ACTUAL RECEIPT THEREOF. The assessment notices be served personally, or, if personal service is impracticable, by substituted service or registered mail to the taxpayer’s registered or known address. If the taxpayer denies receipt of assessment notices, the burden shifts to the BIR to establish by competent evidence that the notices were actually received, such as registry return cards bearing the taxpayer’s or its authorized representative’s signature or certifications from the Bureau of Posts. Applying these principles, the Court found that although the BIR claimed to have attempted personal service before sending the PAN and FLD/FAN by registered mail, the notices were sent to the taxpayer’s former address in Intramuros, Manila despite the BIR’s prior knowledge that the taxpayer had already transferred its principal place of business to Quezon City and had completed the corresponding transfer of its RDO. The Court held that the taxpayer had sufficiently established that it had duly informed the BIR of its change of address through the prescribed registration procedures, while the CIR failed to present any evidence to dispute such fact or to prove that the assessment notices were actually received at the old address. The Court likewise rejected the CIR’s contention that the taxpayer should have filed an administrative protest after subsequently requesting and obtaining copies of the assessment notices, stressing that due process requires the BIR itself to validly serve the assessments before the period to protest can commence. The taxpayer’s later acquisition of copies upon request could not cure the invalid service nor validate an assessment that had already been rendered void by non-compliance with the statutory notice requirements. Because the taxpayer was never properly informed of the assessments, it was deprived of the opportunity to administratively contest the alleged deficiency taxes, thereby violating its constitutional right to due process. As a consequence, the PAN, FAN, and FLD were declared void, and the WDL, being merely a collection remedy founded on invalid assessments, was likewise declared without legal basis. (Vestina Security Services, Inc. v. CIR, CTA Case No. 10889, November 24, 2025; see also Freyssinet Philippines, Inc. v. CIR, CTA Case No. 11084, November 21, 2025

TAXPAYER’S LATER DENIAL OF RECEIPT OF PAN IS NOT A NEWLY DISCOVERED EVIDENCE. A taxpayer must be served with a PAN and FLD/FAN, thereby affording the taxpayer an opportunity to respond as part of due process. In addition, under the Rules of Court, a motion for new trial based on additional evidence may be granted only upon proof of fraud, accident, mistake, excusable negligence, or newly discovered evidence. Applying these principles, the Court found that the taxpayer’s right to due process was not violated because the evidence established that the PAN was timely sent through LBC, with the tracking receipt showing that it was posted and scheduled for delivery the following day. More significantly, the taxpayer’s own Finance Clerk, in her original Judicial Affidavit and testimony, unequivocally admitted that BIR officers personally delivered the PAN in and positively identified the PAN presented in court. The taxpayer raised the alleged non-receipt of the PAN only after the CTA Division had rendered an adverse decision, relying on a Supplemental Judicial Affidavit in which the same witness recanted her previous testimony. The Court held that this belated assertion did not constitute newly discovered or omitted evidence because, through the exercise of reasonable diligence, the taxpayer could have raised the issue as early as its receipt of the FAN and certainly during the administrative protest and trial before the CTA. The Court also found the taxpayer’s position to be inherently inconsistent, as it initially argued that it was deprived of the full 15-day period to respond to the PAN, an argument that presupposed receipt of the PAN, before later claiming that it never received the PAN at all. Since the supplemental affidavit merely sought to introduce forgotten evidence through a piecemeal presentation of proof, and no compelling reason existed to warrant a liberal application of procedural rules, the Court sustained the validity of the assessment process and ruled that there was no denial of due process. [IBMS Technology Phils. Corporation v. CIR, CTA EB No. 2907 (CTA Case No. 9970), November 12, 2025]

ISSUANCE OF FLD/FAN ON THE SAME DATE AS ISSUANCE OF THE PAN VIOLATES THE TAXPAYER’S DUE PROCESS. The taxpayer shall have 15 days from receipt of the PAN to submit a reply, and only after receipt of such response or upon the taxpayer’s failure to respond within the prescribed period may the BIR issue the FLD/FAN. The PAN stage is an essential component of administrative due process because it provides the taxpayer an opportunity to dispute the findings and allows the BIR to reconsider its position before issuing a final assessment. The Court likewise ruled that the BIR’s premature issuance of an FLD/FAN before the lapse of the 15-day response period constitutes a denial of due process, and the taxpayer’s subsequent filing of a protest does not cure the defect. In this case, the Court found that the BIR failed to observe the mandatory due process requirements in the issuance of the assessment. The taxpayer received the PAN on January 4, 2012, giving it until January 19, 2012 to file a response. However, the taxpayer issued the FLD/FAN on the same date, January 4, 2012, without waiting for the taxpayer’s reply or the expiration of the 15-day period granted by law and regulations. The fact that the taxpayer subsequently filed a protest to the PAN on January 11, 2012 did not validate the defective assessment, as the BIR had already made a determination of respondent’s alleged tax liabilities without considering any possible response to the PAN. Hence, the premature issuance of the FLD/FAN constituted a violation of respondent’s right to due process, rendering the assessment void and properly subject to cancellation. [CIR v. Asia United Leasing Finance Corporation, CTA EB No. 2984 (CTA Case No. 8525) November 3, 2025; see also CIR v. Misnet Education, Inc., CTA EB No. 2825 (CTA Case No. 9941), November 18, 2025]

A DUE DATE EARLIER THAN THE DATE OF MAILING OF FLD/FAN RENDERS THE ASSESSMENT VOID. A valid FLD/FAN must not only state the taxpayer’s definite tax liability but also require payment within a specific and prospective period. Due date for payment is a substantive requirement, as it affords the taxpayer a real and fair opportunity to comply, and assessments lacking a valid due date are void. Applying these principles, the Court held that the FLD/FAN was invalid even assuming it had been properly served because it indicated September 21, 2022 as the due date for payment but was mailed only on September 23, 2022, making compliance legally impossible before the taxpayer could even receive the notice. The Court ruled that a lapsed due date renders the demand for payment illusory and ineffective, deprives the taxpayer of the opportunity to comply, violates the due process guarantee, which contemplates that delinquency interest accrues only after the taxpayer has been duly notified and has failed to pay on the due date appearing in the notice and demand. Since the FLD/FAN failed to contain a valid, prospective, and enforceable demand for payment, it did not constitute a valid assessment and was declared void (Freyssinet Philippines, Inc. v. CIR, CTA Case No. 11084,November 21, 2025)

BIR HAS 3 YEARS TO ASSESS AS A RULE; TAXPAYER MUST PROVE WHICH PART OF ASSESSMENT PRESCRIBES. The BIR must assess internal revenue taxes within three (3) years from the last day prescribed by law for filing the return or from the actual filing date, whichever is later. Since the BIR neither alleged nor proved the existence of a false or fraudulent return, the ordinary 3-year prescriptive period governed the assessment of the taxpayer’s deficiency taxes. Where the FLD/FAN was issued after 3 years from date of filing, the assessment is considered prescribed. However, the Court held that the assessments for deficiency Income Tax and the December EWT and WTC remained timely, as the FAN was issued within the applicable three-year period for those liabilities. The Court further ruled that a factual determination was still necessary to segregate the alleged deficiencies attributable to the prescribed periods from those pertaining to the non-prescribed periods; otherwise, absent sufficient proof, the deficiencies would be attributed only to the portion of taxable year that remained assessable. [IBMS Technology Phils. Corporation v. CIR, CTA EB No. 2907 (CTA Case No. 9970), November 12, 2025]

BIR CANNOT VALIDLY INVOKE THE 10-YEAR PRESCRIPTIVE PERIOD ABSENT A CLEAR STATEMENT IN THE ASSESSMENT NOTICE, PROOF THAT THE UNDER-DECLARATION EXCEEDED THE 30% THRESHOLD, AND EVIDENCE OF A DELIBERATE OR WILLFUL MISSTATEMENT. The BIR has the right to  assess internal revenue taxes within 3 years from the last day prescribed for filing the return or the actual filing thereof, whichever is later, while the ten 10-year prescriptive period applies only in cases of a false or fraudulent return with intent to evade tax or failure to file a return. The extraordinary 10-year period may be invoked only upon strict compliance with due process requirements, namely: (1) the assessment notice must clearly state that the BIR is applying the 10-year prescriptive period instead of the ordinary 3-year period; (2) it must disclose the factual and legal bases for alleging falsity or fraud, including the computation showing that the taxpayer’s under-declaration exceeded the 30% threshold; and (3) the alleged false return must be supported by clear and convincing evidence of a deliberate or willful misstatement, since a false return requires intentional falsity and not merely an inaccurate declaration. Applying these principles, the Court ruled that the BIR could not rely on the 10-year prescriptive period because the FLD/FAN did not state that the extraordinary period was being invoked, and although the BIR alleged that the taxpayer underdeclared sales by more than 30%, it failed to disclose the computation establishing that threshold. More significantly, the BIR failed to present clear and convincing evidence that the taxpayer deliberately or willfully filed a false VAT return, with its own revenue officer admitting during trial that no evidence of willfulness or intent to evade taxes had been established. Consequently, the Court held that the BIR’s authority to assess had already prescribed, rendering the FLD/FAN and the subsequent FDDA void and without legal effect (Justice Maria Lourdes P.A. Sereno v. CIR, CTA Case No. 10793, December 26, 2026; see also Freyssinet Philippines, Inc. v. CIR, CTA Case No. 11084,November 21, 2025; The City of Manila v. CIR, CTA Case No. 10654, November 12, 2025)

BIR HAS 3 YEARS TO COLLECT, WHICH BEGINS UPON THE ISSUANCE OF THE FLD/FAN; REQUEST FOR RECONSIDERATION DOES NOT TOLL THE RUNNING OF THE PERIOD. When a deficiency tax assessment is validly issued within the ordinary 3-year prescriptive period, the BIR has a separate 3-year period from the date the assessment notice is released, mailed, or sent to the taxpayer within which to collect the assessed taxes through distraint, levy, or judicial action. Jurisprudence likewise establishes that only a request for reinvestigation that is granted by the CIR suspends the running of the period to collect, whereas a mere request for reconsideration does not interrupt prescription. In this case, the taxpayer received the FLD in 2014 to initiate collection. Although the taxpayer subsequently filed a protest in the form of a request for reconsideration, such protest did not suspend the prescriptive period because it neither involved the submission of new evidence nor constituted a granted request for reinvestigation. Since the BIR commenced its collection efforts only in 2020, when the WDL was served, more than 3 years had already elapsed from the date the assessment became collectible. Accordingly, the Court held that the BIR’s right to collect had prescribed, rendering its collection efforts legally unenforceable. CIR v. Jimmy Kho, CTA EB No. 2877 (CTA Case No. 10308), November 18, 2025.

BIR HAS 3 YEARS TO COLLECT; FILING OF ANSWER TO PETITION CONSTITUTES JUDICIAL ACTION FOR COLLECTION. When a tax assessment is validly issued within the 3-year prescriptive period, the BIR has another 3 years from the date the assessment notice is released, mailed, or sent to the taxpayer within which to collect the assessed taxes through distraint, levy, or judicial action. Jurisprudence further recognizes that while a granted request for reinvestigation may suspend the running of the period to collect, the filing of a judicial action for collection, such as the BIR’s Answer to a taxpayer’s petition for review before the CTA praying for payment of the assessed taxes, constitutes a valid mode of collection. In this case, the Court found that although the taxpayer’s protest requested a reinvestigation, there was no evidence that the CIR informed the taxpayer that such request had been granted. Consequently, no suspension of the collection period occurred, and the 3-year period to collect commenced upon the issuance of the FLD/FAN. Nevertheless, before the expiration of this period, the BIR filed its Answer to the taxpayer’s Petition for Review, which, under prevailing jurisprudence, constituted a judicial action for the collection of the assessed taxes. Accordingly, the Court held that the BIR timely initiated collection proceedings and that its right to collect had not yet prescribed. [IBMS Technology Phils. Corporation v. CIR, CTA EB No. 2907 (CTA Case No. 9970), November 12, 2025]

THE FLD/FAN WAS DECLARED VOID BECAUSE, DESPITE THE TAXPAYER’S TIMELY REPLY TO THE PAN WITH EXPLANATIONS, RECONCILIATIONS, AND SUPPORTING DOCUMENTS, THE BIR MERELY REITERATED THE PAN FINDINGS IN THE FLD/FAN WITHOUT ADDRESSING THE TAXPAYER’S DEFENSES OR PROVIDING THE FACTUAL AND LEGAL BASES FOR REJECTING THEM, VIOLATING DUE PROCESS. The BIR must inform the taxpayer in writing of the factual and legal bases of the assessment and, as an essential component of due process, consider and address the taxpayer’s defenses and supporting evidence; otherwise, the assessment is void. While the invalidity of a FDDA does not automatically invalidate the underlying assessment, the assessment itself becomes void when the BIR fails to observe these due process requirements. In this case, although the taxpayer timely filed a Reply to the PAN disputing the alleged undeclared receipts, unsupported interest expense, and deficiency expanded withholding tax through explanations, reconciliations, and supporting documents, the BIR merely reproduced the findings in the PAN in the FLD/FAN with only the interest amounts updated, without addressing or explaining why the taxpayer’s defenses were rejected. As a result, the taxpayer was deprived of meaningful notice of the factual and legal bases for the continued assessment, constituting a denial of due process that rendered the deficiency tax assessments null and void (Bethlehem Holdings, Inc. v. CIR, CTA Case No. 10991, November 18, 2025)

THE TAXPAYER’S PROTEST FILED BEYOND THE 30-DAY PERIOD RENDERS ASSESSMENT FINAL, EXECUTORY, AND DEMANDABLE, DEPRIVING THE CTA OF JURISDICTION. A taxpayer must file a valid protest against a FLD/FAN within 30 days from receipt; otherwise, the assessment becomes final, executory, and demandable, leaving the courts without jurisdiction to review it. Applying these rules, the Court held that although the taxpayer’s protest was dated September 8, 2022, the controlling date was the actual filing date, which was September 14, 2022, as evidenced by the registered mail acceptance stamp on the envelope addressed to the authorized Regional Director. Since the taxpayer received the FLD/FAN on August 10, 2022, he had only until September 9, 2022 to file his protest. The Court ruled that the protest was filed five days late, rendering the assessment final and executory. Consequently, the Court no longer had jurisdiction to review the assessment and dismissed the petition (Mangubat v. CIR, CTA Case No. 11063, February 3, 2026)

CTA LACKS JURISDICTION TO ENTERTAIN PETITION FILED 10 MONTHS AFTER RECEIPT OF THE FDDA. A taxpayer adversely affected by the denial of an administrative protest must either appeal the FDDA to the CTA or elevate the matter to CIR, as the case may be, within 30 days from receipt of the FDDA; otherwise, the assessment becomes final, executory, and demandable. A taxpayer has only three remedies after filing an administrative protest: (1) appeal to the CTA within 30 days from receipt of the denial of the protest; (2) if the denial is issued by the CIR’s authorized representative, elevate the protest to the CIR within the same 30-day period; or (3) in case of inaction, appeal to the CTA within 30 days from the lapse of the 180-day period. Applying these rules, the Court found that the taxpayer received the FLD/FAN on April 12, 2021 and timely filed a request for reinvestigation on April 20, 2021. Although the BIR initially granted the taxpayer 60 days to submit supporting documents, it subsequently informed the taxpayer that it would proceed with the issuance of the FDDA due to the taxpayer’s failure to submit the required documents within the prescribed period. The taxpayer received the FDDA, expressly denominated as the BIR’s “final decision” on the protest, on November 12, 2021. Consequently, the taxpayer had only until December 12, 2021 to either appeal to the CTA or elevate the matter to the CIR. However, the taxpayer filed its Petition for Review only on September 27, 2022, approximately ten (10) months after receipt of the FDDA. The Court therefore held that the petition was filed beyond the mandatory and jurisdictional 30-day period, thereby depriving the CTA of jurisdiction to entertain the case. (Delicious Kakanin Enterprises Corporation v. CIR and Regional Director, Revenue Region No. 5, Caloocan City, CTA Case No. 10988, March 12, 2026)

CTA RETAINED JURISDICTION TO REVIEW THE VALIDITY OF THE WDL UNDER “OTHER MATTERS” BUT WILL NOT RULE ON VALIDITY OF THE ASSESSMENT ITSELF AS WDL COULD NOT BE TREATED AS THE CIR’S DECISION ON THE ASSESSMENT. A taxpayer may appeal to the CTA within 30 days from receipt of the CIR’s adverse decision on a disputed assessment or from the lapse of the 180-day period in case of inaction. Where the taxpayer opts to await the CIR’s decision after the 180-day period, such choice is mutually exclusive from immediately appealing the inaction. The CTA has jurisdiction not only over disputed assessments but also over “other matters” arising under the NIRC, including the validity of WDL. Applying these rules, the Court found that the taxpayer timely protested the FLD/FAN and, after the lapse of the 180-day period without action, elected to await the decision of the BIR’s authorized representative instead of immediately appealing to the CTA. When the authorized representative eventually issued the FDDA the taxpayer filed a Request for Reconsideration with the CIR. However, instead of receiving a decision on the administrative appeal, the taxpayer received WDL, which it argued constituted a constructive denial of its Request for Reconsideration. The Court rejected this argument, holding that under prevailing jurisprudence, a WDL issued during collection proceedings can no longer be treated as the CIR’s final decision on a disputed assessment. Since the Request for Reconsideration remained unresolved, there was no appealable decision on the assessment over which the CTA could exercise jurisdiction, and the Court therefore lacked jurisdiction to review the correctness of the assessment and the FDDA. Nevertheless, the Court ruled that it had jurisdiction to determine the validity of the WDL as an “other matter” arising under the Tax Code. Considering that the taxpayer filed its Petition within the filing period granted, the petition was timely insofar as it questioned the validity of the WDL. Accordingly, the Court held that it had only partial jurisdiction over the case, allowing review of the WDL while dismissing the challenge to the assessment for lack of jurisdiction (The Greenbelt Madison Condominium Association, Inc. v. CIR, CTA Case No. 10789, November 26, 2025)

THE TAXPAYER CANNOT VALIDLY INVOKE THE EARLY CLOSURE OF THE CASHIER AND ALLEGED ADVICE OF COURT PERSONNEL TO FILE VIA COURIER  TO JUSTIFY LATE FILING; CTA CANNOT RELAX THE RULES TO ALLOW BOTH LATE PAYMENT OF DOCKET FEES AND LATE FILING OF THE PETITION; HENCE, THE CTA ACQUIRED NO JURISDICTION OVER THE CASE. The CTA has exclusive appellate jurisdiction over decisions and inactions of the CIR involving disputed assessments and other matters arising under the NIRC, including the validity of  WDL. A taxpayer may directly appeal a WDL to the CTA within 30 days from receipt thereof, as the issuance of a WDL may constitute an implied denial of the taxpayer’s protest. Applying these principles, the Court found that the taxpayer received the WDL on October 28, 2021 and therefore had until November 29, 2021 to file a petition for review. However, the Petition for Review was actually filed only on December 3, 2021, beyond the mandatory and jurisdictional 30-day period. The Court rejected the taxpayer’s claim that it had attempted to file the petition on November 29, 2021 but was prevented from doing so because the cashier had allegedly closed early and court personnel advised it to file through a private courier, ruling that these allegations were unsupported by evidence and, in any event, contradicted by court records showing that the Cash Division continued accepting payments until after 4:30 p.m. The Court likewise held that even assuming such advice had been given, it was not binding on the Court, and the doctrine allowing the late payment of docket fees under exceptional circumstances was inapplicable because the delay pertained not merely to the payment of docket fees but to the actual filing of the petition itself. Since the timely perfection of an appeal is mandatory and jurisdictional, the belated filing deprived the CTA of jurisdiction to entertain the case, warranting the dismissal of the petition. (Helicon Technology Corporation v.  CIR, CTA Case No. 10694, December 29, 2025)

THE RECKONING PERIOD FOR FILING AN APPEAL WITH THE CTA EN BANC BEGINS FROM THE OSG’S RECEIPT OF THE DECISION, NOT FROM THE BIR’S RECEIPT THEREOF. A party adversely affected by a decision or resolution of the CTA Division on a motion for reconsideration or new trial must file a petition for review with the CTA En Banc within 15 days from receipt thereof, unless a timely motion for extension is filed before the expiration of the reglementary period. The period to appeal in cases involving the government is reckoned from the date the Office of the Solicitor General (OSG), as the government’s principal counsel, receives the assailed decision or resolution, and not from receipt by the deputized government lawyer, who merely acts as the OSG’s representative under its supervision and control. Applying these principles, the Court found that while the BIR’s deputized counsel received the CTA Division’s Resolution on October 11, 2024, the OSG had actually received it earlier on October 9, 2024. Thus, the 15-day period to file a petition for review or a motion for extension expired on October 24, 2024. Since the CIR filed the Petition for Review only on October 28, 2024, without having sought a timely extension, the appeal was filed beyond the mandatory and jurisdictional period. Consequently, the CTA Division’s Resolution had already become final and executory by operation of law, leaving the CTA En Banc with no jurisdiction to entertain the belated appeal [CIR v. Berong Nickel Corporation, CTA EB No. 3017 (CTA Case No. 10319), December 17, 2025; see also CIR v. Misnet Education, Inc., CTA EB No. 2825 (CTA Case No. 9941), November 18, 2025]

AN ELECTRIC COOPERATIVE MUST ESTABLISH THAT IT IS A NON-STOCK, NON-PROFIT ENTITY DULY REGISTERED WITH THE NEA BEFORE IT MAY VALIDLY INVOKE THE INCOME TAX EXEMPTION. Electric cooperatives registered with the National Electrification Administration (NEA) are granted a permanent exemption from income tax, and despite the temporary withdrawal of tax incentives The Court emphasized that tax exemptions are construed strictly against the taxpayer, who bears the burden of proving entitlement thereto. Applying these principles, the Court held that although the taxpayer claimed to be permanently exempt from income tax as an electric cooperative, it failed to establish that it was a non-stock, non-profit electric cooperative duly registered with the NEA. The document purportedly proving its NEA registration was not formally admitted in evidence, and the BIR specifically denied the taxpayer’s allegation of NEA registration in its Answer. In the absence of competent and admitted evidence establishing the taxpayer’s qualification for the exemption, the Court ruled that the taxpayer could not invoke the tax exemption, thereby sustaining the deficiency income tax assessment, including the corresponding surcharge and interest [Bukidnon II Electric Cooperative, Inc. (BUSECO) v. CIR, CTA Case No. 10930, December 5, 2025]

TO BE DEDUCTIBLE, TAXPAYER MUST PROVE THAT SALARIES AND WAGES WERE SUBJECTED TO WTC; TAXPAYER MUST PROVE LINK TO EXPENSES; AFS MUST BE PRESENTED AND MUST TRACE THE DISALLOWED AMOUNT. Under the Rules of Evidence, entries in official records are prima facie evidence of the facts stated therein, although the taxpayers still bear the burden of proving entitlement to deductions or non-liability for assessed taxes with competent evidence. In this case, the Court upheld the disallowance in Salaries and Wages representing payments to contractors and subcontractors for failure to establish that these were properly subjected to Withholding Tax on Compensation (WTC) noting that while the taxpayer invoked the Monthly Alphalist of Payees (MAP) attached to its Expanded Withholding Tax (EWT) returns and argued that these showed compliance with 2% EWT on payments, the Court found that such documents only proved EWT compliance and did not automatically establish that the subject salaries and wages were duly subjected to WTC or properly linked to the disallowed expenses. The Court further ruled that the taxpayer’s attempt to rely on its Audited Financial Statements to show that the payments formed part of “Direct Labor” under Cost of Services could not be given credence, as the AFS was not admitted in evidence due to failure to present the original documents for comparison, and even if considered, the figures therein did not specifically identify or sufficiently trace the payments to the disallowed amount. Accordingly, the Court sustained the BIR’s disallowance for lack of competent and specific proof that the contested salaries and wages were properly subjected to withholding tax requirements. [IBMS Technology Phils. Corporation v. CIR, CTA EB No. 2907 (CTA Case No. 9970), November 12, 2025]

REVENUE ISSUANCES

REVENUE MEMORANDUM CIRCULAR NO. 72-2026 

Under the tax authority’s power to streamline administrative procedures, the requirement to secure a prior confirmatory tax ruling for qualified nominee transfers of proprietary club shares is completely removed, moving instead to a post-audit verification system to improve the ease of doing business. 

Covered Issuance Circular clarifying the tax-exempt status of corporate nominee transfers of proprietary club shares and dispensing with advance regulatory approvals.

Transfer is exempt from:
• Capital Gains Tax (CGT)
• Documentary Stamp Tax (DST)
• Donor’s Tax
Scope of Exemption and Conditions All transfers of proprietary club shares from an outgoing corporate nominee/trustee to an incoming nominee/trustee where the legal title changes but the underlying corporation retains absolute beneficial ownership, solely to comply with club rules requiring registration under a natural person.

Conditions:
1. The corporation remains the beneficial owner.
2. The transfer is documented by a Declaration of Trust or Trust Agreement.
3. The share is recorded in the corporate books.
4. The transfer is without monetary or non-monetary consideration, directly or indirectly, in favor of the outgoing or incoming nominee.
Activities Allowed / Conditions Taxpayers may bypass advance confirmatory rulings and proceed directly to the appropriate Revenue District Office (RDO) for the processing of the electronic Certificate Authorizing Registration (eCAR).

To qualify, the proprietary club share must be recorded as a corporate asset, a valid Declaration of Trust or Trust Agreement must be executed, and no monetary or non-monetary consideration may be exchanged between the outgoing and incoming nominees.
Duration / Resolution Effective immediately upon issuance on June 30, 2026.

All pending requests for confirmatory rulings previously submitted to the BIR will no longer be acted upon, and compliance for all covered transactions will be verified solely through mandatory post-audit checks.
Pending Applications All applications currently pending before the BIR shall no longer be acted upon.

Applicants may proceed directly to the Revenue District Office (RDO) having jurisdiction over the transaction for the processing of the electronic Certificate Authorizing Registration (eCAR).

BIR DEADLINES FROM JULY 6, 2026 TO JULY 12, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
July 8, 2026 SUBMISSION – All Transcript Sheets of Official Register Books (ORBs) used by Dealers/Manufacturers/Toll Manufacturers/Assemblers/Importers of Alcohol Products, Tobacco Products, Petroleum Products, Non-Essential Goods, Sweetened Beverage Products, Mineral Products, and Automobiles. Month of June 2026
e-SUBMISSION – Monthly e-Sales Report for all taxpayers using CRM/POS and/or other similar business machines whose last digit of the 9-digit TIN is an even number. Month of June 2026
July 10, 2026 SUBMISSION – List of Buyers of Sugar together with a copy of the Certificate of Advance Payment of VAT made by each buyer appearing in the list by a Sugar Cooperative. Month of June 2026
SUBMISSION – Information Return on Releases of Refined Sugar by the Proprietor or Operator of a Sugar Refinery or Mill. Month of June 2026
e-SUBMISSION – Monthly e-Sales Report for all taxpayers using CRM/POS and/or other similar business machines whose last digit of the 9-digit TIN is an odd number. Month of June 2026
eFILING & PAYMENT/REMITTANCE (Online/Manual) – BIR Form 2200-M (Excise Tax Return for the Amount of Excise Taxes Collected from Payments Made to Sellers of Metallic Minerals). Month of June 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation). Non-eFPS Filers. Month of June 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 2200-C (Excise Tax Return for Cosmetic Procedures) together with the Monthly Summary of Cosmetic Procedures Performed. Month of June 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or BIR Form 1600-PT (Monthly Remittance Return of Other Percentage Taxes Withheld), together with the Monthly Alphalist of Payees (MAP), for eFPS and Non-eFPS Filers. Month of June 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1606 (Withholding Tax Remittance Return for Onerous Transfer of Real Property Other Than Capital Asset, Including Taxable and Exempt Transactions). Month of June 2026
e-FILING & e-PAYMENT/REMITTANCE – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or BIR Form 1600-PT (Other Percentage Taxes Withheld), and BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) for National Government Agencies (NGAs). Month of June 2026
July 11, 2026 e-FILING – BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – eFPS Filers under Group E. Month of June 2026
July 12, 2026 e-FILING – BIR Form 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – eFPS Filers under Group E. Month of December 2025

Court of Tax Appeals Decisions Articles

Security and Exchange Commission Articles

Bureau of Internal Revenue Articles