Competence. Integrity. Commitment.

COURT OF TAX APPEALS (CTA) DECISIONS

LOA SERVED 860 DAYS AFTER ISSUANCE AND THE APPLICABLE 180-DAY AUDIT PERIOD HAD ALREADY EXPIRED RENDERS THE ASSESSMENT VOID. A revenue officer may examine a taxpayer and recommend a deficiency assessment only pursuant to a valid Letter of Authority (LOA), while the regulations require the LOA to be served within 30 days from issuance, otherwise it becomes null and void unless revalidated; consistent with this, the Supreme Court held that an unserved LOA that remains outstanding beyond 30 days becomes wholly unenforceable absent revalidation. Here, the LOA was served 860 days after issuance, with no showing that it had been revalidated. The Court therefore found that the LOA had already become void and unenforceable when served. Although the BIR regulations subsequently deleted the 30-day service requirement, and clarified that an LOA served beyond 30 days may still be considered valid, the Circular expressly limits this to cases where the applicable 180-day/240-day period for completion of the audit has not yet expired. That saving provision did not benefit the BIR because, when the LOA was eventually served, the 180-day audit period had already expired. The taxpayer’s failure to update its address and the BIR’s alleged difficulty in locating it likewise did not preserve the validity of the already expired LOA. Since the audit and examination were therefore conducted without a valid and enforceable LOA, the resulting deficiency assessment was void and ineffectual. (Floorcompany, Inc., v. Commissioner of Internal Revenue (“CIR”), CTA Case No. 11050, April 29, 2026)

LOA IS REQUIRED FOR AN ASSESSMENT OUTSIDE THE COVERED PERIOD; BIR CANNOT VALIDLY ARGUE THAT NEW LOA IS UNNECESSIARY FOR VAT ASSESSMENT DUE TO UTILIZATION OF EXCESS INPUT VAT. An RO may examine a taxpayer and perform assessment functions only pursuant to a valid LOA issued by the CIR or a duly authorized RD, and the LOA must identify the taxable period covered because it defines the extent of the RO’s authority and protects the taxpayer’s right to due process. The Supreme Court emphasized that an assessment made pursuant to an invalid LOA, or beyond the authority granted therein, is void and ineffectual; the RO cannot assess a taxpayer for a taxable period not covered by the LOA, since the RO must obtain another LOA if the BIR intends to expand the audit period. A LOA is required even when the BIR does not physically examine the taxpayer’s books, because the requirement depends on whether the taxpayer is subjected to an examination or audit, not on the manner by which the BIR obtains or verifies the information used in the assessment. Here, the BIR issued LOA authorizing the examination of books of accounts and other accounting records for all internal revenue taxes. Despite this limited authority, the BIR issued an Assessment Letter and a Denial of Protest for alleged deficiency VAT for the quarter ended June 30, 2021, a period clearly outside the coverage of the LOAs. The CIR argued that a new LOA was unnecessary because the deficiency VAT assessment resulted from utilization of excess input taxes rather than from an examination of books and accounting records. The Court rejected this argument, explaining that the BIR cannot avoid the LOA requirement simply by relying on information or systems that do not involve a physical examination of the taxpayer’s books; once the taxpayer is subjected to an examination or audit, the statutory requirement for prior authorization applies. Thus, the BIR should have issued another LOA specifically authorizing the examination and assessment for the quarter ended June 30, 2021. [CIR v. PMFTC, Inc., CTA EB No. 3009 (CTA Case No. 10714), April 13, 2026]

A TAXPAYER MAY BE TREATED AS CBL ONLY UPON PROOF OF THE REQUIRED BIR TAGGING AND PUBLICATION; THUS, WHERE THE BIR SHOWED ONLY CERTIFICATIONS OF UNSUCCESSFUL LOCATION EFFORTS BUT FAILED TO PROVE ACTUAL CBL DESIGNATION AND PUBLICATION, THE LOA REMAINED SUBJECT TO THE 30-DAY REVALIDATION AND 180-DAY AUDIT PERIODS, RENDERING IT AND THE RESULTING ASSESSMENTS VOID. A taxpayer may be given “Cannot Be Located” (CBL) status only after the BIR makes efforts to locate the taxpayer and obtains certifications from at least two specified offices or organizations that the taxpayer does not appear in their records; the taxpayer’s CBL status must then be reflected in the BIR records and submitted for publication on the BIR website and in at least two newspapers of general circulation. Here, although the BIR obtained certifications from the Makati City Business Permits Office and Barangays San Isidro and Bangkal indicating that taxpayer was not registered in their respective records, these certifications merely established efforts to locate taxpayer and did not prove that taxpayer was actually tagged as CBL in the BIR’s records. The only evidence offered was a Memorandum recommending that taxpayer be included in the CBL list and that the matter be referred for publication; the BIR presented no evidence that the CBL designation was actually made, or that taxpayer’s name was submitted and published on the BIR website and in at least two newspapers. The Court could not consider evidence that had not been formally offered. Consequently, the BIR failed to establish the factual predicate for exempting the LOA from the 30-day revalidation requirement and the 180-day audit-completion period. The LOA was therefore void, and because the assessments for taxable year 2017 were issued pursuant to an invalid LOA, they were likewise unenforceable and had to be cancelled and set aside. (Floorcompany, Inc., v. CIR, CTA Case No. 11050, April 29, 2026)

A WDL IS VALID ONLY WHEN THE TAX LIABILITY IS FINAL AND EXECUTORY; THUS, WDLS ARE PREMATURE BECAUSE THE TAXPAYER’S MR OF THE FDDA REMAINED PENDING; TAXPAYER CANNOT VALIDLY CHALLENGE THE ASSESSMENT FOR LACK OF A FINAL CIR DECISION. The Court of Tax Appeals has jurisdiction over “other matters” arising under the NIRC, including the validity of a Warrant of Distraint and/or Levy (“WDL”), but the BIR may resort to summary collection remedies only when the taxpayer’s liability has become delinquent, final, and executory, whether arising from self-assessed taxes or a final deficiency assessment. Here, the taxpayer received the second WDL and filed its Petition within the 30-day period; the first WDL was refused because its Motion for Reconsideration (“MR”) of the Final Decision on Disputed Assessment (“FDDA”) was still pending. The Court held that both WDLs were premature because the deficiency assessment had not become final and executory: the taxpayer timely protested the FLD/FAN, submitted supporting documents, and elevated the denial of its protest through an MR to the CIR. Collection through a WDL presupposes a final and executory liability; thus, the BIR could not enforce the assessment while the taxpayer’s administrative remedy remained pending. However, the Court could not rule on the merits of the deficiency assessment because, after denial of a protest by an authorized representative of the CIR, the taxpayer may either appeal to the CTA within 30 days or seek reconsideration from the CIR, and these remedies are mutually exclusive. Having chosen the latter, the taxpayer had to await the CIR’s action on its MR before seeking judicial review. Moreover, only one 180-day period is available for the CIR or his authorized representative to act, reckoned from submission of the supporting documents; the subsequent MR did not create a new 180-day period. Accordingly, the Court cancelled and set aside the WDLs and ordered the BIR to cease collection until the assessment becomes final and executory, but dismissed the Petition insofar as it sought review of the deficiency assessment, there being no final CIR decision on the pending MR. (Ivonclar Vivadent, Inc. v. CIR, CTA Case No. 11253, April 20, 2026)

TAXPAYER SHOULD APPEAL THE FDDA SIGNED BY THE CIR HIMSELF TO THE CTA; MOTION FOR RECONSIDERATION WILL NOT TOLL THE PERIOD. The CTA has jurisdiction over disputed assessments only when the taxpayer timely protests the assessment and timely appeals the CIR’s final decision to the CTA, while “other matters  include challenges to BIR collection remedies such as WDL and Warrant of Garnishment (“WOG”). Here, the CTA En Banc ruled that the original Petition for Review was only partly within the CTA’s jurisdiction. The FDDA signed by the CIR (Dulay) constituted the CIR’s final decision on taxpayer’s protest and the taxpayer should have appealed the FDDA to the CTA. Instead, taxpayer filed a letter-reply/motion for reconsideration with the CIR, which did not suspend or extend the period to appeal. Consequently, the assessments became final, executory, and demandable, depriving the CTA of jurisdiction to review their validity. The Court nevertheless recognized jurisdiction over the WOGs as “other matters.” The WDL, however, was challenged beyond the 30-day period; hence, the CTA had no jurisdiction over the WDL. In contrast, the WOGs were received within 30-day period deadline, giving the CTA jurisdiction over them. On the merits, the Court sustained the WOGs because taxpayer could not use a challenge to the collection remedy to indirectly reopen an assessment that had already become final. Taxpayer’s separate argument that the first LOA was invalid because it was served more than 30 days after issuance without revalidation was likewise rejected. The taxpayer did not object to the alleged defect when the LOA was served, nor did it raise the issue in its protest or original CTA petition; it surfaced only during cross-examination and was formally raised much later in a memorandum. Because the first LOA was valid, taxpayer’s challenge to the waivers extending the period to assess also failed. Accordingly, the CTA En Banc partially dismissed the Petition for lack of jurisdiction insofar as it sought nullification of the assessment and WDL, but denied it on the merits [Pentagon Gas Corporation v. CIR, CTA EB No. 3089 (CTA Case No. 10868), April 20, 2026]

15-DAY PERIOD TO FILE APPEAL TO CTA EN BANC IS RECKONED FROM DATE OF RECEIPT OF OSG, NOT BY THE BIR A Petition for Review to the CTA En Banc must be filed within 15 days from receipt of the Division’s resolution, with extension available only upon proper motion. Where the OSG is the government’s principal counsel, receipt by the OSG controls the appeal period, even if the resolution is received later by deputized BIR counsel. Thus, receipt by the OSG started the 15-day period, and petition filed by the BIR outside the 15-days period is dismissible. [CIR v. Sumitomo Corporation – Manila Branch, CTA EB No. 2998 (CTA Case No. 10412, April 7, 2026]

IN A DE NOVO CTA PROCEEDING, DOCUMENTS MERELY SUBMITTED DURING THE BIR AUDIT HAVE NO EVIDENTIARY VALUE ABSENT FORMAL OFFER; THUS, WHERE THE TAXPAYER FAILED TO FORMALLY OFFER THE ORS/SIS SUPPORTING ITS INPUT VAT CLAIM, THE CTA SUSTAINED THE DISALLOWANCE FOR FAILURE TO PROVE THE ASSESSMENT ERRONEOUS. The CTA is a court of record where cases are litigated de novo, requiring taxpayers to formally offer competent evidence to substantiate their claims; likewise, under the rules on evidence, allegations are not evidence and the burden of proof rests on the party asserting the claim. Here, the CIR disallowed input VAT because the supporting ORs and SIs were either missing or issued by non-VAT suppliers, and although taxpayer claimed that the documents were submitted during the BIR audit and that the amounts were instead treated as expenses/COS, it failed to formally offer the alleged ORs and SIs before the CTA. Since documents merely submitted to the BIR have no evidentiary value absent formal offer in court, taxpayer failed to prove that the assessment was erroneous; thus, the CTA sustained the disallowance of the unsupported input VAT (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

INPUT VAT IS CREDITABLE ONLY UPON COMPLIANCE WITH PRESCRIBED INVOICING REQUIREMENTS. A taxpayer claiming input VAT must establish that the supporting VAT invoices/official receipts comply with the prescribed invoicing requirements, including the nature of payment/service, TIN, address, VAT breakdown, and other required details; input tax on local purchases of goods is creditable upon consummation of the sale, not upon payment. Here, the CTA found that taxpayer’s supporting invoices/receipts failed to comply with these requirements, and taxpayer could not shift the burden to its suppliers because it was incumbent upon it to exercise due diligence in ensuring that its documents were compliant; its cash-flow records also could not cure the absence of the required information. However, the Court cancelled the disallowance because the records showed that the taxpayer’s TIN was actually reflected in the supporting document. The Court likewise upheld the disallowance in “out-of-period” input VAT because the purchases involved goods acquired in a different year, for which the input tax became creditable upon consummation, rather than upon payment. Accordingly, the CTA sustained the invoicing-related disallowance (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

TAXPAYER MUST CLEARLY RECONCILE ALLEGATION OF OVERCLAIMED INPUT VAT BY SUBMITTING RELEVANT AND VERIFIABLE SOURCE DOCUMENTS . The CTA is a court of record conducting trials de novo, and the taxpayer bears the burden of proving that an assessment is erroneous; assessments are prima facie presumed correct and made in good faith. Here, the BIR determined an overclaimed input VAT by comparing the Global Sources of Input Tax (GSIT) reflected in taxpayer’s AFS/AITR with the sources of input tax reported in its VAT returns. Although taxpayer presented reconciliations and claimed that its importation input VAT was supported by 664 pages of importation documents and that differences arose from the use of landed cost versus amounts recorded in the AFS/AITR, it failed to present the underlying importation documents and other supporting records necessary to verify these explanations and failed to adequately explain the variances in its reconciliations. Since the reconciliations, without the relevant source documents, could not be independently verified, and evidence not formally offered cannot be considered, taxpayer failed to discharge its burden of proving the assessment erroneous; thus, the CTA sustained the disallowance for overclaimed input tax. (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

REVENUE ISSUANCES

Pursuant to Revenue Memorandum Circular (RMC) No. 97-2026 and under the National Internal Revenue Code (NIRC) of 1997, as amended, allowable system loss charges billed by electric distribution utilities to consumers are excluded from the 12% Value-Added Tax (VAT) computation to directly reduce end-user energy costs.

Date of Issuance September 14, 2026
Effectivity Immediately; applied prospectively from its effectivity and from the effectivity of ERC Resolution No. 26, Series of 2026, pursuant to Sections 12, 14, and 17 thereof
Nature of System Loss Charge The allowable System Loss Charge, within the cap approved by the ERC, is treated as a government-mandated pass-through cost
VAT Treatment The allowable System Loss Charge is excluded from Gross Sales for VAT purposes and is therefore not subject to output VAT
Creditable Withholding VAT (CWVAT) Since the allowable System Loss Charge is excluded from VATable gross sales, it is likewise not subject to CWVAT
Income Tax Treatment Unchanged. The VAT exclusion does not extend to income tax or the corresponding creditable withholding tax
Separate Identification The allowable System Loss Charge must be separately identified in the billing statement, invoice, or similar document
ERC Compliance Taxpayers must comply with applicable ERC rules and regulations governing the allowable System Loss Charge
Tax Compliance Taxpayers must comply with the relevant invoicing and gross sales provisions of the Tax Code and its implementing rules and regulations
Billing and Accounting Affected taxpayers must ensure proper billing, accounting, reporting, and disclosure of the System Loss Charge
Covered taxpayers –   must separately identify and properly account for the allowable System Loss Charge
  • Generation Companies (GenCos)
  • National Grid Corporation of the Philippines (NGCP)
  • Distribution Utilities (DUs)
Electric Cooperatives Covered taxpayer; must comply with the applicable ERC and tax requirements
Other Affected Taxpayers Must likewise ensure proper billing, accounting, reporting, and separate identification of the allowable System Loss Charge
Key Limitation The exclusion is for VAT purposes only; it does not mean that the System Loss Charge is excluded from taxable income or from income-tax withholding

BIR DEADLINES FROM SEPTEMBER 21, 2026 TO SEPTEMBER 27, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE  FILING/SUBMISSION
September 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayer. Non-eFPS Filers – Fiscal Quarter ending August 31, 2026
Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products – Fiscal Quarter ending August 31, 2026 
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550Q (Quarterly Value-Added Tax Return). eFPS & Non-eFPS Filers – Fiscal Quarter ending August 31, 2026
BIR Form 2551Q (Quarterly Percentage Tax Return) – eFPS & Non-eFPS Filers. Fiscal Quarter ending August 31, 2026
BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider). Fiscal Quarter ending August 31, 2026 

COURT OF TAX APPEALS (CTA) DECISIONS

REASSIGNMENT OF AUDIT TO ANOTHER EXAMINER PRIOR TO THE PAN-STAGE REQUIRES A NEW LETTER OF AUTHORITY (LOA); MEMORANDUM OF ASSESSMENT ISSUED BY A REVENUE DISTRICT OFFICER IS NOT SUFFICIENT. The Tax Code requires that the examination of a taxpayer’s books be conducted only by revenue officers specifically authorized under a valid LOA; an LOA is a special authority granted to particular revenue officers, not a general authority that may be used by any BIR officer. The Supreme Court held that the reassignment or substitution of revenue officers without a new or amended LOA violates the taxpayer’s right to due process and usurps the statutory authority of the CIR or his duly authorized representative. Any reassignment or transfer of a case to other revenue officers requires the issuance of a new LOA. Here, the examiners, who conducted the examination and recommended the issuance of the PAN, were not authorized under a valid LOA; their supposed authority rested only on Memorandum of Assignment issued by the Revenue District Officer, which could not substitute for an LOA. The subsequent LOA likewise did not cure the defect because it was issued long after the PAN. Thus, the PAN issued based on the unauthorized examination was void for lack of valid authority and violation of due process. [(Ammex I-Support Corporation v. Commissioner of Internal Revenue (CIR), CTA Case No. 11192, April 17, 2026)]

PHRASES IN THE ASSESSMENT NOTICE “YOU ARE REQUESTED TO PAY” OR “IF YOU ARE AMENABLE” DO NOT NEGATE DEMAND TO PAY; ASSESSMENT REMAINS VALID. A valid assessment must constitute a written notice and demand for a definite tax liability and must indicate a clear due date for payment, because the demand signals when penalties and interest accrue and informs the taxpayer of its remedies. Applying these principles, the CTA held that the FLD and FAN contained an unequivocal demand despite using the phrase “you are requested to pay,” since a demand may properly take the form of a request for payment; here, the FAN stated a definite amount and expressly provided June 30, 2022 as the payment deadline. Moreover, the title “Formal Letter of Demand” itself indicated the CIR’s intention to demand payment, and the phrases “you are requested to pay” and “if you are amenable” did not negate the demand. Thus, the assessment notices validly demanded payment of the deficiency taxes. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

3-YEAR PRESCRIPTIVE PERIOD WAS EXTENDED BY 420 DAYS DUE TO COVID-19  PANDEMIC. Internal revenue taxes must generally be assessed within 3 years from the last day prescribed for filing the return or the actual filing date, whichever is later, subject to the suspension provisions; during the COVID-19 pandemic, various legislations/regulations validly suspended the running of the prescriptive period during the specified ECQ/MECQ period. Applying these rules, although the original 3-year periods for 2018 income tax, VAT, WTC, and EWT liabilities had generally expired before the FLD was issued, the CTA held that the applicable COVID-19 suspensions validly extended the prescriptive periods by 420 days; consequently, the BIR’s right to assess remained timely for all the deficiency taxes involved, before the FLD was issued and received (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

TAXPAYER WAS NOT LIABLE FOR 30% RCIT ON PAGCOR’S USE OF THE CORPORATE OFFICES BECAUSE THE LEASE EXPRESSLY PROVIDED THAT SUCH USE WAS WITHOUT ADDITIONAL RENT. Income derived from taxable activities is subject to regular corporate income tax, while the tax treatment of PAGCOR-related income depends on the nature of the income actually earned; the CIR treated rental income from PAGCOR as subject to 30% RCIT on the theory that the reported rent supposedly covered both the gaming area and the corporate offices, with only the former being connected to exempt gaming activities. The CTA, however, found no factual or contractual basis for imputing rental income to the corporate offices because the Lease Agreement expressly provided that the rent pertained to the gaming premises, and that, upon payment of the stipulated rent, PAGCOR could continue using the Office Premises “without any further charge or payment therefor.” Thus, the taxpayer actually derived rental income only from the gaming premises and did not earn any additional rental income from PAGCOR’s use of the corporate offices. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

DISALLOWANCE OF MCIT CARRY-OVER WITHOUT EXPLANATION IS VOID. An assessment is void unless the taxpayer is informed in writing of the factual and legal bases thereof, as this is a substantive and mandatory requirement. Here, the FLD deducted the MCIT and income tax carried over to 2019 from the taxpayer’s total tax credits/payments, effectively disallowing these amounts, but failed to explain the factual and legal basis for their disallowance; thus, the taxpayer was not adequately informed of why these tax credits were rejected, rendering the corresponding assessment items void. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

INTEREST INCOME FROM A LOAN BY REAL ESTATE BUSINESS IS NOT SUBJECT TO VAT; BIR MUST PROVE INTEREST INCOME’S CONNECTION TO THE MAIN BUSINESS. VAT applies to services rendered in the course of trade or business, including transactions incidental thereto, but a transaction may be considered incidental only when there is an intimate connection between it and the taxpayer’s main business activity; moreover, interest income from loans is generally subject to VAT when earned by a lending investor, dealer in securities, financial institution, or an entity performing similar financing activities. Here, the taxpayer was principally engaged in the purchase, development, leasing, management, and sale of real and personal properties, and was not a lending investor, dealer in securities, or financial institution; although the interest income from its loan could potentially be VATable if the loan transaction were incidental to its business, the BIR failed to establish any clear relation or intimate connection between the loan and taxpayer’s main real estate business, merely stating that the income was not among its exempt activities. Thus, absent proof that the loan was incidental to petitioner’s VATable business, the interest income was not subject to VAT. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

PROCEEDS FROM DISPOSAL OF PROPERTY BY PAGCOR CONTRACTEE ENGAGED IN REAL ESTATE IS SUBJECT TO VAT. The tax exemption extended to PAGCOR contractees applies only to earnings derived from casino/gaming operations conducted under the PAGCOR franchise, while income from other activities remains subject to tax; likewise, transactions incidental to a taxpayer’s main business may be subject to VAT under the NIRC. Here, although the  proceeds from the disposal of property and equipment involved equipment previously used in casino operations, and the sale itself did not constitute earnings derived from PAGCOR’s gaming operations the disposal was considered a transaction incidental to petitioner’s business of purchasing, leasing, and selling real and personal properties, making the proceeds subject to VAT. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

RENTAL INCOME FROM PAGCOR’S USE OF CORPORATE OFFICE IS NOT SUBJECT TO VAT IF LEASE AGREEMENT PROVIDES THAT PAGCOR WILL NOT PAY RENT FOR THE USE THEREOF. Under the PAGCOR Charter and the Lease Agreement between the taxpayer and PAGCOR, only actual or constructively received rent income may be subjected to VAT. Here, rental income was based on the assumption that a portion of PAGCOR’s rent payments pertained to its use of the corporate offices, allegedly outside the exempt gaming activities; however, the lease agreement expressly provided that PAGCOR would incur no charge or further payment for its use of the Office Premises, resulting in no actual or constructive receipt of rent income by petitioner. Thus, there was no VATable rental income arising from PAGCOR’s use of the corporate offices, and the VAT assessment was cancelled. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

DISALLOWANCE OF INPUT VAT CARRY-OVER WITHOUT EXPLANATION IS VOID. An assessment or disallowance is void when the taxpayer is not informed in writing of the factual and legal bases thereof. Here, the BIR deducted input tax carried over to 2019 from the computed VAT due, effectively disallowing the amount and increasing the basic deficiency VAT, but neither the FLD nor the Details of Discrepancies stated the factual or legal basis for such disallowance. Accordingly, the disallowance of input tax carry-over was void, and after allowing the input tax credits, the taxpayer’s credits were sufficient to cover its output VAT for CY 2018, resulting in no basic deficiency VAT liability. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR CANNOT VALIDLY ASSESS TAXPAYER FOR FAILURE TO REFUND EXCESS WITHHOLDING TAX TO EMPLOYEES; BIR’S ASSESSMENT BASED ON MERE COMPARISON OF ALPHALIST AND AFS WITHOUT EXAMINING THE NATURE OF THE ACCOUNTS IS VOID. The penalty imposed on an employer or withholding agent applies when it fails or refuses to refund excess withholding tax to an employee, and does not provide a basis for assessing additional withholding tax merely from discrepancies in compensation expenses. Here, the BIR assessed deficiency WTC based on a discrepancy between compensation expenses reflected in taxpayer’s AFS and amounts reported in its Alphalist/BIR Form 1601-C, but its reliance on Section 252 was misplaced because that provision concerns the non-refund of excess withholding tax, whereas the assessment sought to impose additional withholding tax. The assessment also lacked sufficient factual basis because the amount taken from the Alphalist included non-taxable compensation, yet the BIR simply compared this amount with selected salary and payroll-related accounts in the AFS and treated the entire difference as compensation subject to WTC without examining the nature and taxability of the individual accounts. Thus, the BIR failed to establish both the legal authority and factual basis for the assessment, rendering the deficiency WTC assessment devoid of merit and subject to cancellation. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S EWT ASSESSMENT BASED ON MERE COMPARISON OF BOOKS/AFS AND WITHHOLDING TAX RETURN IS VOID; BIR MUST IDENTIFY THE SPECIFIC TRANSACTIONS AND NATURE OF INCOME PAYMENTS. An assessment must inform the taxpayer in writing of the specific factual and legal bases upon which it is made; otherwise, the assessment is void for failure to satisfy the statutory and constitutional requirements of due process. Here, the BIR assessed deficiency EWT based on discrepancies between the taxpayer’s expenses per books/AFS and its BIR Form 1601-E returns, classifying the alleged discrepancies as purchases of goods, purchases of services, rent, and professional fees and applying different EWT rates. However, the BIR merely invoked Section 57(B) of the NIRC and Section 2.57.2 of RR No. 2-98 without identifying the specific transactions covered, the nature of the income payments, the identities or classes of payees, or the particular subsection of Section 2.57.2 that prescribed the applicable withholding rate. This was insufficient because Section 2.57.2 contains several subsections covering different types of income payments and payees, each with corresponding EWT rates; thus, a general reference to the provision did not enable the taxpayer to determine which transactions were allegedly subject to EWT, why they were taxable, and how the rates were applied. Accordingly, the deficiency EWT assessment was declared void for failure to sufficiently state its factual and legal bases. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S DST ASSESSMENT (1) ON LOAN BASED ON YEAR-END BALANCE (2) PRIOR YEAR LEASE AND (3) RENT-FREE USE OF OFFICE IS VOID. DST is imposed on taxable debt instruments and certain lease agreements; however, a tax assessment must be supported by actual facts and transactions, rather than presumptions. Here, the BIR assessed deficiency DST by treating the year-end balances of taxpayer’s “Amounts owed by/to related party” accounts as loans or advances subject to DST. The Court found this improper because the amounts represented year-end balances, and the corresponding accounts already had substantial beginning balances, indicating that the amounts could have arisen from transactions in prior years. The BIR failed to determine whether the balances represented new loans or advances actually made during the year and did not present supporting documents, such as instructional letters, memoranda, vouchers, or other evidence establishing the existence of taxable loan transactions. The Court stressed that assessments cannot rest on reasonable or logical presumptions but must be grounded on actual facts. The DST assessments on the parking-area lease income and rental expense involving, respectively, were likewise improper because the relevant lease agreements were executed in prior years. Finally, the DST on alleged rent income was unfounded because the taxpayer did not receive any additional rent for PAGCOR’s use of the Office Premises, while the PAGCOR Gaming Premises lease was executed in prior year and was exempt from DST under the PAGCOR Charter. Accordingly, the BIR failed to establish that the assessed transactions were taxable DST transactions occurring within the audit period, and the entire deficiency DST assessment was cancelled. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S FAILURE TO ADDRESS TAXPAYER’S ARGUMENTS IN THE PAN RENDERS THE ASSESSMENT VOID. The Tax Code requires that the taxpayer be informed in writing of the factual and legal bases of the assessment and that its defenses and supporting evidence be meaningfully considered; otherwise, the assessment is void for violation of administrative due process. The Supreme Court held that due process requires not merely an opportunity to be heard but also that the BIR actually consider and address the taxpayer’s explanations, with reasons stated for rejecting them. Here, the taxpayer filed a reply to the PAN, raising factual and legal arguments against the proposed assessment, but the subsequent FAN/ANs neither acknowledged nor addressed taxpayer’s arguments and were substantially identical to the PAN, except for the computation of interest. The subsequent protest against the FAN/ANs did not cure the defect because the denial of due process had already occurred at the assessment stage. Accordingly, the FAN/ANs were null and void, and the assessment and subsequent decision were cancelled and set aside. [(Ammex I-Support Corporation v. CIR, CTA Case No. 11192, April 17, 2026; Abraham Holdings, Inc.(Formerly Armadillo Holdings, Inc.) v. CIR, CTA Case No. 11088, June 8, 2026; Ozamiz City v. CIR, CTA Case No. 10828, June 18, 2026; CIR v. Marina Square Properties, Inc., CTA EB No. 3051, CTA Case No. 13049, May 21, 2026; Konica Minolta Marketing Services (Philippines) Inc., v. CIR,  CTA Case No. 10908, May 26, 2026; CIR v. United Graphic Printing Corporation, CTA Eb No. 3142, CTA Case No. 10610, May 26, 2026; CIR v. Serbiz Multi-Purpose Cooperative, CTA EB No. 3057, CTA Case No. 10369, May 28, 2026; CIR v. Justice Maria Lourdes P.A. Sereno, CTA EB No. 2996, CTA Case No. 10792, April 23, 2026; CIR v. Plastic Container Packaging Corporation, CTA EB No. 3039 (CTA Case No. 10095), April 22, 2026; CIR v. Neuftech Philippines, Inc., CTA EB No. 3012, CTA Case No. 10442, May 7, 2026)]

3-YEAR ASSESSMENT PERIOD APPLIES IF BIR FAILS TO PROVE FRAUDULENT INTENT. The extended prescriptive period applies only in cases of a false or fraudulent return with intent to evade tax or failure to file, while absent fraud or intentional falsity, the applicable period to collect an assessed tax is 3 years from the assessment. Here, the BIR failed to establish that taxpayer deliberately falsified her returns or intended to evade taxes; rather, she filed her AITRs, voluntarily paid income taxes, and reasonably relied on the BIR Form 2316 and tax withholdings of her employer, the Supreme Court, as statutory withholding agent. Thus, the alleged errors did not constitute fraud, making the extended prescriptive period inapplicable. (CIR v. Justice Maria Lourdes P.A. Sereno, CTA EB No. 2996, CTA Case No. 10792, April 23, 2026)

COOPERATIVE’S TAX EXEMPTION RETROACTS TO THE DATE OF ITS REGISTRATION. For cooperatives, while the law provides that tax exemption generally takes effect upon issuance of the Certificate of Tax Exemption, the initial issuance of such certificate is retroactive to the date the law took effect, provided that the cooperative was registered with the Cooperative Development Authority (CDA). Here, the taxpayer was registered with the CDA in 2009, and its Certificate of Tax Exemption issued in 2012 was its first certificate; hence, the certificate’s effectivity retroacted to 2009, making taxpayer exempt from income tax and VAT beginning taxable year 2009 despite the certificate being issued only in 2012. Thus, the taxpayer was not liable for the deficiency taxes assessed for TY 2009, CIR v. Serbiz Multi-Purpose Cooperative, CTA EB No. 3057, (CTA Case No. 10369) May 28, 2026)]

RECEIPT OF THE FORMAL LETTER OF DEMAND/FINAL ASSESSMENT NOTICE (FLD/FAN) PRIOR TO EXPIRATION OF 15-DAY PERIOD TO REPLY TO THE PAN RENDERS THE ASSESSMENT VOID. A taxpayer must be given 15 days from receipt of the PAN to submit a reply, and the BIR must wait for the taxpayer’s response or the lapse of the 15-day period before issuing the FLD/FAN; here, the taxpayer received the PAN on January 4, 2013, as shown by the notation on the PAN itself, giving it until January 21, 2013 to respond because the 15th day fell on a Saturday. However, the BIR issued the FAN on January 14, 2013, seven days before the expiration of the response period, thereby prematurely terminating respondent’s statutory opportunity to contest the PAN. The BIR’s unsupported claim that the PAN was served on December 28, 2012 was insufficient, as it presented no proof of service, while the PAN itself indicated receipt on January 4, 2013. The subsequent filing of a protest and administrative appeal did not cure the defect. [CIR v. Kuehne + Nagel, Inc., CTA EB No. 3024 (CTA Case No. 10216), April 15, 2026]

TAXPAYER CANNOT REFUND AN ERRONEOUSLY PAID IN A TAX ASSESSMENT CASE. SEE DISSENTING OPINION. A taxpayer seeking a refund or tax credit of erroneously or illegally collected taxes must first file a written administrative claim with the CIR, and both the administrative and judicial claims must be filed within two years from the date of payment; this two-year period is mandatory and jurisdictional. Here, the taxpayer paid tax during the reinvestigation of its TY 2009 assessment. Although the Court in Division subsequently found that the payments were made pursuant to a void assessment and ordered their refund, the Court En Banc held that the CTA had no jurisdiction to grant such relief. Moreover, with respect to all the payments, the taxpayer failed to file a written claim for refund or tax credit with the CIR within two years and did not even allege or pray for a refund in its Petition for Review. Accordingly, the En Banc modified the Division’s decision by deleting the refund/TCC while affirming that the assessments were void. Dissenting Opinion: The CTA has jurisdiction not only over disputed assessments and refund cases, but also over “other matters arising under the NIRC” or laws administered by the BIR. Moreover, it may resolve related issues necessary for the complete and orderly disposition of the case. Lastly, the period should be relaxed because of the peculiar circumstances of the case. Strict procedural rules should not be applied where they would allow the government to retain taxes it had no legal right to collect. [CIR v. Kuehne + Nagel, Inc., CTA EB No. 3024 (CTA Case No. 10216), April 15, 2026]

A SUBSEQUENT LOA IS VOID IF IT COVERS A PERIOD UNDER AN EARLIER LOA, WHICH HAS BEEN FULLY SETTLED. For income tax purposes, the examination and inspection of a taxpayer’s books shall be conducted only once in a taxable year, subject to limited exceptions, while the BIR regulations provide a “One LOA per Taxable Year” rule by generally allowing only one LOA for the same taxpayer, tax type, and period, except when a subsequent LOA is justified by circumstances such as the reassignment, retirement, or inability of the originally assigned revenue officers to continue the investigation. Applying these rules, the third LOA was infirm because it substantially overlapped with the period already examined under the First and Second LOAs. Moreover, none of the recognized exceptions justified the third LOA: even the alleged fraud, irregularity, or mistake had already been investigated under the Second LOA, and the alleged undeclared gain from the sale of land and improvements – which became the basis for the ad valorem penalties under the third LOA – had already been considered and ultimately abandoned in the FDDA issued under the Second LOA. More importantly, the assessments under the second LOA had already become final and were fully settled when taxpayer voluntarily paid the assessed deficiency taxes. thereby closing the audit and assessment process. Thus, the Third LOA improperly attempted to reopen and reassess matters that had already been examined, resolved, abandoned, and paid, in violation of the “One LOA per Taxable Year” rule and the principles of finality of assessments and orderly tax administration; consequently, the third LOA was void, and all assessments issued pursuant thereto were likewise void and without legal effect. [Orica Nitrates Philippines, Inc. v. CIR, CTA Case No. 10946, (April 15, 2026)]

BIR’S FAILURE TO INDICATE THE DUE DATE IN THE FAN RENDERS THE ASSESSMENT VOID. The Tax Code mandates that the taxpayer be informed in writing of the facts and law upon which an assessment is based, and jurisprudence establishes that a valid formal assessment must contain not only the computation of the tax liability but also a definite demand for payment within a prescribed period. A FAN that fails to state a definite due date is not a valid assessment because the due date determines when the taxpayer must pay, when penalties and interest may accrue, and allows the taxpayer to determine and exercise the proper remedies. Here, the FLD dated merely instructed taxpayer to pay the ad valorem penalties “within the time shown in the assessment notice,” but the FAN itself contained no due date, with the corresponding field left blank. Thus, there was no date certain or specific period within which petitioner was required to pay, resulting in the absence of a valid demand for payment. (Orica Nitrates Philippines, Inc. v. CIR, CTA Case No. 10946, April 15, 2026)

FLD/FAN ISSUED 10-DAYS AFTER THE RECEIPT OF THE PAN RENDERS THE ASSESSMENT VOID. The Tax Code requires the BIR to issue a PAN informing the taxpayer of the facts and law supporting the proposed deficiency assessment and to give the taxpayer 15 days from receipt of the PAN to respond before the FLD/FAN may be validly issued; these requirements are substantive due process safeguards, and failure to strictly comply renders the assessment void. In this case, the BIR issued the PAN but issued the FLD/FAN only 10 days later, without waiting for the full 15-day period, thereby depriving the taxpayer of the opportunity to contest the PAN and present supporting evidence. Accordingly, the FLD/FAN and the resulting deficiency tax assessment were declared void and without effect, and the assessments were cancelled and set aside. [(Transnational E-Business Solutions, Inc. v. CIR, CTA Case No. 10912,  April 13, 2026; CIR v. Travel Warehouse, Inc., CTA EB No. 3011, (CTA Case No. 10098), April 6, 2026)]

REVENUE ISSUANCES

Revenue Memorandum Circular No. 96-2026

The BIR clarifies the qualification of Export-Oriented Enterprises (EOE) to VAT Refund during the transitory period for securing a VAT Zero-Rating Certificate from the Export Marketing Bureau of the Department of Trade and Industry (EMB-DTI).

  • EOE that were passed on VAT on their local purchases and importation during the effectivity of RA 12066 on November 28, 2024 up to issuance of the VAT zero-rating certification by the EMB-DTI, may claim VAT refund for such passed-on VAT, provided that such certification was issued during the transitory period ending December 31, 2025
  • If EOE attains 70% threshold from the preceding year but did not obtain EMB certification (including transitory period), it cannot refund input VAT covering immediately succeeding year; but input VAT may be carried forward to subsequent taxable quarters until utilized
  • If VAT has been reimbursed, credited, adjusted, recovered from suppliers or utilized, it cannot be refunded.

BIR DEADLINES FROM SEPTEMBER 14, 2026 TO SEPTEMBER 20, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
SEPTEMBER 14, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group B. Month of August 2026
SEPTEMBER 15, 2026
REGISTRATION (Online thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Accounts/Invoices and Other Accounting Records. Fiscal Year ending August 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1702–RT/1702-EX/1702-MX– Fiscal Year ending May 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return For Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending May 31, 2026
eFILING & PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld). eFPS Filers under Group A. Month of August 2026
e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld)  – eFPS Filers under Group E, D, C & B. Month of August 2026
SEPTEMBER 16, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers – September 1-15, 2026
SEPTEMBER 20, 2026 eFILING & PAYMENT (Online/Manual) – BIR Form 1600 WP (Remittance Return of Percentage Tax on Winnings and Prizes Withheld by Race Track Operators) – eFPS & Non-eFPS Filers. Month of August 2026
AUGUST 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – Non-eFPS Filers. Fiscal Quarter ending July 31, 2026
SUBMISSION – Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products. Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2551Q (Quarterly Percentage Tax Return). Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider) – Fiscal Quarter ending July 31, 2026
AUGUST 29, 2026 e-FILING & PAYMENT (Online/Manual) – BIR Form 1702Q (Quarterly Income Tax Return For Corporations, Partnerships and Other Non-Individual Taxpayers) and Summary Alphalist of Withholding Taxes (SAWT). For the Quarter ending June 30, 2026
AUGUST 30, 2026
SUBMISSION – Proof of eFiled BIR Form 1702 – RT/EX/MX with Audited Financial Statements (AFS), 1709 (if applicable), and Other Attachments through Electronic Audited Financial Statements (eAFS) or Manually. Fiscal Year ending April 30, 2026
SUBMISSION – Soft Copies of Inventory List and Schedules stored and saved in DVD-R/USB properly labeled together with Notarized Sworn Declaration. Fiscal Year ending July 31, 2026
e-SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – eFPS Filers. Fiscal Quarter ending July 31, 2026
ONLINE REGISTRATION (thru ORUS) – Computerized Books of Accounts and Other Accounting Records. Fiscal Year ending July 31, 2026

Dear Clients, Colleagues and Friends:

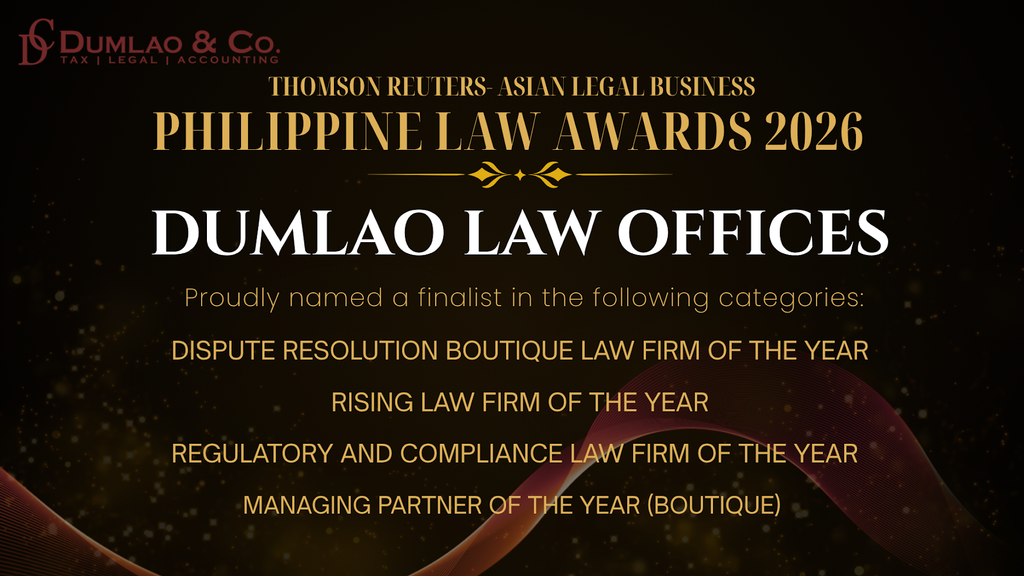
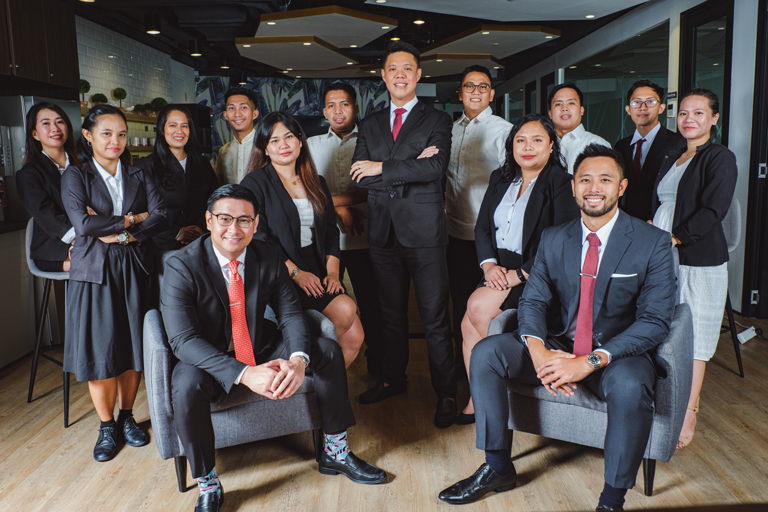
We are thrilled to share that Dumlao Law Offices has been named as a finalist in the 11th Annual ALB Philippine Law Awards 2026, presented by Asian Legal Business.

The firm has been recognized as a finalist in the following categories:

  • Dispute Resolution Boutique Law Firm of the Year
  • Rising Law Firm of the Year
  • Regulatory and Compliance Law Firm of the Year
  • Managing Partner of the Year (Boutique)

This recognition is a meaningful milestone for our firm and reflects our continued commitment to excellence in legal practice and service.

We are grateful for the continued trust and confidence extended to Dumlao Law Offices and remain committed to providing quality and dependable legal services.

Thank you for being part of our journey.

COURT OF TAX APPEALS (CTA) DECISIONS

IN VAT REFUND CLAIMS, WHERE THE CIR FAILS TO ACT WITHIN THE 90-DAY PERIOD, THE CLAIM IS DEEMED DENIED AND MUST BE APPEALED WITHIN 30 DAYS; SEE DISSENTING OPINION. The CTA has jurisdiction over decisions and inaction of the CIR involving VAT refund claims, and the CIR’s failure to act within the prescribed 90-day period constitutes a deemed denial, which must be appealed to the CTA within 30 days from the expiration of such period; applying these rules, the CIR failed to act within the 90-day period, which expired on October 13, 2020, such that the taxpayer had until November 12, 2020 to file its judicial claim, and the subsequent VAT refund notice issued beyond the 90-day period did not revive or extend the appeal period, rendering the Petition for Review filed only on November 20, 2020 late and depriving the CTA of jurisdiction. Dissenting opinion: The TRAIN Law did not eliminate the taxpayer’s right to appeal either the CIR’s inaction or a denial issued after the 90-day processing period. The TRAIN Law deleted the language referring to inaction and shortened the processing period to 90 days; however, CTA Charter continued to expressly grant the CTA jurisdiction over CIR inaction. A taxpayer could still either appeal the CIR’s deemed denial within 30 days after the lapse of the 90-day period or wait for the CIR’s actual decision and appeal within 30 days from receipt, even if the decision was issued after the 90-day period. [Franklin Baker Company of the Philippines v. CIR, CTA EB No. 3025 (CTA Case No. 10407), February 10, 2026]

A TAXPAYER CLAIMING A CWT REFUND MUST PROVE THAT THE INCOME PAYMENTS SUBJECT TO CWT WERE INCLUDED IN ITS GROSS INCOME. The Court generally cannot consider evidence that was not formally offered, and even when this rule is relaxed, the evidence must have been identified through testimony and incorporated into the record; applying this rule, the taxpayer failed to prove that the income payments subjected to the claimed CWTs were included in its gross income because its AITR, AFS, and GL reflected a discrepancy, and it did not adequately reconcile the difference or trace the income payments reported in the SAWT and CWT certificates to the revenues declared in its AITR. Although the taxpayer presented reconciliation tables attributing the discrepancy to accounting adjustments, revenues not subjected to CWT, and timing differences, these were presented for the first time on appeal, were not testified to by its witnesses, were unsupported by specific evidence, and were not evaluated by the Court in Division; hence, they constituted mere allegations that could not establish entitlement to the claimed CWT refund. The Court likewise emphasized that the findings of the Court-commissioned ICPA were not conclusive and could not relieve taxpayer of its burden to independently substantiate its refund claim. [Ford Group Philippines v. Commissioner of Internal Revenue, CTA EB No. 3026 (CTA Case No. 10507), February 4, 2026]

ONLY A FINAL DECISION OR INACTION OF THE CIR OR A DULY AUTHORIZED REPRESENTATIVE IS APPEALABLE TO THE CTA; AN RDO’S LETTER IS NOT AN APPEALABLE DENIAL SINCE HE IS NOT CONSIDERED AS AUTHORIZED REPRESENTATIVE. Only a decision or inaction of the CIR, or of a duly authorized representative acting pursuant to a valid delegation of authority, is appealable to the CTA; although the CIR may delegate the authority to decide refund claims to qualified subordinate officials, such delegation must comply with the applicable rules, which provide that VAT refund claims are processed by the RDO but their approval or denial must be made by the Regional Director or the appropriate authorized official. Applying these rules, the letter issued by RDO and received by the taxpayer was not an appealable decision because an RDO, acting alone, lacked authority to finally deny the refund claim, and the letter itself did not convey a tenor of finality, stating merely that the taxpayer failed to prove its entitlement to the refund and providing the information for its guidance. The actual appealable denial was the subsequent letter signed by Regional Director, categorically denying the VAT refund for lack of legal and factual basis; however, the taxpayer had already filed its Petition for Review before receipt of the authorized denial, making the CTA petition premature and depriving the Court of jurisdiction. [Firmenich (Philippines), Inc. v. Commissioner of Internal Revenue, CTA EB No. 2992 (CTA Case No. 10209), December 15, 2025]

 A FACILITY CONDUCTING BUSINESS IS CONSIDERED AS A BRANCH, WHICH IS REQUIRED TO BE VAT-REGISTERED FOR INPUT VAT REFUND PURPOSES. Every person subject to internal revenue tax must register with the appropriate RDO before commencement of business, and every separate or distinct establishment or facility where sales transactions are conducted must be registered as a branch and subjected to the corresponding annual registration fee; this registration requirement is likewise a prerequisite to being considered a VAT-registered person entitled to claim an input VAT refund. Applying these rules, although the Palawan Facility and Technopoint Facility were denominated as facilities, the taxpayer generated sales of call center services to, thereby making the facilities branches for VAT registration purposes; however, the taxpayer failed to register them as branches and pay the corresponding annual registration fees on or before the sales transactions occurred. Consequently, the taxpayer was not a VAT-registered person during the period covered by the refund claim [Foundever Philippines Corporation (formerly Sitel Philippines Corporation) v. Commissioner of Internal Revenue, CTA EB No. 2942 (CTA Case No. 10200), December 18, 2025]

A TAXPAYER CLAIMING AN EXCISE TAX REFUND MUST SUFFICIENTLY IDENTIFY AND TRACE THE PETROLEUM PRODUCTS SOLD TO TAX-EXEMPT ENTITIES TO THE PRODUCTS ON WHICH THE EXCISE TAX SUBJECT OF THE REFUND CLAIM WAS ACTUALLY IMPOSED AND PAID. The taxpayer bears the burden of substantiating its entitlement by competent evidence establishing a clear nexus between the excise taxes paid and the petroleum products subsequently sold to tax-exempt entities; moreover, the Court is not bound by the findings of the ICPA, and evidence submitted to the ICPA does not constitute evidence formally offered before the Court. Applying these rules, the taxpayer failed to establish that the bunker fuel oil (BFO) and special fuel oil (SFO) sold to tax-exempt entities were the same petroleum products on which it paid excise taxes, as it did not submit the Official Registry Books (ORBs), complete and properly supported fuel-oil inventory records, and all relevant sales invoices; the missing invoices further prevented the Court from tracing the inventory using the first-in, first-out method. The Court also rejected petitioner’s claim that the ORB requirement was introduced later, noting that ORBs had previously been utilized in jurisprudence and tax refund examinations, and held that the taxpayer could not rely on its submission of the ORBs to the ICPA because such submission was not equivalent to a formal offer of evidence before the Court. [SL Harbor Bulk Terminal Corporation v. Commissioner of Internal Revenue, CTA EB No. 2982 (CTA Case No. 10320), December 23, 2025 and CTA EB No. 2981 (CTA Case No. 10440), February 2, 2026]

LACK OF DESCRIPTION IN INVOICE WARRANTS THE DISALLOWANCE OF INPUT VAT REFUND; CROSS-REFERENCING TO BILLING STATEMENTS IS NOT SUFFICIENT. Admissibility of evidence must be distinguished from its probative value, and a taxpayer seeking an input VAT refund bears the burden of proving its legal and factual entitlement through sufficient, competent, complete, and legible evidence; moreover, strict compliance with VAT substantiation and invoicing requirements is necessary because the VAT invoice or official receipt serves as the primary evidence of creditable input VAT and ensures an accurate audit trail. Applying these rules, although the taxpayer’s physical copies of the official receipts were admitted in evidence, the scanned copies submitted for the Court’s appreciation were blurred and unreadable, preventing the Court from properly examining and verifying the input VAT credits claimed; hence, their admission did not establish their probative value. The taxpayer likewise failed to comply with the requirement that VAT official receipts for services indicate the nature of the service, and its admission that the subject ORs lacked such description could not be cured by identifying the suppliers or cross-referencing billing statements and invoices, since other documents cannot substitute for the required VAT receipts themselves. The Court further held that the principle of VAT neutrality cannot override the NIRC’s mandatory invoicing and documentary requirements, which are substantive requirements rather than mere technicalities. [Commissioner of Internal Revenue v. New York Bay Philippines, Inc., CTA EB Nos. 2915 & 2916 (CTA Case No. 10417), December 2, 2025]

Defective verification is not fatal and may be corrected or dispensed with when warranted by the circumstances, while a defect in the certification against forum shopping is generally not curable by subsequent submission unless there is substantial compliance or special or compelling circumstances; applying these rules, the Court found substantial compliance because the petitioner expressly explained that it could not initially submit the authenticated documents due to distance and time constraints and subsequently filed the Apostilled Verification and Certification of Non-Forum Shopping and Director’s Certificate as soon as these were secured, thus satisfying the mandatory purpose of the requirements without unduly rigid application that would defeat the orderly administration of justice [Commissioner of Internal Revenue v. Grid Solutions (US) LLC., CTA EB No. 2814 (CTA Case No. 10146)]

DOE REGISTRATION IS REQUIRED FOR ZERO-VAT SALE ON SALE OF ELECTRICITY GENERATED FROM RENEWABLE ENERGY SOURCES. Sales of electricity generated from renewable energy sources may qualify for 0% VAT, but the incentive is subject to the statutory and regulatory conditions imposed on Renewable Energy Developers, including registration with the DOE, and the taxpayer must still prove through competent evidence that it actually made zero-rated sales; applying these rules, the Court held that the taxpayer’s reliance on the NIRC alone was misplaced because R.A. No. 9513 is a later and special law specifically governing fiscal incentives for RE Developers, and its express repealing clause and IRR require an RE Developer to secure DOE registration to qualify for the incentives, including VAT zero-rating. Although the taxpayer submitted a BOI Certificate of Registration, it failed to timely present the required DOE Certificate of Registration, which it attached only to its Motion for Reconsideration; evidence that could have been presented during trial but was belatedly submitted without justification constitutes forgotten evidence and cannot be admitted on appeal. More importantly, even assuming the taxpayer could qualify for the incentive, it still failed to prove the actual existence of zero-rated sales. Its Quarterly VAT Return reported no zero-rated sales; its AFS and AITR showed only interest income and no operating revenue from electricity generation; and taxpayer itself admitted that it had no recorded sale of electricity because it only began generating electricity in the subsequent year. Its subsequent reliance on its later AITR was likewise insufficient because the return merely reflected aggregate revenue without identifying the nature of the transactions or establishing that they were zero-rated sales. The official receipts submitted for the first time before the Court En Banc were also inadmissible forgotten evidence because they had not been formally offered during the proceedings before the Court in Division and no justification was given for their late submission. [YH Green Energy Incorporated v. Commissioner of Internal Revenue, CTA EB No. 2995 (CTA Case No. 9784), February 10, 2026]

NON-RESIDENT FOREIGN CORPORATION’S SALE OF SHARES IN A DOMESTIC CORPORATION IS EXEMPT FROM CGT IF DOMESTIC CORPORATION’S PROPERTY AND EQUIPEMENT DOES NOT EXCEED THE 50% THRESHOLD. A claim for refund of erroneously or illegally collected taxes must be supported by timely administrative and judicial claims, and the claimant must establish its right to the refund, including the specific legal basis for any claimed tax exemption; applying these rules, the taxpayer established its entitlement to a refund of the CGT paid on the sale of domestic company shares because RP-US Tax Treaty grants the exclusive taxing right over gains from the sale of shares to the seller’s country of residence, unless the shares represent an interest in a corporation whose assets principally consist of Philippine real property, and the domestic corporation’s financial statements showed that its Philippine property and equipment well below the 50% threshold; the Philippines had no taxing right over the capital gain, and the statutory taxpayer/seller had standing to claim the refund. [Commissioner of Internal Revenue v. Grid Solutions (US) LLC., CTA EB No. 2814 (CTA Case No. 10146)]

REVENUE ISSUANCES

BIR RMO No. 22-2026, August 24, 2026

The BIR prescribes the consolidated and revised policies, guidelines and procedures for the BIR audit program

  • Taxpayer (TP) is subject to only 1 Letter of Authority (eLA) for a given year covering all applicable internal revenue tax type
  • Audit shall be system-assisted, risk-based. TP identity remained concealed during the selection and assignment stage to ensure impartiality and prevent undue influence.
  • Mandatory cases:
    • Suspected fraud such as declaring 30% less income or 30% more expenses;
    • TP identified through specific industry knowledge, data from third parties, or publicly accessible information;
    • TP previously under a Mission Order where preliminary findings show a 30% or greater understatement of sales;
    • ONETT where findings resulted in tax deficiency or real property transactions with findings in the eCAR system (should be limited only to a specific ONETT and conducted by the investigating office which issued the eCAR and which has proper jurisdiction; if eCAR is used by the office which has no jurisdiction, referral to the appropriate office to be made and corresponding eLA is used)
    • Using tax exemptions or special incentives;
    • Non-compliance with tax obligations arising from Spontaneous Exchange of Information (EOI);
    • ТP requesting for tax clearance whose gross sales for the immediately preceding year exceed Php3M or gross assets is more than Php8M, due to:
      • Death of the taxpayer; or 
      • Taxpayers retiring from business
      • Taxpayers undergoing merger/ consolidation/  split-up/ spin-off and other types of corporate reorganizations
    • TP who failed to respond to Third Party Information (TPI) request
    • TP with validated discrepancies or material inconsistencies identified through the system.
    • TP with refund claims
  • Mandatory cases do not require CIR’s approval. Approving authority is regional director or ACI R for LTS; Effect of misclassification – administrative sanction
  • Taxpayer enjoying tax exemptions or incentives is not automatically subjected to audit, and subject to risk-based evaluation
  • Failure to respond to request for confirmation of TPI data matching within the period – TP shall be subject to mandatory audit
  • For refunds of income tax under Section 58 (e) and 76(C), LOA and TVN will be issued
  • Service of LOA requires First and Second/Final notice if taxpayer fails to comply within 10 days
  • Place of examination – place of business or BIR office; if documents are voluminous or transport or examination at the BIR would be impractical, burdensome or disruptive to business operation, TP has option on the venue and manner of examination; TP consent on audit venue to be accomplished
    • If at BIR office – taxpayer may opt to physically submit the BIR records
    • If principal place of business – TP to coordinate with RO; TP shall provide suitable area
      • Photocopies may be accepted; TP or authorized representative must certify that the documents are true and faithful reproduction of the original. BIR may require presentation of original for solely for verification. 
      • SDT – no option for venue; venue is BIR office specified in the SDT
  • Minutes of Meeting after NOD is issued are required
  • Prescriptive period suspended – when issuance of SDT or EOI BIR is requested; effectivity date: upon date of receipt of request by concerned office; to resume when BIR officer receives the requested information
  • Termination Letter – to be prepared for all paid cases or cases with no findings or discrepancies; issued by Regional office; LTS, HREA-EAS; 
  • Priority cases (electronically selected based on risk-based criteria; uses the data from filed tax returns and other information in the BIR system)
    • Drastic decrease in reported sales or VAT payments
    • Large increases in sales that are zero-rated or exempt from tax
    • TP with Discrepancy Notices
    • Differences between current VAT filings and what was carried over from previous months
    • Claiming input VAT that cover more than 75% of the total output tax
    • Paying income tax that is less than 2% of the gross sales/revenues
    • TP filing percentage tax returns exceededing the VAT threshold
    • Reporting a net loss despite having substantial sales
    • Operating for more than five years without ever being audited
    • Taxpayers with increase in assets of more than 50% from the previous year but with reported net loss
    • Claims for damages from natural disasters or for old inventory
    • Getting almost all income from a parent company or affiliate
    • Taxpayers claiming write-off of input tax as allowable deduction in its annual income tax
    • Sharing expenses between different branches or companies in a group. 
  • Recommendations by the heads of investigating office must be supported by written justification. IT shall include the audit selection criteria; subject to approval of the CIR upon recommendation of the DCIR-OG, DCIR-SRG before the eLA is issued
  • Effectivity: immediately (august 24, 2026)

BIR DEADLINES FROM AUGUST 24, 2026 TO AUGUST 30, 2026. A gentle reminder on the following deadlines, as may be applicable.

DATE FILING/SUBMISSION
AUGUST 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – Non-eFPS Filers. Fiscal Quarter ending July 31, 2026
SUBMISSION – Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products. Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2551Q (Quarterly Percentage Tax Return). Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider) – Fiscal Quarter ending July 31, 2026
AUGUST 29, 2026 e-FILING & PAYMENT (Online/Manual) – BIR Form 1702Q (Quarterly Income Tax Return For Corporations, Partnerships and Other Non-Individual Taxpayers) and Summary Alphalist of Withholding Taxes (SAWT). For the Quarter ending June 30, 2026
AUGUST 30, 2026
SUBMISSION – Proof of eFiled BIR Form 1702 – RT/EX/MX with Audited Financial Statements (AFS), 1709 (if applicable), and Other Attachments through Electronic Audited Financial Statements (eAFS) or Manually. Fiscal Year ending April 30, 2026
SUBMISSION – Soft Copies of Inventory List and Schedules stored and saved in DVD-R/USB properly labeled together with Notarized Sworn Declaration. Fiscal Year ending July 31, 2026
e-SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – eFPS Filers. Fiscal Quarter ending July 31, 2026
ONLINE REGISTRATION (thru ORUS) – Computerized Books of Accounts and Other Accounting Records. Fiscal Year ending July 31, 2026

COURT OF TAX APPEALS (CTA) DECISIONS

TAXPAYER CANNOT CLAIM REFUND FOR VAT ERRONEOUSLY PASSED ON BY SUPPLIERS ON ZERO-RATED PURCHASES; THE PROPER REMEDY IS REIMBURSEMENT FROM THE SUPPLIERS. A taxpayer that is entitled to zero-rated purchases is not the proper party to claim a refund of VAT erroneously passed on by its suppliers; the buyer’s remedy is to seek reimbursement from the supplier. Applying these principles, even assuming that taxpayer’s purchases from renewable energy suppliers were zero-rated, the VAT allegedly shifted to the taxpayer should not have been charged in the first place; the taxpayer therefore cannot recover the erroneously passed-on VAT through a Section 112 refund claim merely because it bore the economic burden. The Supreme Court held that the proper recourse of a buyer mistakenly charged VAT on zero-rated purchases is against its supplier and the same principle extends to  renewable energy developers. Thus, the Court held that the taxpayer was not the proper party to claim a refund of the input VAT erroneously passed on by its suppliers, without prejudice to its right to seek reimbursement from them. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

THE INCENTIVES GRANTED TO RE DEVELOPERS EXPRESSLY COVER BOTH POWER AND NON-POWER APPLICATIONS; INPUT VAT RELATED TO NON-POWER APPLICATION CANNOT BE VALIDLY SUBJECT OF INPUT VAT REFUND. The law (third paragraph) provides zero-rated VAT on local purchases of goods, properties, and services needed for the whole process of exploring and developing renewable energy sources up to their conversion into power. The Court held that the third paragraph does not distinguish between power and non-power applications: the phrase “whole process of exploring and developing renewable energy sources” sufficiently covers non-power applications, while the succeeding phrase “up to its conversion into power” merely extends the coverage to power applications and does not exclude non-power RE developers. Since petitioner was accredited by the DOE as a biomass RE developer for non-power application, specifically a biofuel manufacturer producing biodiesel/Coconut Methyl Ester, its purchases falling within the statutory coverage were entitled to VAT zero-rating. Accordingly, the input VAT pertaining to purchases entitled to zero-rating should be disallowed from the taxpayer’s VAT refund claim. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

INPUT VAT ON CAPITAL GOODS EXCEEDING PHP MILLION MUST BE PROPERLY SUBSTANTIATED BY INVOICE AND AMORTIZATION SCHEDULE; PRIOR YEAR INPUT VAT RETURN IS NOT SUFFICIENT. Input VAT on capital goods with an aggregate acquisition cost exceeding Php1 million may be spread over 60 months or the capital goods’ estimated useful life, whichever is shorter, but the taxpayer must properly substantiate the capital-goods purchases and the corresponding amortization; supporting documents are necessary to establish the nature of the purchases as capital goods and to verify the proper amortization of the input VAT. Applying this rule, although the taxpayer claimed that the deferred input VAT carried over from CY 2017 was supported by its Q4 CY 2017 VAT return and that it represented the remaining amortized input tax, the taxpayer failed to present the underlying documents establishing the capital-goods purchases and the correctness of the amortization computation; even its independent CPA reported that the supporting documents for the capital-goods input taxes deferred and amortized in CY 2018 had not been provided. Thus, the mere appearance of the amount in the prior-period VAT return was insufficient substantiation, and the Court properly disallowed the deferred input VAT from the refund claim. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

INPUT VAT MAY BE SUPPORTED BY PHOTOCOPIES. A duplicate, including a photocopy, is admissible to the same extent as an original unless a genuine question is raised regarding the authenticity of the original or admission of the duplicate would be unjust or inequitable. The Supreme Court recognized that a photocopy falls within the definition of a duplicate and is therefore admissible as an original. Applying this rule, the Court held that the input VAT supported by photocopies of sales invoices and official receipts should not have been disallowed, since the BIR did not question the authenticity of the originals nor establish that admitting the photocopies would be unjust or inequitable. Accordingly, the disallowance was reversed and the amount was added back to the taxpayer’s valid input VAT for CY 2018. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

A VAT-REGISTERED TAXPAYER CLAIMING INPUT VAT ATTRIBUTABLE TO ZERO-RATED SALES HAS TWO ALTERNATIVE OPTIONS: (1) CHARGE THE INPUT VAT AGAINST OUTPUT VAT FROM REGULAR 12% VATABLE SALES AND CLAIM A REFUND ONLY OF ANY RESULTING EXCESS INPUT VAT, OR (2) CLAIM THE ENTIRE INPUT VAT ATTRIBUTABLE TO ZERO-RATED SALES FOR REFUND OR TAX CREDIT. The Court cannot impose the first method when the taxpayer chose the second. In this case, however, the Court found that the taxpayer original Petition for Review and its own computation showed that it chose the first option, as it first allocated input VAT to VATable sales and determined whether such input VAT exceeded its declared output VAT before arriving at the refundable amount. Thus, the Court in Division properly charged the substantiated input VAT against petitioner’s output VAT. The Court En Banc determined valid input VAT, of which an amount was allocated to VATable sales, leaving  output VAT still due; the remaining input VAT allocated to zero-rated sales was likewise insufficient to produce any excess input VAT refundable to petitioner. Accordingly, despite the adjustment recognizing the photocopied supporting documents, the taxpayer still had no excess input VAT for refund and failed to satisfy the requisites under Section 112. [Pure Essence International, Inc. v. Commissioner of Internal Revenue, CTA EB No. 3023 (CTA Case No. 10411), February 27, 2026]

INVOICE ISSUED PRIOR TO DATE OF ATP CANNOT VALIDLY SUBSTANTIATE INPUT VAT; ANTE-DATING IS NOT ALLOWED. Taxpayers are required to issue a duly registered invoice at the point of each sale, and the supporting invoice must be covered by a valid and subsisting Authority to Print (ATP) applicable to the date of the transaction. Applying this rule, the Court rejected the taxpayer’s argument that the subject document remained valid merely because they were eventually registered with the BIR under an ATP dated earlier than ATP date, and that the NIRC does not expressly prohibit antedating. The Court clarified that antedating itself was not the decisive issue; rather, the receipts (now invoice) were disallowed because they were not duly registered receipts at the point of each sale, constituting non-compliance with the invoicing and substantiation requirements. The official receipts (now invoice) covering transactions dated earlier should have been supported by an ATP valid and subsisting on those dates, but the receipts (now invoice) bore serial numbers outside the range authorized by  a later ATP. Consequently, the receipts could not substantiate the claimed input VAT. [Mastercard Transaction Services (Philippines) Inc. v. Commissioner of Internal Revenue, CTA EB Nos. 3062 & 3066 (CTA Case No. 10628), March 18, 2026]

AN EXPORT SALE IS SUBJECT TO ZERO PERCENT VAT ONLY WHEN THE SALE IS MADE BY A VAT-REGISTERED PERSON, THERE IS AN ACTUAL SALE AND SHIPMENT OF GOODS FROM THE PHILIPPINES TO A FOREIGN COUNTRY, AND THE SALE IS PAID FOR IN ACCEPTABLE FOREIGN CURRENCY AND ACCOUNTED FOR IN ACCORDANCE WITH BSP RULES. The taxpayer bears the burden of strictly proving both the factual basis of its zero-rated sales and compliance with the statutory and documentary requirements, since a VAT refund is in the nature of a tax exemption; moreover, a CTA case is litigated de novo, and the judicial claim must be established by the evidence formally presented before the CTA. Applying these rules, the taxpayer failed to prove that its reported sales actually qualified for VAT zero-rating. The Court found that some of reported sales had no valid VAT zero-rated sales invoices or lacked corresponding bills of lading and/or export declarations; or bills of lading that were inadmissible, missing from the records, did not correspond with the exhibits offered, or were illegible. The taxpayer likewise failed to establish the third requirement because its inward remittance certifications and bank transaction reports did not correspond with the amounts stated in the sales invoices; its explanations that the discrepancies resulted from advance payments, prior-period receivables, or the practice of splitting or consolidating invoice amounts were merely bare assertions unsupported by sales invoices, official receipts, bank credit advices, or reconciliation schedules. Because the taxpayer failed to first establish the existence of valid zero-rated sales to which the claimed unutilized input VAT could be attributed, the Court found it unnecessary to examine the remaining requisites for the refund. [Agri Exim Global Philippines, Inc. v. CIR, CTA EB No.3075, CTA Case No. 10621, March 24, 2026]

WHERE THE TAXPAYER IMPORTED JET A-1 FUEL AND SUBSEQUENTLY SOLD IT TO QUALIFIED INTERNATIONAL CARRIERS FOR USE OUTSIDE THE PHILIPPINES, THE FUEL BECAME EXEMPT. Under the applicable provisions on excise tax and tax exemption of petroleum products sold to international carriers, excise tax is an indirect tax imposed on the article itself, with the statutory liability attaching to the importer or manufacturer, while the economic burden may be passed on to the buyer; hence, the buyer is not the statutory taxpayer entitled to claim the exemption. Applying this rule, the Court held that the international carriers that purchased the Jet A-1 fuel merely bore the economic burden of the excise tax, while the taxpayer, as the importer and statutory taxpayer, was the proper party to claim the exemption and refund. Although the excise tax became due upon importation, the subsequent sale of the Jet A-1 fuel to qualified international carriers for use and consumption outside the Philippines rendered the petroleum products exempt, resulting in the excise taxes previously paid being erroneously or illegally collected and therefore refundable. The taxpayer sufficiently proved through competent evidence that it imported the Jet A-1 fuel and subsequently sold it to international carriers; thus, the CTA in Division correctly granted the refund. [(CIR v. Pilipinas Shell Petroleum Corporation, CTA EB No. 3027, CTA Case NO. 10352, March 11, 2026)]

UNDER THE 2-YEAR PRESCRIPTIVE PERIOD FOR TAX REFUNDS, THE PERIOD RUNS FROM PAYMENT OF THE ERRONEOUSLY OR ILLEGALLY COLLECTED TAX; THUS, BECAUSE THE TAXPAYER IMPROPERLY RECOGNIZED DEFERRED SUBSCRIPTION REVENUE IN 2017 AND PAID THE CORRESPONDING INCOME TAX IN APRIL 2018, ITS REFUND CLAIMS FILED ONLY IN APRIL AND MAY 2021 WERE PRESCRIBED; WITH DISSENTING OPINION. Both the administrative and judicial claims for refund of erroneously or illegally collected taxes must be filed within  2 years from the date of payment of the tax, with timely filing being mandatory and jurisdictional; applying these provisions, the Court En Banc held that the erroneous payment arose not in CY 2018 but in CY 2017, when the taxpayer improperly included Php200M of deferred subscription revenue, collected but not yet earned, in its 2017 taxable income and paid the corresponding income tax in April 2018. Since the taxpayer uses the accrual method, income should be recognized when earned, and the deferred subscription revenue was properly earned only in 2018; thus, the two-year period commenced in April 2018 and, considering the applicable COVID-19 extensions, taxpayer had only until June 2020 to file its claims. However, the taxpayer filed its administrative claim only in April 2021 and its judicial claim in May 2021, both beyond the prescriptive period, depriving the CTA of jurisdiction and requiring dismissal of the refund case. Dissenting Opinion: The two-year prescriptive period should be reckoned from its 2018 income tax payment, not from 2017 when the taxpayer reported the cash deposits or advances as income when received in 2017 in compliance with RMC No. 16-2013; the Court should respect the accounting method adopted by the taxpayer [SAS Institute (Philippines) Inc. v. Commissioner of Internal Revenue & Commissioner of Internal Revenue v. SAS Institute (Philippines) Inc., CTA EB Nos. 2991 & 2994 (CTA Case No. 10537), March 4, 2026.]

REVENUE ISSUANCES

RMC No. 95-2026, August 14, 2026

The BIR provides extension of the deadlines for the filing of tax returns of corresponding taxes due thereon, including submission of required documents for taxpayers due to unavailability of eBIR forms offline package

Covered Return Deadlines on August 10 to 16, 2026
Extended Period August 18, 2026
Excluded from the Coverage Taxpayers mandated to use eFPS

BIR DEADLINES. A gentle reminder on the following deadlines, as may be applicable:

BIR DEADLINES FROM AUGUST 10, 2026 TO AUGUST 16, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
AUGUST 18, 2026
SUBMISSION – List of Buyers of Sugar Together with a Copy of Certificate of Advance Payment of VAT made by each buyer appearing in the List by a Sugar Cooperative. Month of July 2026
SUBMISSION – Information Return on Releases of Refined Sugar by the Proprietor or Operator of a Sugar Refinery or Mill. Month of July 2026
e-SUBMISSION – Monthly e-Sales Report for All Taxpayers using CRM/POS and/or Other Similar Business Machines whose last digit of 9-digit TIN is Odd Number. Month of July 2026
e-FILING & PAYMENT/REMITTANCE (Online/Manual) – BIR Form 2200-M Excise Tax Return for the Amount of Excise Taxes Collected from Payment Made to Sellers of Metallic Minerals. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2200-C (Excise Tax Return for Cosmetic Procedures) with Monthly Summary of Cosmetic Procedures Performed. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 0620 (Monthly Remittance Form of Tax Withheld on the Amount Withdrawn from the Decedent’s Deposit Account) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or 1600-PT (Other Percentage Taxes Withheld) and Monthly Alphalist of Payees (MAP) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1606 – (Withholding Tax Remittance Return for Onerous Transfer of Real Property Other Than Capital Asset Including Taxable and Exempt). Month of July 2026
e-FILING & e-PAYMENT/REMITTANCE – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or BIR Form 1600-PT (Other Percentage Taxes Withheld) and 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – National Government Agencies (NGAs). Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E. Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group D. Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group C.  Month of July 2026
AUGUST 18, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group B. Month of July 2026
AUGUST 18, 2026
REGISTRATION (Online Thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Accounts/Invoices and Other Accounting Records. Fiscal Year ending July 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1702 – RT/EX/MX. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return For Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1701Q (Quarterly Income Tax Return For Individuals, Estates & Trusts) and Summary Alphalist of Withholding Taxes (SAWT) – eFPS & Non-eFPS Filers. For the Quarter ending June 30, 2026
e-FILING & e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group A. Month of July 2026
e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded)  and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E, D ,C & B.  Month of July 2026
AUGUST 18, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers. August 1-15, 2026

COURT OF TAX APPEALS DECISIONS

REASONS FOR DISALLOWANCE OF CWT. A taxpayer is entitled to a refund of excess Creditable Withholding Taxes (CWT) if, among others, the income payments subject of the CWTs are declared as part of the taxpayer’s gross income in its annual ITR and the fact of withholding is established through duly issued BIR Form No. 2307, without requiring proof of the withholding agent’s actual remittance or the submission of a SAWT. Here, while the taxpayer substantiated most of its claimed CWTs through valid BIR Forms 2307, the Court disallowed some CWT due to defective withholding certificates and further denied CWT corresponding to income payments that were not sufficiently proven to have been reported as part of gross income. Reasons for the disallowance: variance between sales invoice and schedule; unreadable invoice; cancelled sales invoice, untraced payment file; incorrect TIN of the taxpayer; the TIN of the Head Office was indicated but the address is the Branch Office; Incomplete address of the taxpayer; BIR Forms 2307 were dated outside of the claimed period; variance in the amount of CWT per BIR Form 2307 versus per books; CWT not within the period of claim; no signature of the payor-issuer/authorized representative; with alteration on taxpayer’s name without counter signature, alteration on the taxpayer’s TIN without counter signature; income payments not traced to the GL/supporting documents [Watsons Personal Care Stores (Philippines), Inc. v. CIR, CTA Case No. 10883, November 26, 2025; Watsons Personal Care Stores (Philippines), Inc., CTA Case No. 10504, February 16, 2026; see also Sonic Sales & Distribution, Inc. v. CIR, CTA Case No. 10888, February 18, 2026]

OSG’S RECEIPT OF THE RESOLUTION, NOT BIR’S, IS THE RECKONING PERIOD TO APPEAL TO THE CTA EN BANC. An aggrieved party may appeal a CTA Division decision or resolution on a motion for reconsideration or new trial to the Court En Banc within 15 days from receipt thereof, while the Administrative Code vests in the Office of the Solicitor General (OSG) the authority and duty to represent the government in appellate proceedings, with deputized government lawyers remaining under its supervision and control. Service upon the deputized counsel or BIR Legal Division is insufficient; the OSG, as principal counsel, must receive the decision and has the authority to determine whether an appeal should be taken. In this case, although the BIR received the assailed Resolution in December, the OSG received it only in January the following year, while the BIR filed the Petition for Review in December, before the OSG had even received the Resolution. There was also no evidence that the BIR had been duly authorized by the OSG to file the appeal. Thus, the petition lacked the requisite OSG authority, and the 15-day appeal period could not be reckoned from the BIR’s receipt of the Resolution. Consequently, the appeal was not properly perfected, causing the assailed Resolution to attain finality (CIR v. MSCI Hongkong Limited, CTA EB No. 3047, CTA Case No. 10474, February 19, 2026)

A DUPLICATE COPY, INCLUDING A PHOTOCOPY, OF A DOCUMENT IS ADMISSIBLE TO THE SAME EXTENT AS AN ORIGINAL UNLESS (1) A GENUINE QUESTION IS RAISED AS TO THE AUTHENTICITY OF THE ORIGINAL, OR (2) IT WOULD BE UNJUST OR INEQUITABLE TO ADMIT THE DUPLICATE IN LIEU OF THE ORIGINAL; DISSENTING OPINION Consistent with Lastimosa Case, a photocopy of a paper-based document qualifies as a duplicate, abandoning the former distinction between electronic and paper-based documents. Applying this rule, the Court En Banc held that certain exhibits, which the Court in Division had excluded solely because the taxpayer failed to present the originals for comparison, should be admitted because the BIR did not question their authenticity and there was no showing that admitting the photocopies would be unjust or inequitable. Although the taxpayer failed to timely seek reconsideration of the earlier exclusion, the Court relaxed the procedural rules in the interest of substantial justice, consistent with the principle that procedural rules are meant to facilitate, rather than defeat, the just resolution of cases. Accordingly, the Court admitted the photocopied exhibits as duplicates under the amended Rules on Evidence. Dissenting Opinion: original documents should have been presented under the CTA rules; party should sufficiently explain the unavailability of the originals; taxpayer did not seek reconsideration of the CTA in Division’s resolution excluding the documentary exhibits; there was no proper tender of excluded evidence; strict application of law under tax refund cases [Schaeffler Philippines Inc. v. Commissioner of Internal Revenue, CTA EB No. 2947 (CTA Case No. 10358), February 20, 2026]

THE ABSENCE OF A SEPARATELY PROMINENT IMPRINT OF “ZERO-RATED SALE” DID NOT AUTOMATICALLY NEGATE THE ZERO-RATED CHARACTER OF THE TRANSACTIONS. A VAT invoice must prominently indicate “zero-rated sale,” while invoices covering mixed transactions must clearly show the breakdown of taxable, exempt, and zero-rated components; however, substantial compliance with these invoicing requirements may suffice when the invoice itself clearly identifies the amount as pertaining to zero-rated sales. In this case, although the Court in Division denied the taxpayer’s refund claim because the phrase “zero-rated sale” was not separately and prominently imprinted on the invoice/OR, the Court En Banc held that the invoices contained a detailed breakdown expressly identifying the sales amount under “Zero Rated Sales,” which sufficiently disclosed both the nature and monetary value of the transactions. The Court found that this presentation substantially complied with the invoicing requirement because there could be no other reasonable conclusion than that the stated amount pertained to zero-rated sales, and the clients’ PEZA registrations further established that the sales were indeed subject to zero percent VAT [Schaeffler Philippines Inc. v. Commissioner of Internal Revenue, CTA EB No. 2947 (CTA Case No. 10358), February 20, 2026; Commissioner of Internal Revenue v. MSCI Hong Kong Limited, CTA EB No. 2939 (CTA Case No. 9884), November 9, 2025]

REVENUE ISSUANCES

RMC No. 89-2026, August 10, 2026

The BIR provides extension of the deadlines for the filing of tax returns and payment of corresponding taxes due thereon, including submission of required documents for taxpayers within the jurisdiction of Revenue District Offices of the BIR that were affected by the continued heavy rainfall brought about by southwest monsoon.

Covered Return Deadlines on August 10 to 17, 2026
Extended Period August 17, 2026
Covered Areas
  • Metro Manila
  • Ilocos Sur
  • Provinces of La Union and Pangasinan
  • Provinces of Abra, Apayao, Benguet, Ifugao, Kalinga, Mountan Province
  • Provinces of Bataan, Bulacan, Pampanga, Tarlac, Zambales
  • Provinces of Cavite, Batangas, Rizal and Mindoro
Further extension If extended deadline falls on a holiday, or non-working day, submission and/or filing shall be made on the next working day

BIR DEADLINES. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
AUGUST 17, 2026
SUBMISSION – List of Buyers of Sugar Together with a Copy of Certificate of Advance Payment of VAT made by each buyer appearing in the List by a Sugar Cooperative. Month of July 2026
SUBMISSION – Information Return on Releases of Refined Sugar by the Proprietor or Operator of a Sugar Refinery or Mill. Month of July 2026
e-SUBMISSION – Monthly e-Sales Report for All Taxpayers using CRM/POS and/or Other Similar Business Machines whose last digit of 9-digit TIN is Odd Number. Month of July 2026
e-FILING & PAYMENT/REMITTANCE (Online/Manual) – BIR Form 2200-M Excise Tax Return for the Amount of Excise Taxes Collected from Payment Made to Sellers of Metallic Minerals. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2200-C (Excise Tax Return for Cosmetic Procedures) with Monthly Summary of Cosmetic Procedures Performed. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 0620 (Monthly Remittance Form of Tax Withheld on the Amount Withdrawn from the Decedent’s Deposit Account) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or 1600-PT (Other Percentage Taxes Withheld) and Monthly Alphalist of Payees (MAP) – eFPS & Non-eFPS Filers. Month of July 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 1606 – (Withholding Tax Remittance Return for Onerous Transfer of Real Property Other Than Capital Asset Including Taxable and Exempt). Month of July 2026
e-FILING & e-PAYMENT/REMITTANCE – BIR Form 1600-VT (Monthly Remittance Return of Value-Added Tax) and/or BIR Form 1600-PT (Other Percentage Taxes Withheld) and 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) – National Government Agencies (NGAs). Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E. Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group D. Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group C.  Month of July 2026
AUGUST 17, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group B. Month of July 2026
AUGUST 17, 2026
REGISTRATION (Online Thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Accounts/Invoices and Other Accounting Records. Fiscal Year ending July 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1702 – RT/EX/MX. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return For Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending April 30, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1701Q (Quarterly Income Tax Return For Individuals, Estates & Trusts) and Summary Alphalist of Withholding Taxes (SAWT) – eFPS & Non-eFPS Filers. For the Quarter ending June 30, 2026
e-FILING & e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group A. Month of July 2026
e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded)  and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group E, D ,C & B.  Month of July 2026
AUGUST 17, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers. August 1-15, 2026

Articles

Archives

Recent Articles

Court of Tax Appeals Decisions Articles

Security and Exchange Commission Articles

Bureau of Internal Revenue Articles

Recent Articles