Month: September 2026

COURT OF TAX APPEALS (CTA) DECISIONS

LOA SERVED 860 DAYS AFTER ISSUANCE AND THE APPLICABLE 180-DAY AUDIT PERIOD HAD ALREADY EXPIRED RENDERS THE ASSESSMENT VOID. A revenue officer may examine a taxpayer and recommend a deficiency assessment only pursuant to a valid Letter of Authority (LOA), while the regulations require the LOA to be served within 30 days from issuance, otherwise it becomes null and void unless revalidated; consistent with this, the Supreme Court held that an unserved LOA that remains outstanding beyond 30 days becomes wholly unenforceable absent revalidation. Here, the LOA was served 860 days after issuance, with no showing that it had been revalidated. The Court therefore found that the LOA had already become void and unenforceable when served. Although the BIR regulations subsequently deleted the 30-day service requirement, and clarified that an LOA served beyond 30 days may still be considered valid, the Circular expressly limits this to cases where the applicable 180-day/240-day period for completion of the audit has not yet expired. That saving provision did not benefit the BIR because, when the LOA was eventually served, the 180-day audit period had already expired. The taxpayer’s failure to update its address and the BIR’s alleged difficulty in locating it likewise did not preserve the validity of the already expired LOA. Since the audit and examination were therefore conducted without a valid and enforceable LOA, the resulting deficiency assessment was void and ineffectual. (Floorcompany, Inc., v. Commissioner of Internal Revenue (“CIR”), CTA Case No. 11050, April 29, 2026)

LOA IS REQUIRED FOR AN ASSESSMENT OUTSIDE THE COVERED PERIOD; BIR CANNOT VALIDLY ARGUE THAT NEW LOA IS UNNECESSIARY FOR VAT ASSESSMENT DUE TO UTILIZATION OF EXCESS INPUT VAT. An RO may examine a taxpayer and perform assessment functions only pursuant to a valid LOA issued by the CIR or a duly authorized RD, and the LOA must identify the taxable period covered because it defines the extent of the RO’s authority and protects the taxpayer’s right to due process. The Supreme Court emphasized that an assessment made pursuant to an invalid LOA, or beyond the authority granted therein, is void and ineffectual; the RO cannot assess a taxpayer for a taxable period not covered by the LOA, since the RO must obtain another LOA if the BIR intends to expand the audit period. A LOA is required even when the BIR does not physically examine the taxpayer’s books, because the requirement depends on whether the taxpayer is subjected to an examination or audit, not on the manner by which the BIR obtains or verifies the information used in the assessment. Here, the BIR issued LOA authorizing the examination of books of accounts and other accounting records for all internal revenue taxes. Despite this limited authority, the BIR issued an Assessment Letter and a Denial of Protest for alleged deficiency VAT for the quarter ended June 30, 2021, a period clearly outside the coverage of the LOAs. The CIR argued that a new LOA was unnecessary because the deficiency VAT assessment resulted from utilization of excess input taxes rather than from an examination of books and accounting records. The Court rejected this argument, explaining that the BIR cannot avoid the LOA requirement simply by relying on information or systems that do not involve a physical examination of the taxpayer’s books; once the taxpayer is subjected to an examination or audit, the statutory requirement for prior authorization applies. Thus, the BIR should have issued another LOA specifically authorizing the examination and assessment for the quarter ended June 30, 2021. [CIR v. PMFTC, Inc., CTA EB No. 3009 (CTA Case No. 10714), April 13, 2026]

A TAXPAYER MAY BE TREATED AS CBL ONLY UPON PROOF OF THE REQUIRED BIR TAGGING AND PUBLICATION; THUS, WHERE THE BIR SHOWED ONLY CERTIFICATIONS OF UNSUCCESSFUL LOCATION EFFORTS BUT FAILED TO PROVE ACTUAL CBL DESIGNATION AND PUBLICATION, THE LOA REMAINED SUBJECT TO THE 30-DAY REVALIDATION AND 180-DAY AUDIT PERIODS, RENDERING IT AND THE RESULTING ASSESSMENTS VOID. A taxpayer may be given “Cannot Be Located” (CBL) status only after the BIR makes efforts to locate the taxpayer and obtains certifications from at least two specified offices or organizations that the taxpayer does not appear in their records; the taxpayer’s CBL status must then be reflected in the BIR records and submitted for publication on the BIR website and in at least two newspapers of general circulation. Here, although the BIR obtained certifications from the Makati City Business Permits Office and Barangays San Isidro and Bangkal indicating that taxpayer was not registered in their respective records, these certifications merely established efforts to locate taxpayer and did not prove that taxpayer was actually tagged as CBL in the BIR’s records. The only evidence offered was a Memorandum recommending that taxpayer be included in the CBL list and that the matter be referred for publication; the BIR presented no evidence that the CBL designation was actually made, or that taxpayer’s name was submitted and published on the BIR website and in at least two newspapers. The Court could not consider evidence that had not been formally offered. Consequently, the BIR failed to establish the factual predicate for exempting the LOA from the 30-day revalidation requirement and the 180-day audit-completion period. The LOA was therefore void, and because the assessments for taxable year 2017 were issued pursuant to an invalid LOA, they were likewise unenforceable and had to be cancelled and set aside. (Floorcompany, Inc., v. CIR, CTA Case No. 11050, April 29, 2026)

A WDL IS VALID ONLY WHEN THE TAX LIABILITY IS FINAL AND EXECUTORY; THUS, WDLS ARE PREMATURE BECAUSE THE TAXPAYER’S MR OF THE FDDA REMAINED PENDING; TAXPAYER CANNOT VALIDLY CHALLENGE THE ASSESSMENT FOR LACK OF A FINAL CIR DECISION. The Court of Tax Appeals has jurisdiction over “other matters” arising under the NIRC, including the validity of a Warrant of Distraint and/or Levy (“WDL”), but the BIR may resort to summary collection remedies only when the taxpayer’s liability has become delinquent, final, and executory, whether arising from self-assessed taxes or a final deficiency assessment. Here, the taxpayer received the second WDL and filed its Petition within the 30-day period; the first WDL was refused because its Motion for Reconsideration (“MR”) of the Final Decision on Disputed Assessment (“FDDA”) was still pending. The Court held that both WDLs were premature because the deficiency assessment had not become final and executory: the taxpayer timely protested the FLD/FAN, submitted supporting documents, and elevated the denial of its protest through an MR to the CIR. Collection through a WDL presupposes a final and executory liability; thus, the BIR could not enforce the assessment while the taxpayer’s administrative remedy remained pending. However, the Court could not rule on the merits of the deficiency assessment because, after denial of a protest by an authorized representative of the CIR, the taxpayer may either appeal to the CTA within 30 days or seek reconsideration from the CIR, and these remedies are mutually exclusive. Having chosen the latter, the taxpayer had to await the CIR’s action on its MR before seeking judicial review. Moreover, only one 180-day period is available for the CIR or his authorized representative to act, reckoned from submission of the supporting documents; the subsequent MR did not create a new 180-day period. Accordingly, the Court cancelled and set aside the WDLs and ordered the BIR to cease collection until the assessment becomes final and executory, but dismissed the Petition insofar as it sought review of the deficiency assessment, there being no final CIR decision on the pending MR. (Ivonclar Vivadent, Inc. v. CIR, CTA Case No. 11253, April 20, 2026)

TAXPAYER SHOULD APPEAL THE FDDA SIGNED BY THE CIR HIMSELF TO THE CTA; MOTION FOR RECONSIDERATION WILL NOT TOLL THE PERIOD. The CTA has jurisdiction over disputed assessments only when the taxpayer timely protests the assessment and timely appeals the CIR’s final decision to the CTA, while “other matters  include challenges to BIR collection remedies such as WDL and Warrant of Garnishment (“WOG”). Here, the CTA En Banc ruled that the original Petition for Review was only partly within the CTA’s jurisdiction. The FDDA signed by the CIR (Dulay) constituted the CIR’s final decision on taxpayer’s protest and the taxpayer should have appealed the FDDA to the CTA. Instead, taxpayer filed a letter-reply/motion for reconsideration with the CIR, which did not suspend or extend the period to appeal. Consequently, the assessments became final, executory, and demandable, depriving the CTA of jurisdiction to review their validity. The Court nevertheless recognized jurisdiction over the WOGs as “other matters.” The WDL, however, was challenged beyond the 30-day period; hence, the CTA had no jurisdiction over the WDL. In contrast, the WOGs were received within 30-day period deadline, giving the CTA jurisdiction over them. On the merits, the Court sustained the WOGs because taxpayer could not use a challenge to the collection remedy to indirectly reopen an assessment that had already become final. Taxpayer’s separate argument that the first LOA was invalid because it was served more than 30 days after issuance without revalidation was likewise rejected. The taxpayer did not object to the alleged defect when the LOA was served, nor did it raise the issue in its protest or original CTA petition; it surfaced only during cross-examination and was formally raised much later in a memorandum. Because the first LOA was valid, taxpayer’s challenge to the waivers extending the period to assess also failed. Accordingly, the CTA En Banc partially dismissed the Petition for lack of jurisdiction insofar as it sought nullification of the assessment and WDL, but denied it on the merits [Pentagon Gas Corporation v. CIR, CTA EB No. 3089 (CTA Case No. 10868), April 20, 2026]

15-DAY PERIOD TO FILE APPEAL TO CTA EN BANC IS RECKONED FROM DATE OF RECEIPT OF OSG, NOT BY THE BIR A Petition for Review to the CTA En Banc must be filed within 15 days from receipt of the Division’s resolution, with extension available only upon proper motion. Where the OSG is the government’s principal counsel, receipt by the OSG controls the appeal period, even if the resolution is received later by deputized BIR counsel. Thus, receipt by the OSG started the 15-day period, and petition filed by the BIR outside the 15-days period is dismissible. [CIR v. Sumitomo Corporation – Manila Branch, CTA EB No. 2998 (CTA Case No. 10412, April 7, 2026]

IN A DE NOVO CTA PROCEEDING, DOCUMENTS MERELY SUBMITTED DURING THE BIR AUDIT HAVE NO EVIDENTIARY VALUE ABSENT FORMAL OFFER; THUS, WHERE THE TAXPAYER FAILED TO FORMALLY OFFER THE ORS/SIS SUPPORTING ITS INPUT VAT CLAIM, THE CTA SUSTAINED THE DISALLOWANCE FOR FAILURE TO PROVE THE ASSESSMENT ERRONEOUS. The CTA is a court of record where cases are litigated de novo, requiring taxpayers to formally offer competent evidence to substantiate their claims; likewise, under the rules on evidence, allegations are not evidence and the burden of proof rests on the party asserting the claim. Here, the CIR disallowed input VAT because the supporting ORs and SIs were either missing or issued by non-VAT suppliers, and although taxpayer claimed that the documents were submitted during the BIR audit and that the amounts were instead treated as expenses/COS, it failed to formally offer the alleged ORs and SIs before the CTA. Since documents merely submitted to the BIR have no evidentiary value absent formal offer in court, taxpayer failed to prove that the assessment was erroneous; thus, the CTA sustained the disallowance of the unsupported input VAT (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

INPUT VAT IS CREDITABLE ONLY UPON COMPLIANCE WITH PRESCRIBED INVOICING REQUIREMENTS. A taxpayer claiming input VAT must establish that the supporting VAT invoices/official receipts comply with the prescribed invoicing requirements, including the nature of payment/service, TIN, address, VAT breakdown, and other required details; input tax on local purchases of goods is creditable upon consummation of the sale, not upon payment. Here, the CTA found that taxpayer’s supporting invoices/receipts failed to comply with these requirements, and taxpayer could not shift the burden to its suppliers because it was incumbent upon it to exercise due diligence in ensuring that its documents were compliant; its cash-flow records also could not cure the absence of the required information. However, the Court cancelled the disallowance because the records showed that the taxpayer’s TIN was actually reflected in the supporting document. The Court likewise upheld the disallowance in “out-of-period” input VAT because the purchases involved goods acquired in a different year, for which the input tax became creditable upon consummation, rather than upon payment. Accordingly, the CTA sustained the invoicing-related disallowance (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

TAXPAYER MUST CLEARLY RECONCILE ALLEGATION OF OVERCLAIMED INPUT VAT BY SUBMITTING RELEVANT AND VERIFIABLE SOURCE DOCUMENTS . The CTA is a court of record conducting trials de novo, and the taxpayer bears the burden of proving that an assessment is erroneous; assessments are prima facie presumed correct and made in good faith. Here, the BIR determined an overclaimed input VAT by comparing the Global Sources of Input Tax (GSIT) reflected in taxpayer’s AFS/AITR with the sources of input tax reported in its VAT returns. Although taxpayer presented reconciliations and claimed that its importation input VAT was supported by 664 pages of importation documents and that differences arose from the use of landed cost versus amounts recorded in the AFS/AITR, it failed to present the underlying importation documents and other supporting records necessary to verify these explanations and failed to adequately explain the variances in its reconciliations. Since the reconciliations, without the relevant source documents, could not be independently verified, and evidence not formally offered cannot be considered, taxpayer failed to discharge its burden of proving the assessment erroneous; thus, the CTA sustained the disallowance for overclaimed input tax. (Joyland Industries Corporation v. CIR, CTA Case No. 11269, April 15, 2026)

REVENUE ISSUANCES

Pursuant to Revenue Memorandum Circular (RMC) No. 97-2026 and under the National Internal Revenue Code (NIRC) of 1997, as amended, allowable system loss charges billed by electric distribution utilities to consumers are excluded from the 12% Value-Added Tax (VAT) computation to directly reduce end-user energy costs.

Date of Issuance September 14, 2026
Effectivity Immediately; applied prospectively from its effectivity and from the effectivity of ERC Resolution No. 26, Series of 2026, pursuant to Sections 12, 14, and 17 thereof
Nature of System Loss Charge The allowable System Loss Charge, within the cap approved by the ERC, is treated as a government-mandated pass-through cost
VAT Treatment The allowable System Loss Charge is excluded from Gross Sales for VAT purposes and is therefore not subject to output VAT
Creditable Withholding VAT (CWVAT) Since the allowable System Loss Charge is excluded from VATable gross sales, it is likewise not subject to CWVAT
Income Tax Treatment Unchanged. The VAT exclusion does not extend to income tax or the corresponding creditable withholding tax
Separate Identification The allowable System Loss Charge must be separately identified in the billing statement, invoice, or similar document
ERC Compliance Taxpayers must comply with applicable ERC rules and regulations governing the allowable System Loss Charge
Tax Compliance Taxpayers must comply with the relevant invoicing and gross sales provisions of the Tax Code and its implementing rules and regulations
Billing and Accounting Affected taxpayers must ensure proper billing, accounting, reporting, and disclosure of the System Loss Charge
Covered taxpayers –   must separately identify and properly account for the allowable System Loss Charge
  • Generation Companies (GenCos)
  • National Grid Corporation of the Philippines (NGCP)
  • Distribution Utilities (DUs)
Electric Cooperatives Covered taxpayer; must comply with the applicable ERC and tax requirements
Other Affected Taxpayers Must likewise ensure proper billing, accounting, reporting, and separate identification of the allowable System Loss Charge
Key Limitation The exclusion is for VAT purposes only; it does not mean that the System Loss Charge is excluded from taxable income or from income-tax withholding

BIR DEADLINES FROM SEPTEMBER 21, 2026 TO SEPTEMBER 27, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE  FILING/SUBMISSION
September 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayer. Non-eFPS Filers – Fiscal Quarter ending August 31, 2026
Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products – Fiscal Quarter ending August 31, 2026 
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550Q (Quarterly Value-Added Tax Return). eFPS & Non-eFPS Filers – Fiscal Quarter ending August 31, 2026
BIR Form 2551Q (Quarterly Percentage Tax Return) – eFPS & Non-eFPS Filers. Fiscal Quarter ending August 31, 2026
BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider). Fiscal Quarter ending August 31, 2026 

COURT OF TAX APPEALS (CTA) DECISIONS

REASSIGNMENT OF AUDIT TO ANOTHER EXAMINER PRIOR TO THE PAN-STAGE REQUIRES A NEW LETTER OF AUTHORITY (LOA); MEMORANDUM OF ASSESSMENT ISSUED BY A REVENUE DISTRICT OFFICER IS NOT SUFFICIENT. The Tax Code requires that the examination of a taxpayer’s books be conducted only by revenue officers specifically authorized under a valid LOA; an LOA is a special authority granted to particular revenue officers, not a general authority that may be used by any BIR officer. The Supreme Court held that the reassignment or substitution of revenue officers without a new or amended LOA violates the taxpayer’s right to due process and usurps the statutory authority of the CIR or his duly authorized representative. Any reassignment or transfer of a case to other revenue officers requires the issuance of a new LOA. Here, the examiners, who conducted the examination and recommended the issuance of the PAN, were not authorized under a valid LOA; their supposed authority rested only on Memorandum of Assignment issued by the Revenue District Officer, which could not substitute for an LOA. The subsequent LOA likewise did not cure the defect because it was issued long after the PAN. Thus, the PAN issued based on the unauthorized examination was void for lack of valid authority and violation of due process. [(Ammex I-Support Corporation v. Commissioner of Internal Revenue (CIR), CTA Case No. 11192, April 17, 2026)]

PHRASES IN THE ASSESSMENT NOTICE “YOU ARE REQUESTED TO PAY” OR “IF YOU ARE AMENABLE” DO NOT NEGATE DEMAND TO PAY; ASSESSMENT REMAINS VALID. A valid assessment must constitute a written notice and demand for a definite tax liability and must indicate a clear due date for payment, because the demand signals when penalties and interest accrue and informs the taxpayer of its remedies. Applying these principles, the CTA held that the FLD and FAN contained an unequivocal demand despite using the phrase “you are requested to pay,” since a demand may properly take the form of a request for payment; here, the FAN stated a definite amount and expressly provided June 30, 2022 as the payment deadline. Moreover, the title “Formal Letter of Demand” itself indicated the CIR’s intention to demand payment, and the phrases “you are requested to pay” and “if you are amenable” did not negate the demand. Thus, the assessment notices validly demanded payment of the deficiency taxes. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

3-YEAR PRESCRIPTIVE PERIOD WAS EXTENDED BY 420 DAYS DUE TO COVID-19  PANDEMIC. Internal revenue taxes must generally be assessed within 3 years from the last day prescribed for filing the return or the actual filing date, whichever is later, subject to the suspension provisions; during the COVID-19 pandemic, various legislations/regulations validly suspended the running of the prescriptive period during the specified ECQ/MECQ period. Applying these rules, although the original 3-year periods for 2018 income tax, VAT, WTC, and EWT liabilities had generally expired before the FLD was issued, the CTA held that the applicable COVID-19 suspensions validly extended the prescriptive periods by 420 days; consequently, the BIR’s right to assess remained timely for all the deficiency taxes involved, before the FLD was issued and received (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

TAXPAYER WAS NOT LIABLE FOR 30% RCIT ON PAGCOR’S USE OF THE CORPORATE OFFICES BECAUSE THE LEASE EXPRESSLY PROVIDED THAT SUCH USE WAS WITHOUT ADDITIONAL RENT. Income derived from taxable activities is subject to regular corporate income tax, while the tax treatment of PAGCOR-related income depends on the nature of the income actually earned; the CIR treated rental income from PAGCOR as subject to 30% RCIT on the theory that the reported rent supposedly covered both the gaming area and the corporate offices, with only the former being connected to exempt gaming activities. The CTA, however, found no factual or contractual basis for imputing rental income to the corporate offices because the Lease Agreement expressly provided that the rent pertained to the gaming premises, and that, upon payment of the stipulated rent, PAGCOR could continue using the Office Premises “without any further charge or payment therefor.” Thus, the taxpayer actually derived rental income only from the gaming premises and did not earn any additional rental income from PAGCOR’s use of the corporate offices. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

DISALLOWANCE OF MCIT CARRY-OVER WITHOUT EXPLANATION IS VOID. An assessment is void unless the taxpayer is informed in writing of the factual and legal bases thereof, as this is a substantive and mandatory requirement. Here, the FLD deducted the MCIT and income tax carried over to 2019 from the taxpayer’s total tax credits/payments, effectively disallowing these amounts, but failed to explain the factual and legal basis for their disallowance; thus, the taxpayer was not adequately informed of why these tax credits were rejected, rendering the corresponding assessment items void. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

INTEREST INCOME FROM A LOAN BY REAL ESTATE BUSINESS IS NOT SUBJECT TO VAT; BIR MUST PROVE INTEREST INCOME’S CONNECTION TO THE MAIN BUSINESS. VAT applies to services rendered in the course of trade or business, including transactions incidental thereto, but a transaction may be considered incidental only when there is an intimate connection between it and the taxpayer’s main business activity; moreover, interest income from loans is generally subject to VAT when earned by a lending investor, dealer in securities, financial institution, or an entity performing similar financing activities. Here, the taxpayer was principally engaged in the purchase, development, leasing, management, and sale of real and personal properties, and was not a lending investor, dealer in securities, or financial institution; although the interest income from its loan could potentially be VATable if the loan transaction were incidental to its business, the BIR failed to establish any clear relation or intimate connection between the loan and taxpayer’s main real estate business, merely stating that the income was not among its exempt activities. Thus, absent proof that the loan was incidental to petitioner’s VATable business, the interest income was not subject to VAT. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

PROCEEDS FROM DISPOSAL OF PROPERTY BY PAGCOR CONTRACTEE ENGAGED IN REAL ESTATE IS SUBJECT TO VAT. The tax exemption extended to PAGCOR contractees applies only to earnings derived from casino/gaming operations conducted under the PAGCOR franchise, while income from other activities remains subject to tax; likewise, transactions incidental to a taxpayer’s main business may be subject to VAT under the NIRC. Here, although the  proceeds from the disposal of property and equipment involved equipment previously used in casino operations, and the sale itself did not constitute earnings derived from PAGCOR’s gaming operations the disposal was considered a transaction incidental to petitioner’s business of purchasing, leasing, and selling real and personal properties, making the proceeds subject to VAT. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

RENTAL INCOME FROM PAGCOR’S USE OF CORPORATE OFFICE IS NOT SUBJECT TO VAT IF LEASE AGREEMENT PROVIDES THAT PAGCOR WILL NOT PAY RENT FOR THE USE THEREOF. Under the PAGCOR Charter and the Lease Agreement between the taxpayer and PAGCOR, only actual or constructively received rent income may be subjected to VAT. Here, rental income was based on the assumption that a portion of PAGCOR’s rent payments pertained to its use of the corporate offices, allegedly outside the exempt gaming activities; however, the lease agreement expressly provided that PAGCOR would incur no charge or further payment for its use of the Office Premises, resulting in no actual or constructive receipt of rent income by petitioner. Thus, there was no VATable rental income arising from PAGCOR’s use of the corporate offices, and the VAT assessment was cancelled. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

DISALLOWANCE OF INPUT VAT CARRY-OVER WITHOUT EXPLANATION IS VOID. An assessment or disallowance is void when the taxpayer is not informed in writing of the factual and legal bases thereof. Here, the BIR deducted input tax carried over to 2019 from the computed VAT due, effectively disallowing the amount and increasing the basic deficiency VAT, but neither the FLD nor the Details of Discrepancies stated the factual or legal basis for such disallowance. Accordingly, the disallowance of input tax carry-over was void, and after allowing the input tax credits, the taxpayer’s credits were sufficient to cover its output VAT for CY 2018, resulting in no basic deficiency VAT liability. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR CANNOT VALIDLY ASSESS TAXPAYER FOR FAILURE TO REFUND EXCESS WITHHOLDING TAX TO EMPLOYEES; BIR’S ASSESSMENT BASED ON MERE COMPARISON OF ALPHALIST AND AFS WITHOUT EXAMINING THE NATURE OF THE ACCOUNTS IS VOID. The penalty imposed on an employer or withholding agent applies when it fails or refuses to refund excess withholding tax to an employee, and does not provide a basis for assessing additional withholding tax merely from discrepancies in compensation expenses. Here, the BIR assessed deficiency WTC based on a discrepancy between compensation expenses reflected in taxpayer’s AFS and amounts reported in its Alphalist/BIR Form 1601-C, but its reliance on Section 252 was misplaced because that provision concerns the non-refund of excess withholding tax, whereas the assessment sought to impose additional withholding tax. The assessment also lacked sufficient factual basis because the amount taken from the Alphalist included non-taxable compensation, yet the BIR simply compared this amount with selected salary and payroll-related accounts in the AFS and treated the entire difference as compensation subject to WTC without examining the nature and taxability of the individual accounts. Thus, the BIR failed to establish both the legal authority and factual basis for the assessment, rendering the deficiency WTC assessment devoid of merit and subject to cancellation. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S EWT ASSESSMENT BASED ON MERE COMPARISON OF BOOKS/AFS AND WITHHOLDING TAX RETURN IS VOID; BIR MUST IDENTIFY THE SPECIFIC TRANSACTIONS AND NATURE OF INCOME PAYMENTS. An assessment must inform the taxpayer in writing of the specific factual and legal bases upon which it is made; otherwise, the assessment is void for failure to satisfy the statutory and constitutional requirements of due process. Here, the BIR assessed deficiency EWT based on discrepancies between the taxpayer’s expenses per books/AFS and its BIR Form 1601-E returns, classifying the alleged discrepancies as purchases of goods, purchases of services, rent, and professional fees and applying different EWT rates. However, the BIR merely invoked Section 57(B) of the NIRC and Section 2.57.2 of RR No. 2-98 without identifying the specific transactions covered, the nature of the income payments, the identities or classes of payees, or the particular subsection of Section 2.57.2 that prescribed the applicable withholding rate. This was insufficient because Section 2.57.2 contains several subsections covering different types of income payments and payees, each with corresponding EWT rates; thus, a general reference to the provision did not enable the taxpayer to determine which transactions were allegedly subject to EWT, why they were taxable, and how the rates were applied. Accordingly, the deficiency EWT assessment was declared void for failure to sufficiently state its factual and legal bases. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S DST ASSESSMENT (1) ON LOAN BASED ON YEAR-END BALANCE (2) PRIOR YEAR LEASE AND (3) RENT-FREE USE OF OFFICE IS VOID. DST is imposed on taxable debt instruments and certain lease agreements; however, a tax assessment must be supported by actual facts and transactions, rather than presumptions. Here, the BIR assessed deficiency DST by treating the year-end balances of taxpayer’s “Amounts owed by/to related party” accounts as loans or advances subject to DST. The Court found this improper because the amounts represented year-end balances, and the corresponding accounts already had substantial beginning balances, indicating that the amounts could have arisen from transactions in prior years. The BIR failed to determine whether the balances represented new loans or advances actually made during the year and did not present supporting documents, such as instructional letters, memoranda, vouchers, or other evidence establishing the existence of taxable loan transactions. The Court stressed that assessments cannot rest on reasonable or logical presumptions but must be grounded on actual facts. The DST assessments on the parking-area lease income and rental expense involving, respectively, were likewise improper because the relevant lease agreements were executed in prior years. Finally, the DST on alleged rent income was unfounded because the taxpayer did not receive any additional rent for PAGCOR’s use of the Office Premises, while the PAGCOR Gaming Premises lease was executed in prior year and was exempt from DST under the PAGCOR Charter. Accordingly, the BIR failed to establish that the assessed transactions were taxable DST transactions occurring within the audit period, and the entire deficiency DST assessment was cancelled. (Marina Square Properties, Inc. v. CIR, CTA Case No. 11092, June 29, 2026)

BIR’S FAILURE TO ADDRESS TAXPAYER’S ARGUMENTS IN THE PAN RENDERS THE ASSESSMENT VOID. The Tax Code requires that the taxpayer be informed in writing of the factual and legal bases of the assessment and that its defenses and supporting evidence be meaningfully considered; otherwise, the assessment is void for violation of administrative due process. The Supreme Court held that due process requires not merely an opportunity to be heard but also that the BIR actually consider and address the taxpayer’s explanations, with reasons stated for rejecting them. Here, the taxpayer filed a reply to the PAN, raising factual and legal arguments against the proposed assessment, but the subsequent FAN/ANs neither acknowledged nor addressed taxpayer’s arguments and were substantially identical to the PAN, except for the computation of interest. The subsequent protest against the FAN/ANs did not cure the defect because the denial of due process had already occurred at the assessment stage. Accordingly, the FAN/ANs were null and void, and the assessment and subsequent decision were cancelled and set aside. [(Ammex I-Support Corporation v. CIR, CTA Case No. 11192, April 17, 2026; Abraham Holdings, Inc.(Formerly Armadillo Holdings, Inc.) v. CIR, CTA Case No. 11088, June 8, 2026; Ozamiz City v. CIR, CTA Case No. 10828, June 18, 2026; CIR v. Marina Square Properties, Inc., CTA EB No. 3051, CTA Case No. 13049, May 21, 2026; Konica Minolta Marketing Services (Philippines) Inc., v. CIR,  CTA Case No. 10908, May 26, 2026; CIR v. United Graphic Printing Corporation, CTA Eb No. 3142, CTA Case No. 10610, May 26, 2026; CIR v. Serbiz Multi-Purpose Cooperative, CTA EB No. 3057, CTA Case No. 10369, May 28, 2026; CIR v. Justice Maria Lourdes P.A. Sereno, CTA EB No. 2996, CTA Case No. 10792, April 23, 2026; CIR v. Plastic Container Packaging Corporation, CTA EB No. 3039 (CTA Case No. 10095), April 22, 2026; CIR v. Neuftech Philippines, Inc., CTA EB No. 3012, CTA Case No. 10442, May 7, 2026)]

3-YEAR ASSESSMENT PERIOD APPLIES IF BIR FAILS TO PROVE FRAUDULENT INTENT. The extended prescriptive period applies only in cases of a false or fraudulent return with intent to evade tax or failure to file, while absent fraud or intentional falsity, the applicable period to collect an assessed tax is 3 years from the assessment. Here, the BIR failed to establish that taxpayer deliberately falsified her returns or intended to evade taxes; rather, she filed her AITRs, voluntarily paid income taxes, and reasonably relied on the BIR Form 2316 and tax withholdings of her employer, the Supreme Court, as statutory withholding agent. Thus, the alleged errors did not constitute fraud, making the extended prescriptive period inapplicable. (CIR v. Justice Maria Lourdes P.A. Sereno, CTA EB No. 2996, CTA Case No. 10792, April 23, 2026)

COOPERATIVE’S TAX EXEMPTION RETROACTS TO THE DATE OF ITS REGISTRATION. For cooperatives, while the law provides that tax exemption generally takes effect upon issuance of the Certificate of Tax Exemption, the initial issuance of such certificate is retroactive to the date the law took effect, provided that the cooperative was registered with the Cooperative Development Authority (CDA). Here, the taxpayer was registered with the CDA in 2009, and its Certificate of Tax Exemption issued in 2012 was its first certificate; hence, the certificate’s effectivity retroacted to 2009, making taxpayer exempt from income tax and VAT beginning taxable year 2009 despite the certificate being issued only in 2012. Thus, the taxpayer was not liable for the deficiency taxes assessed for TY 2009, CIR v. Serbiz Multi-Purpose Cooperative, CTA EB No. 3057, (CTA Case No. 10369) May 28, 2026)]

RECEIPT OF THE FORMAL LETTER OF DEMAND/FINAL ASSESSMENT NOTICE (FLD/FAN) PRIOR TO EXPIRATION OF 15-DAY PERIOD TO REPLY TO THE PAN RENDERS THE ASSESSMENT VOID. A taxpayer must be given 15 days from receipt of the PAN to submit a reply, and the BIR must wait for the taxpayer’s response or the lapse of the 15-day period before issuing the FLD/FAN; here, the taxpayer received the PAN on January 4, 2013, as shown by the notation on the PAN itself, giving it until January 21, 2013 to respond because the 15th day fell on a Saturday. However, the BIR issued the FAN on January 14, 2013, seven days before the expiration of the response period, thereby prematurely terminating respondent’s statutory opportunity to contest the PAN. The BIR’s unsupported claim that the PAN was served on December 28, 2012 was insufficient, as it presented no proof of service, while the PAN itself indicated receipt on January 4, 2013. The subsequent filing of a protest and administrative appeal did not cure the defect. [CIR v. Kuehne + Nagel, Inc., CTA EB No. 3024 (CTA Case No. 10216), April 15, 2026]

TAXPAYER CANNOT REFUND AN ERRONEOUSLY PAID IN A TAX ASSESSMENT CASE. SEE DISSENTING OPINION. A taxpayer seeking a refund or tax credit of erroneously or illegally collected taxes must first file a written administrative claim with the CIR, and both the administrative and judicial claims must be filed within two years from the date of payment; this two-year period is mandatory and jurisdictional. Here, the taxpayer paid tax during the reinvestigation of its TY 2009 assessment. Although the Court in Division subsequently found that the payments were made pursuant to a void assessment and ordered their refund, the Court En Banc held that the CTA had no jurisdiction to grant such relief. Moreover, with respect to all the payments, the taxpayer failed to file a written claim for refund or tax credit with the CIR within two years and did not even allege or pray for a refund in its Petition for Review. Accordingly, the En Banc modified the Division’s decision by deleting the refund/TCC while affirming that the assessments were void. Dissenting Opinion: The CTA has jurisdiction not only over disputed assessments and refund cases, but also over “other matters arising under the NIRC” or laws administered by the BIR. Moreover, it may resolve related issues necessary for the complete and orderly disposition of the case. Lastly, the period should be relaxed because of the peculiar circumstances of the case. Strict procedural rules should not be applied where they would allow the government to retain taxes it had no legal right to collect. [CIR v. Kuehne + Nagel, Inc., CTA EB No. 3024 (CTA Case No. 10216), April 15, 2026]

A SUBSEQUENT LOA IS VOID IF IT COVERS A PERIOD UNDER AN EARLIER LOA, WHICH HAS BEEN FULLY SETTLED. For income tax purposes, the examination and inspection of a taxpayer’s books shall be conducted only once in a taxable year, subject to limited exceptions, while the BIR regulations provide a “One LOA per Taxable Year” rule by generally allowing only one LOA for the same taxpayer, tax type, and period, except when a subsequent LOA is justified by circumstances such as the reassignment, retirement, or inability of the originally assigned revenue officers to continue the investigation. Applying these rules, the third LOA was infirm because it substantially overlapped with the period already examined under the First and Second LOAs. Moreover, none of the recognized exceptions justified the third LOA: even the alleged fraud, irregularity, or mistake had already been investigated under the Second LOA, and the alleged undeclared gain from the sale of land and improvements – which became the basis for the ad valorem penalties under the third LOA – had already been considered and ultimately abandoned in the FDDA issued under the Second LOA. More importantly, the assessments under the second LOA had already become final and were fully settled when taxpayer voluntarily paid the assessed deficiency taxes. thereby closing the audit and assessment process. Thus, the Third LOA improperly attempted to reopen and reassess matters that had already been examined, resolved, abandoned, and paid, in violation of the “One LOA per Taxable Year” rule and the principles of finality of assessments and orderly tax administration; consequently, the third LOA was void, and all assessments issued pursuant thereto were likewise void and without legal effect. [Orica Nitrates Philippines, Inc. v. CIR, CTA Case No. 10946, (April 15, 2026)]

BIR’S FAILURE TO INDICATE THE DUE DATE IN THE FAN RENDERS THE ASSESSMENT VOID. The Tax Code mandates that the taxpayer be informed in writing of the facts and law upon which an assessment is based, and jurisprudence establishes that a valid formal assessment must contain not only the computation of the tax liability but also a definite demand for payment within a prescribed period. A FAN that fails to state a definite due date is not a valid assessment because the due date determines when the taxpayer must pay, when penalties and interest may accrue, and allows the taxpayer to determine and exercise the proper remedies. Here, the FLD dated merely instructed taxpayer to pay the ad valorem penalties “within the time shown in the assessment notice,” but the FAN itself contained no due date, with the corresponding field left blank. Thus, there was no date certain or specific period within which petitioner was required to pay, resulting in the absence of a valid demand for payment. (Orica Nitrates Philippines, Inc. v. CIR, CTA Case No. 10946, April 15, 2026)

FLD/FAN ISSUED 10-DAYS AFTER THE RECEIPT OF THE PAN RENDERS THE ASSESSMENT VOID. The Tax Code requires the BIR to issue a PAN informing the taxpayer of the facts and law supporting the proposed deficiency assessment and to give the taxpayer 15 days from receipt of the PAN to respond before the FLD/FAN may be validly issued; these requirements are substantive due process safeguards, and failure to strictly comply renders the assessment void. In this case, the BIR issued the PAN but issued the FLD/FAN only 10 days later, without waiting for the full 15-day period, thereby depriving the taxpayer of the opportunity to contest the PAN and present supporting evidence. Accordingly, the FLD/FAN and the resulting deficiency tax assessment were declared void and without effect, and the assessments were cancelled and set aside. [(Transnational E-Business Solutions, Inc. v. CIR, CTA Case No. 10912,  April 13, 2026; CIR v. Travel Warehouse, Inc., CTA EB No. 3011, (CTA Case No. 10098), April 6, 2026)]

REVENUE ISSUANCES

Revenue Memorandum Circular No. 96-2026

The BIR clarifies the qualification of Export-Oriented Enterprises (EOE) to VAT Refund during the transitory period for securing a VAT Zero-Rating Certificate from the Export Marketing Bureau of the Department of Trade and Industry (EMB-DTI).

  • EOE that were passed on VAT on their local purchases and importation during the effectivity of RA 12066 on November 28, 2024 up to issuance of the VAT zero-rating certification by the EMB-DTI, may claim VAT refund for such passed-on VAT, provided that such certification was issued during the transitory period ending December 31, 2025
  • If EOE attains 70% threshold from the preceding year but did not obtain EMB certification (including transitory period), it cannot refund input VAT covering immediately succeeding year; but input VAT may be carried forward to subsequent taxable quarters until utilized
  • If VAT has been reimbursed, credited, adjusted, recovered from suppliers or utilized, it cannot be refunded.

BIR DEADLINES FROM SEPTEMBER 14, 2026 TO SEPTEMBER 20, 2026. A gentle reminder on the following deadlines, as may be applicable:

DATE FILING/SUBMISSION
SEPTEMBER 14, 2026 e-FILING – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld) – eFPS Filers under Group B. Month of August 2026
SEPTEMBER 15, 2026
REGISTRATION (Online thru ORUS or Manual) – Permanently Bound Loose-Leaf Books of Accounts/Invoices and Other Accounting Records. Fiscal Year ending August 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1702–RT/1702-EX/1702-MX– Fiscal Year ending May 31, 2026
eFILING & PAYMENT (Online/Manual) – BIR Form 1707-A (Annual Capital Gains Tax Return For Onerous Transfer of Shares of Stock Not Traded Through the Local Stock Exchange) – by Corporate Taxpayers. Fiscal Year ending May 31, 2026
eFILING & PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld). eFPS Filers under Group A. Month of August 2026
e-PAYMENT – BIR Forms 1601-C (Monthly Remittance Return of Income Taxes Withheld on Compensation) and/or 0619-E (Monthly Remittance Form of Creditable Income Taxes Withheld-Expanded) and/or 0619-F (Monthly Remittance Form of Final Income Taxes Withheld)  – eFPS Filers under Group E, D, C & B. Month of August 2026
SEPTEMBER 16, 2026 SUBMISSION – Consolidated Return of All Transactions based on the Reconciled Data of Stockbrokers – September 1-15, 2026
SEPTEMBER 20, 2026 eFILING & PAYMENT (Online/Manual) – BIR Form 1600 WP (Remittance Return of Percentage Tax on Winnings and Prizes Withheld by Race Track Operators) – eFPS & Non-eFPS Filers. Month of August 2026
AUGUST 25, 2026
SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – Non-eFPS Filers. Fiscal Quarter ending July 31, 2026
SUBMISSION – Sworn Statement of Manufacturer’s or Importer’s Volume of Sales of each particular Brand of Alcohol Products, Tobacco Products and Sweetened Beverage Products. Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2551Q (Quarterly Percentage Tax Return). Fiscal Quarter ending July 31, 2026
e-FILING & PAYMENT (Online/Manual) – BIR Form 2550-DS (Value-Added Tax (VAT) Return for Nonresident Digital Service Provider) – Fiscal Quarter ending July 31, 2026
AUGUST 29, 2026 e-FILING & PAYMENT (Online/Manual) – BIR Form 1702Q (Quarterly Income Tax Return For Corporations, Partnerships and Other Non-Individual Taxpayers) and Summary Alphalist of Withholding Taxes (SAWT). For the Quarter ending June 30, 2026
AUGUST 30, 2026
SUBMISSION – Proof of eFiled BIR Form 1702 – RT/EX/MX with Audited Financial Statements (AFS), 1709 (if applicable), and Other Attachments through Electronic Audited Financial Statements (eAFS) or Manually. Fiscal Year ending April 30, 2026
SUBMISSION – Soft Copies of Inventory List and Schedules stored and saved in DVD-R/USB properly labeled together with Notarized Sworn Declaration. Fiscal Year ending July 31, 2026
e-SUBMISSION – Quarterly Summary List of Sales/Purchases/Importations by a VAT Registered Taxpayers – eFPS Filers. Fiscal Quarter ending July 31, 2026
ONLINE REGISTRATION (thru ORUS) – Computerized Books of Accounts and Other Accounting Records. Fiscal Year ending July 31, 2026

Dear Clients, Colleagues and Friends:

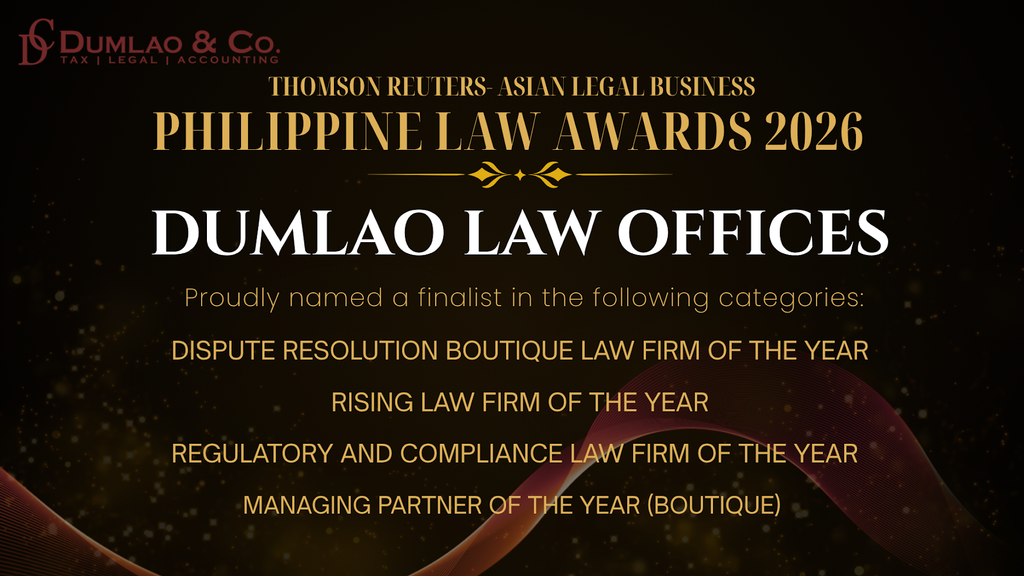
We are thrilled to share that Dumlao Law Offices has been named as a finalist in the 11th Annual ALB Philippine Law Awards 2026, presented by Asian Legal Business.

The firm has been recognized as a finalist in the following categories:

  • Dispute Resolution Boutique Law Firm of the Year
  • Rising Law Firm of the Year
  • Regulatory and Compliance Law Firm of the Year
  • Managing Partner of the Year (Boutique)

This recognition is a meaningful milestone for our firm and reflects our continued commitment to excellence in legal practice and service.

We are grateful for the continued trust and confidence extended to Dumlao Law Offices and remain committed to providing quality and dependable legal services.

Thank you for being part of our journey.

Articles

Archives